

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Bird Detection System for Airports Market Set to Expand at 8.01% CAGR from 2026 to 2032

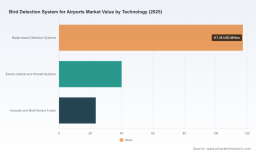
Worldwide Bird Detection System for Airports Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on Worldwide Bird Detection Systems for Airports delivers an executive-grade intelligence package designed to inform capital allocation, product strategy, and partnership decisions for 2026 and beyond. This preview surfaces the study’s strategic implications, synthesizes market momentum, and profiles the competitive landscape — while intentionally reserving the report’s granular segment-level metrics and procurement benchmarks for subscribers and licensed clients.
Worldwide Bird Detection System for Airports Market
Why this market matters to aviation decision‑makers in 2026
Bird strikes remain a persistent operational and financial risk for airports and airlines. Regulatory and operational forces are converging to make advanced detection a prioritized capital investment across commercial, military, and training-airfield portfolios. Our modeled market trajectory shows a sustained expansion from the 2020 baseline through the forecast window (2026–2032), driven by recurring investment cycles, retrofits at legacy airfields, and deployment of new solutions as part of broader smart‑airport programs. PW Consulting’s top-line projection incorporates historical data, technology adoption curves, and regulatory headwinds to produce a forward view grounded in measurable trends: the market rebounds strongly into the mid-2020s and continues on an upward course through the early 2030s, reflecting a compounded annual growth trend that decision-makers should treat as the baseline planning assumption for next‑stage strategy.
Worldwide Bird Detection System for Airports Market
Macro dynamics shaping vendor and buyer behavior
-
Regulatory pressure and standards: Aviation authorities worldwide, including the FAA, increasingly embed advanced detection requirements into Wildlife Hazard Management Plans and best‑practice guidance. Compliance timelines and audit expectations are creating a near‑term procurement pipeline for airports seeking to demonstrate modernized mitigation capabilities.
Worldwide Bird Detection System for Airports Market -
Operational focus on low‑altitude exposure: More than four out of five bird strikes worldwide occur in runway and approach/departure corridors below 800 feet. That operational reality is accelerating demand for sensors and analytics optimized for low‑altitude and ground‑level coverage — not only perimeter radars but also ground‑level thermal and acoustic solutions tailored to runway incursion windows.
-
Economic drivers: Bird strikes impose recurring direct and indirect costs in the aviation ecosystem, prompting risk managers and procurement teams to justify technology investments through measurable reductions in strike incidence and improved operational availability. This dynamic favors vendors who can present verifiable ROI cases and post‑installation performance monitoring.
-
Technology convergence: The fastest-moving procurements are for multi‑sensor solutions that fuse radar, electro‑optical/infrared imaging, acoustic sensing, and AI classification. Buyers are prioritizing systems that can deliver both tactical alerts (real‑time tower notification and patrol guidance) and strategic outputs (ecological trend analysis and seasonal forecasting).
What the market movement means for 2026 corporate strategy
-
Procurement leaders should treat 2026 as a window to convert pilots into scaled deployments. With regulatory expectations rising and a maturing vendor field, procurement strategies must move beyond single‑sensor pilots toward procurement frameworks that include integration, services, and lifecycle performance guarantees.
-
Product and R&D leaders need to prioritize sensor fusion, AI classification accuracy, and systems that reduce false alarms while preserving detection sensitivity at low altitudes. Investing in software platforms that offer remote configuration, predictive activity models, and API connectivity to airport operational systems will be a competitive differentiator.
-
Service and business model innovation is central. As airports seek predictable operational outcomes, vendors that offer outcome‑based contracts, managed detection-as-a-service, or hybrid capital‑plus‑subscription models will expand market access, particularly with regional airports and training facilities where capital budgets are constrained.
-
M&A and partnership opportunities are concentrated around two plays: acquired capabilities that accelerate multi‑sensor fusion and go‑to‑market partnerships that extend distribution into complex airport procurement processes and integrator ecosystems.
Competitive landscape — who’s shaping the field
The vendor field combines specialist radar makers, imaging/thermal system developers, integrators, and software-first entrants. Several established players set the performance and deployment benchmarks industrywide; PW Consulting’s assessment highlights their strategic positioning rather than absolute market shares.
-
DeTect, Inc. (Panama City, Florida) — A long-standing specialist in avian radar with a large installed base and products designed for True3D coverage and high update rates. DeTect’s emphasis on all‑weather performance and tower integration makes it a go‑to for airfields prioritizing persistent situational awareness. Recent deployments continue to validate demand in training and commercial contexts.
-
Robin Radar Systems B.V. (Netherlands) — Known for 3D avian radar products with fast scan speeds and classification capabilities. Robin’s technology is notable for deployments at major international hubs and for its emphasis on size and velocity discrimination, helping customers reduce nuisance alerts while preserving safety margins.
-
Accipiter Radar (Canada / USA) — Delivers software‑definable radar platforms and networked intelligence frameworks that enable multi‑sensor scalability. Their approach appeals to customers seeking expandable systems that can integrate future sensor types and distributed processing.
-
Volacom (Bulgaria) — Focused on thermal imaging and automated detection systems for ground‑level bird and wildlife management, offering continuous all‑weather detection and deterrence automation important for runway safety zones.
-
Xsight Systems (Israel) — Positions a fused millimeter‑wave radar and electro‑optical suite for runway threat detection, emphasizing automatic recognition and integrated auditory deterrence for rapid response at the ground level.
-
NEC Corporation (Japan) — Integrates S‑band radar with high‑sensitivity cameras and enterprise processing for airports pursuing broader smart‑airport architectures. NEC’s strength lies in systems engineering and integration with airport operational platforms.
-
AscendXYZ (Europe) — Provides mobile, end‑to‑end avian radar services with trailer‑mounted systems and real‑time risk modeling for coverage of large areas. This service model is attractive to airports requiring flexible or seasonal capacity without permanent infrastructure investment.
Each vendor brings a differentiated mix of hardware capability, data processing, and service model. Tactical procurement choices increasingly hinge on system openness, integration APIs, and the vendor’s ability to deliver demonstrable reductions in strike risk — not just technical specifications.
Practical deliverables in PW Consulting’s full report
The full study is constructed to be directly actionable for 2026 planning cycles. Key practical deliverables include:
-
Transparent market sizing and forecast methodology calibrated to market signals, procurement cycles, and regulatory timelines — providing a defensible financial baseline for capital planning.
-
Scenario analysis and sensitivity testing for alternative adoption rates, pricing trajectories, and regulatory tightening to stress-test investment cases.
-
Vendor scorecards and capability matrices that evaluate performance across detection range, low‑altitude sensitivity, classification accuracy, integration capabilities, and lifecycle support. (Note: detailed scorecard data and segment-level splits are available only in the full report to preserve competitive confidentiality.)
-
Procurement playbooks and contract language templates for fixed, mobile, and managed‑service deployments — including verification protocols for post‑installation performance guarantees.
-
Operational case studies documenting before/after metrics for strike incidence and patrol responsiveness, plus a checklist for tower integration and airfield operations alignment.
-
Integration and data architecture guidance for fusing sensor feeds into airport operational databases, C2 systems, and ecological monitoring platforms.
Rapid intelligence: a tactical checklist for 2026 procurement
-
Require proof points: insist on site‑specific performance verification and a minimum observation period before final acceptance.
-
Prioritize fusion: evaluate vendors on their ability to fuse radar with EO/IR and acoustic data, and to reduce false positives while preserving detection coverage below 800 ft.
-
Account for services: include maintenance, software updates, and data‑analytic subscriptions in total cost of ownership models rather than comparing hardware sticker prices alone.
-
Plan for scale: choose architectures that allow incremental sensor addition and networked multi‑site deployments to support regional airport groups or military bases.
Concluding strategic recommendations
Entering 2026, airport operators, integrators, and technology investors face an inflection point. Regulatory expectations, concentrated low‑altitude strike exposure, and a maturing vendor ecosystem create a window where timely investments can materially reduce operational risk and deliver sustainable value. PW Consulting’s study quantifies the market’s expansion through the forecast horizon and prescribes tactical steps to convert strategic intent into measurable operational outcomes.
For procurement officers and C‑level strategists, the imperative is clear: move beyond pilot projects to procurement structures that embed performance metrics, integration pathways, and service continuity. For vendors and investors, the opportunity is to differentiate through verifiable outcomes, open architectures, and business models that lower the barrier to adoption.
This preview highlights core directional insights; the full PW Consulting report contains the granular regional and technology splits, supplier scorecards, pricing benchmarks, and deployment case studies required to execute on the 2026 agenda. Access to the complete dataset and actionable annexes is available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Bird Detection System for Airports Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com