

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Truck Mirror System Market Poised for 7.5% CAGR Through 2026–2032

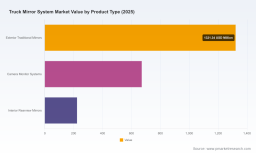
Worldwide Truck Mirror System Market — Strategic Preview for 2026 Decision‑Making
Executive summary
PW Consulting’s forthcoming market research brief on the Worldwide Truck Mirror System Market synthesizes seven years of historical observation (2020–2025) and a seven‑year forecast horizon (2026–2032) to deliver actionable findings for senior executives, procurement leads, R&D chiefs and corporate strategy teams. The industry is in a transitionary phase: traditional exterior mirrors remain fundamental, but digitally enabled camera monitor systems (CMS) and hybrid solutions are scaling rapidly. Our analysis shows the total market expanding from roughly USD 1.55 billion in 2020 to about USD 2.22 billion in 2025, and—at a compound annual growth rate (CAGR) of 7.5%—to an estimated USD 3.68 billion by 2032. Market concentration is moderate: the top three firms account for approximately 38.5% of value, and the top five for about 52.1%, leaving space for targeted challengers and vertical integration plays.
Worldwide Truck Mirror System Market
Why this matters for 2026 planning
- Capital allocation: forecasted mid‑single‑digit to high‑single‑digit growth supports continued investment in digital vision technologies, while still protecting legacy mirror manufacturing capacity for several years.
- Product strategy: OEMs and Tier‑1 suppliers must balance short‑term compliance and customer preferences for mirrors with medium‑term commitments to CMS platforms that deliver fuel efficiency and advanced safety features.
- M&A and partnership timing: moderate concentration and active regulatory windows create opportunistic timing for bolt‑on acquisitions, tech licensing, and strategic JV formation through 2026 and beyond.
Market trajectory and structural drivers
The mirror systems market is being reshaped by three mutually reinforcing forces. First, regulatory evolution—both exemptions that permit camera systems and standards that define field‑of‑vision requirements—has opened pathways for digital alternatives while preserving performance and safety baselines. Second, OEM aerodynamic and fuel‑efficiency programs are creating a halo effect that favors lower‑drag camera solutions in long‑haul and heavy‑duty applications. Third, supplier capability convergence (optics + electronics + software) is accelerating innovation cycles and changing supplier competitiveness from purely mechanical competence to systems integration capability.
Worldwide Truck Mirror System Market
These forces are reflected in the numbers: the market grew materially from 2020 to 2025 and our model—driven by technology substitution, replacement cycles, and increasing penetration of digital systems—projects sustained growth through 2032 at a 7.5% CAGR. That trajectory implies expanding addressable spend for vision subsystems, aftercare and retrofitting services, and software/maintenance revenue streams tied to camera ecosystems.
Worldwide Truck Mirror System Market
Technology and product dynamics
- Camera Monitor Systems (CMS): Rapid maturation of CMS hardware and human‑machine interface design is delivering demonstrable safety and aerodynamic benefits. ISO 16505 and parallel standards provide a technical route for regulatory acceptance, and several high‑profile OEM integrations and exemption filings demonstrate momentum.
- Hybrid approaches: Many operators prefer redundancy—retaining optical mirrors while adding camera-based close‑range views or blind‑spot overlays—so hybrid architectures remain strategically important in the medium term.
- Software, calibration and servicing: The "mirror" is increasingly a software‑centric platform. Calibration, OTA updates, image processing and maintenance contracts will be meaningful profit pools beyond hardware margins.
- Materials and supply chain: Specialized mirror glass, coatings and heated glass remain non‑commoditized inputs. Supply chain resilience for glass, optics and electronic components must be managed as part of procurement strategy.
Regulatory and standards landscape
Policy developments are a central determinant of adoption timing and are therefore a core scenario planning variable for 2026 decisions. In North America, time‑limited exemptions to traditional mirror requirements have allowed early commercial deployments of CMS platforms while regulators study long‑term rule updates. Internationally, UNECE and related regulations continue to raise field‑of‑vision expectations and carve technical paths for electronic alternatives. NHTSA research into camera systems and standards such as ISO 16505 are additional anchors for market acceptance.
For strategy teams, the practical implication is to treat regulatory trajectories as dynamic constraints: exemption programs enable pilots and early OEM integrations, but broad adoption will accelerate only as permanent regulatory clarity and harmonized standards emerge. Companies that engage proactively in standards work and exemption pilots will be advantaged in product validation and aftermarket certification.
Competitive landscape — capabilities and moves to watch
The market’s competitive topology blends global Tier‑1 suppliers, specialized mirror specialists, and technology‑centric entrants. Key players include mature systems integrators with multi‑modal portfolios, long‑standing OEM mirror manufacturers, and newer CMS specialists. Important dimensions of competitive advantage are systems integration, regulatory relationships, OEM platform access, aftermarket distribution and modular service offerings.
- Magna International (Aurora, Canada): A global integrator with advanced vision systems and hybrid camera‑mirror technologies. Strengths include deep OEM relationships and systems engineering capabilities that enable platform‑level integration on heavy‑duty vehicles.
- Samvardhana Motherson Reflectec (SMR) (Stuttgart/India operations): A specialist in exterior/interior mirrors with strong manufacturing scale and electric actuation expertise. Their hybrid and electrically extendable systems are a fit for fleets requiring durability and retrofittable solutions.
- Ficosa (Barcelona, Spain): Focused on rear‑view systems across trucks and light commercial vehicles, with product breadth that spans prismatic interior mirrors to full exterior ranges—positioned to serve OEMs seeking single‑source suppliers.
- Stoneridge, Inc. (Novi, Michigan): A CMS pioneer with regulatory progress and OEM integrations (e.g., deployment on major truck platforms). Their MirrorEye® product portfolio illustrates the route to substituting mirrors under regulatory exemptions.
- Specialized manufacturers (RETRAC, Rosco, Lucerix, K Source, INMESA, Muth, Tokai Rika, Murakami): These firms combine legacy OEM relationships, aftermarket distribution and niche product leadership. They are attractive partners for retrofit programs, regional distribution and targeted product innovations.
Recent industry moves—vehicle integrations announced by OEMs, CMS exemptions and renewals, and product showcases at sector events—signal that 2025–2026 is a high‑velocity window for product validation and commercial rollouts. Firms that secure OEM platform access and regulatory endorsments during this window will gain a durable lead.
Strategic implications and recommended actions for 2026
PW Consulting recommends a portfolio approach for decision‑makers in 2026, balancing near‑term revenue capture with longer‑term platform bets. Key actions include:
- Prioritize modular CMS capability: Invest in modular, software‑upgradable camera platforms that can be certified regionally and function across vehicle classes—this preserves optionality as regulations harmonize.
- Engage in regulatory processes: Allocate resources to participate in exemption pilots, standardization bodies and regulatory comment cycles to shape technical definitions and secure early approvals.
- Secure supply chain resilience: Lock multi‑source agreements for critical optics and coatings, and develop contingency plans for electronics and semiconductor supply to minimize production disruptions.
- Design aftermarket and service streams: Build calibration, update and servicing offerings as premium revenue lines tied to CMS installations and fleets’ uptime requirements.
- Pursue targeted M&A: Use the moderate concentration and active technology shifts to acquire niche CMS capabilities, software know‑how or regional distribution networks that accelerate time‑to‑market.
- Pilot hybrid installations: For risk‑averse fleets and regions with regulatory uncertainty, offer hybrid mirror + camera solutions to capture early revenue while enabling gradual technology migration.
What the PW Consulting report delivers
The full report is designed as a strategic toolkit for 2026 action. It includes:
- Scenario‑driven market forecasts through 2032 with sensitivity analyses and adoption curves by technology pathway.
- Competitive benchmarking and detailed vendor dossiers that assess engineering depth, OEM access, aftermarket channel strength and M&A posture.
- Regulatory mapping across major jurisdictions, including exemption timelines, standards alignment and recommended engagement strategies.
- Supply chain stress tests for key components (glass, coatings, cameras, electronics) and recommended mitigation playbooks.
- Commercial playbooks: go‑to‑market templates for OEM partnership negotiations, retrofit programs, pricing strategies and fleet conversion scenarios.
- Investment and M&A frameworks prioritizing targets by strategic fit, integration complexity and expected return windows.
How PW Consulting supports implementation
Beyond the report, PW Consulting offers tailored advisory packages to convert insight into execution: due‑diligence support for acquisitions, pilot design and measurement for exemption applications, supplier selection and contract negotiation support, and commercial rollout planning for OEMs and fleets. Our advisory engagement is structured to bridge boardroom strategy with the operational workstreams required to capture the forecasted growth.
Conclusion — a strategic teaser
The truck mirror systems market in 2026 sits at an inflection point: the total addressable market has expanded meaningfully since 2020, and sustained growth at a 7.5% CAGR through 2032 will create new value pools for hardware, software and services. The competitive field favors incumbents with systems integration capabilities and new entrants that can move fast on regulatory pathways and software differentiators. For leaders assessing capital deployment, partnership, or M&A in 2026, the window to act is now—but the tactical choices are nuanced and regionally contingent.
PW Consulting’s full Worldwide Truck Mirror System Market report provides the complete datasets, granular segmentation, and proprietary scenario matrices needed to finalize 2026 strategies. To access the in‑depth analysis, vendor profiles, and executable playbooks referenced here, please visit our official report page and request the full briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Truck Mirror System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com