

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cellulose Thickener Market Reaches USD 5,820 Million in 2025, Poised to Hit USD 8,511 Million by 2032 at a 5.58% CAGR

Worldwide Cellulose Thickener Market 2026: Strategic Imperatives from PW Consulting
PW Consulting today publishes an executive preview of our new Worldwide Cellulose Thickener Market report, designed to inform C-suite and investment decisions as companies prepare for 2026. The cellulose ether thickeners market has moved from an estimated USD 4,450.5 million in 2020 to approximately USD 5,820.0 million in 2025, and our proprietary model forecasts continued expansion into the next decade—reaching an estimated USD 8,511.3 million by 2032 under a central-case compound annual growth rate (CAGR) of 5.58% for the forecast window. This release synthesizes the strategic implications of that trajectory while deliberately reserving the report’s full segmentation detail for subscribers and report purchasers.
Worldwide Cellulose Thickener Market
Why this matters for 2026 planning
-
Timing and resource allocation: With sustained mid-single-digit CAGR through the forecast window, companies that align capex, R&D, and procurement cycles to 2026 market dynamics will protect margin and capture share as customer formulations evolve.
Worldwide Cellulose Thickener Market -
Regulatory and trade inflection points: 2024–2025 saw material regulatory and trade changes that reshape sourcing, compliance, and near-term product eligibility—making early compliance and supply diversification a high-return activity for 2026.
Worldwide Cellulose Thickener Market -
Consolidation pressure: Market concentration metrics in our study indicate a market structure where a handful of large players maintain meaningful aggregate share, yet significant opportunities remain for niche and regional specialists.
Macro dynamics shaping the market
From a top-line perspective, demand drivers remain diversified across industrial and consumer-facing end markets—construction, paints and coatings, food and beverage, pharmaceuticals and personal care, and energy-sector uses such as drilling. The combination of continued infrastructure activity in several regions and product reformulation trends in food and personal care underpins the baseline growth we model.
However, a complex overlay of supply-side shocks and regulation has re-weighted near-term risk:
-
Raw material cost volatility: Key upstream inputs—pulp and caustic soda—experienced notable price appreciation in recent quarters, tightening margins for commoditized grades and favoring vertically integrated or long-contracted producers.
-
Regulatory tightening: Updates to chemical safety frameworks and food/contact monographs have narrowed compliance windows for certain impurity profiles and compositional tolerances. Companies that preemptively validate manufacturing and documentation will avoid time-to-market slippage in 2026.
-
Trade friction and tariffs: Recent tariff adjustments on imports from certain regions have materially changed landed cost calculus for some buyers, accelerating local sourcing and regional production expansion discussions.
Competitive landscape — what incumbents are doing
The industry is characterized by a mix of global majors and specialized regional producers. Major players continue to pursue a multi-pronged strategy of product differentiation, capacity optimization, and regulatory positioning:
-
Dow: Continuing to leverage its Methocel™ franchise, Dow has introduced lower-VOC cellulose ether grades targeted at waterborne coatings—an example of how product innovation is now closely linked to sustainability and regulatory narratives.
-
Ashland: Capacity expansions for key HEC lines underscore a strategy to secure supply for formulation-driven customers in personal care and building chemicals, where service reliability is a competitive moat.
-
Shin‑Etsu Chemical and other established Asian producers: Certification and market-eligibility moves—such as food-grade and religious certification—are being used to unlock higher-margin channels and broaden geographical footprints.
-
Specialty and regional suppliers: European and smaller global players are leaning into application expertise for paints, tile adhesives, and specialty personal care formulations, offering formulation advisory and co-development as differentiation.
Our company profiles and competitor playbooks examine product portfolios, margin drivers, capacity maps, and recent transactions. We track notable recent events—new low-VOC product rollouts, targeted capacity investments, and certification updates—to show how these firms are positioning for 2026.
Operational themes and tactical implications for 2026
-
Procurement: Adopt layered sourcing strategies combining long-term contracts for pulp/caustic feedstocks with spot-market overlays. Hedging and strategic inventory build before expected seasonal cost peaks can be accretive to gross margin.
-
Product development: Prioritize low-impurity grades and formulations that address evolving regulatory thresholds and low-VOC preferences. Fast-track applications that can command premium pricing in food and pharma channels where compliance burdens create entry barriers.
-
Manufacturing footprint: Consider modular capacity expansions and toll-manufacturing partnerships in tariff-affected regions. For many buyers and suppliers, nearshoring offers an insurance policy against trade disruption.
-
M&A and alliances: Bolt-on acquisitions remain an efficient route to gain formulation expertise and localized customer access; joint ventures can be the fastest path to mitigate tariff exposure without full greenfield outlay.
-
Commercial strategy: Value-selling around regulatory compliance, supply reliability, and formulation support will be differentiated versus competing purely on price.
What PW Consulting’s full report delivers
The published report is constructed as a hands-on playbook for executives entering 2026 planning cycles. Highlights include:
-
Proprietary market-sizing and forecasting model spanning 2020–2032 with scenario-based outputs and sensitivity analysis tied to raw material and trade-policy scenarios.
-
Segment and application-level demand drivers, with growth outlooks and risk stratification to prioritize GTM efforts (note: fine-grained segment allocations and values are reserved for the full report).
-
Supply-side intelligence: plant-by-plant capacity mapping, utilization benchmarks, and a capacity pipeline tracker capturing announced expansions and likely commissioning timelines.
-
Regulatory and trade impact assessment, including practical compliance checklists and accelerated certification roadmaps for food, pharma, and cosmetics customers.
-
Commercial playbooks for procurement, pricing, and product launch—complete with negotiation levers, contract templates, and case studies from recent transactions.
-
Vendor and customer segmentation frameworks to help sales and R&D prioritize accounts and formulate channel strategies.
-
Strategic M&A scouting lists and valuation benchmarks for target identification, alongside integration risk matrices to guide post-merger value capture.
Strategic recommendations — a 90‑day action plan for 2026 readiness
-
Conduct an immediate supply‑chain stress test: map single‑source exposures, tariff vulnerabilities, and raw-material contract expiries that occur in 2026.
-
Fast-track regulatory audits for product families likely to face tightened impurity or composition limits; allocate a small cross-functional team to pursue certifications where required.
-
Prioritize one or two premium applications (e.g., food-grade or low-VOC architectural coatings) for which you can develop a differentiated product and pricing strategy within 12 months.
-
Evaluate opportunistic M&A or toll-manufacturing partnerships in tariff-impacted geographies to preserve cost competitiveness without overcommitting capital.
-
Design a customer-facing sustainability narrative tied to measurable product attributes (VOC, biodegradability, supply-chain transparency) to capture the growing willingness-to-pay in several end markets.
On market transparency and next steps
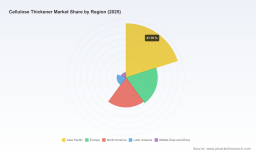
PW Consulting’s preview intentionally omits the granular regional and application-specific dollar splits found in the full study. This “trailer” approach is designed to demonstrate analytical depth while directing teams to the complete dataset and tools required to operationalize 2026 strategies—our interactive model, downloadable playbooks, and proprietary scenario matrices.
To receive the complete report, access the interactive forecast model, or schedule a briefing with PW Consulting’s cellulose ether practice, visit our report page. For clients preparing board-level briefings or investment memoranda for 2026, PW’s analysts are available to deliver tailored slide decks and one‑on‑one strategy sessions.
About PW Consulting: PW Consulting is a strategy advisory firm specializing in industrial chemicals and specialty materials. Our market intelligence combines bottom-up supply mapping, primary interviews across value chains, and scenario-based financial modeling to provide actionable guidance for executives and investors.
For detailed analysis of this topic, please visit the official page: Worldwide Cellulose Thickener Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com