

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
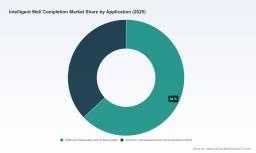
PW Consulting: Worldwide Intelligent Well Completion Market to Reach USD 2,810.26 Million by 2032 at 8.45% CAGR — Offshore Deepwater Segment Leads with USD 1,003.42 Million

Worldwide Intelligent Well Completion Market: Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Intelligent Well Completion Market report (base year 2025). As operators and suppliers plan budgets and partnerships for 2026, this briefing highlights the macro trajectories, competitive dynamics, and near-term commercial risks that will shape capital allocation and technology choices—without disclosing the granular segment tables reserved for the full report.
Worldwide Intelligent Well Completion Market
Why this report matters for 2026 planning
Intelligent well completions are moving from niche demonstrations to mainstream field architectures. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 8.45% over the forecast window, supported by accelerating deployments in deepwater, electrified completions, and multi-zone control architectures. With a base-year vantage point in 2025, PW Consulting’s report synthesizes historical performance, near-term project ramps, and supplier capability to deliver actionable guidance for procurement, technology roadmaps, and partner selection in 2026.
Worldwide Intelligent Well Completion Market
- Investment timing: The sector is entering a phase of steady global revenue growth—continuity that favors multi-year supplier partnerships and staged technology rollouts rather than one-off trials.
- Risk calibration: Near-term cost inflation and trade-policy shifts mean that procurement processes must embed scenario modeling for materials and logistics.
- Value capture: Operators can improve EUR and recovery through digital-first completions, but capture requires integrated lifecycle plans combining downhole hardware, telemetry, and software services.
Market trajectory—what the topline numbers indicate
From our base year lens, the intelligent completion market has moved beyond early-adopter volatility into a structurally growing industry. Market revenues show a multi-year upward path reflecting a steady compound growth profile. This growth is being driven by continued investment in deepwater pre-salt plays, migration toward electric completions and multi-zone control, and the increasing use of permanent downhole sensing and fiber-optic systems for production optimization.
Worldwide Intelligent Well Completion Market
For executives, the message is clear: the market is large enough and growing fast enough that technology decisions made in 2026—platform selection, architecture standardization, and supplier contracting model—will materially influence portfolio performance for the remainder of the decade.
Competitive landscape—who is shaping standards and supply
The market structure demonstrates meaningful concentration among a handful of global systems suppliers and specialized technology firms. Top-tier energy services companies have the scale to deliver integrated intelligent completion packages, while niche and regional providers focus on differentiated components, autonomous control systems, and intervention tools.
- Global integrators: Major service groups—companies with deep completion systems portfolios and global project footprints—continue to win large-scale deepwater contracts and to invest in electric and telemetry-enabled platforms. Their offerings bundle permanent gauges, interval control valves, wet-mate connectors, and surface-to-subsurface integration services.
- Specialists and independents: Technology-focused firms are advancing inflow control devices, downhole robotics, and wireless/autonomous control solutions that simplify installations and reduce running costs—creating modular alternatives for field architects.
- Service partners and regional houses: Regional service firms and national oilfield providers are increasingly important in local market access, running expertise, and operator-specific interface adaptations, particularly in the Middle East and Latin America.
Recent contract awards and deployments illustrate these dynamics. In late 2025, several large completions contracts were awarded for ultra-deepwater pre-salt projects and multi-zone developments, underscoring the strategic importance of scale and bundled delivery capability. In parallel, milestone deployments of long-lateral, high-zone-count intelligent completions have set new operational benchmarks and validated all-electric and fiber-enabled architectures in challenging environments.
Report coverage—practical, transaction-focused deliverables
PW Consulting’s full report is designed for commercial teams, CTO offices, and asset managers who need executable intelligence rather than academic summaries. Key operational outputs include:
- Multi-scenario revenue and demand models through the forecast window, allowing sensitivity testing against oil-price curves, electrification adoption rates, and drilling activity scenarios.
- Procurement playbooks that map risk allocation options for CapEx vs. OpEx delivery models, warranty frameworks, and incentive-aligned contracting structures for long-term monitoring services.
- Vendor evaluation frameworks and contract checklists to weigh trade-offs between turnkey systems from global integrators and component-level sourcing from specialist suppliers.
- Engineering-to-commercial alignment guides that translate downhole architecture choices into surface system requirements, intervention plans, and contingency budgets.
- Case studies of recent field-scale deployments highlighting technical pitfalls, OPEX impacts of permanent sensing, and lessons in running and intervention logistics for multi-zone completions.
To preserve the utility of this preview and adhere to the “trailer” principle, detailed segment-level forecasts and supplier share tables are embargoed to the full report. PW Consulting’s proprietary models, including component-level cost curves and regional demand scenarios, are made available in the complete deliverable.
Dynamics and near-term supply-side risks
Several material and regulatory trends are compressing margins and reshaping vendor selection criteria in 2026:
- Raw material inflation: Supply disruptions in metals markets have driven sharp price growth for aluminum and steel inputs in early 2026. These swings materially affect the bill-of-materials for completion hardware and encourage procurement teams to lock prices or adopt hedging strategies.
- Trade policy and tariffs: Expanded tariff measures on certain non-compliant steel and aluminum products raise landed costs and increase the attractiveness of localized manufacturing or near-shore sourcing for critical components.
- Standards and qualification: Industry standardization efforts advanced in 2025 around control valve qualification and electric-completion interfaces. Participation in these standards bodies is now a strategic lever—shaping interoperability and influencing long-term adoption curves for proprietary systems.
- Operator adoption patterns: High-value pre-salt and deepwater fields remain adoption leaders, with operators scaling intelligent completions into large portfolios. As adoption broadens, suppliers must prove lifecycle reliability and low-intervention performance to win repeat business.
Strategic implications for executives in 2026
Executives making 2026 decisions should orient around four practical priorities:
- Lock the supply chain and cost base: Negotiate multi-year material procurement and explore near-shore fabrication partnerships to mitigate tariff and freight volatility. Include material-cost pass-through clauses that are index-linked to producer-price or metal-spot indices.
- Prioritize systems that lower lifecycle interventions: Favor technologies and vendors with demonstrable reductions in well intervention frequency. The economic value of reduced intervention is often greater than incremental upfront hardware cost.
- Standardize interfaces and participate in specs: Engage in API and industry working groups to influence interoperability standards—reducing vendor lock-in risk while accelerating field-scale rollouts.
- Design contracts for performance alignment: Move beyond pure supply agreements toward outcome-linked models (availability, production uplift, or reduced intervention). Incorporate digital twin and data-sharing terms to unlock joint optimization opportunities.
Vendor watch—what to watch for among market leaders
Large service integrators continue to command a meaningful portion of market activity through bundled systems and global execution capability. At the same time, targeted innovations from independents—wireless autonomous control, advanced inflow control devices, downhole robotics—are reshaping the supplier value ladder. Our report profiles the strategies, recent wins, and technical roadmaps of the sector’s leading players, evaluating their ability to deliver scale, reliability, and software-enabled services.
Notably, several major contract awards and deployments announced in late 2025 validate both scale and technology shifts. These include multi-well, ultra-deepwater contracts for intelligent completion packages and high-zone-count deployments that demonstrate the practicality of all-electric and fiber-based monitoring solutions in long-lateral wells. Such wins are instructive: they signal which supplier capabilities will be essential for large offshore developers and which technologies are maturing into repeatable field solutions.
Next steps and how to access the full intelligence
PW Consulting’s full Worldwide Intelligent Well Completion Market report delivers the detailed segment forecasts, supplier market shares, and procurement templates needed for 2026 decision-making. The public preview you have read is intended to frame the strategic choices and near-term risks; it intentionally withholds the granular forecasts and company-by-company market share tables that underpin commercial negotiations.
For executives preparing 2026 budgets or negotiating multi-year completion contracts, the full report is a practical tool—combining scenario-ready financial models, supplier scorecards, and contract language recommendations. To request an executive briefing and obtain access to the full deliverable, contact PW Consulting’s Industry Research Desk or visit our reports page.
PW Consulting’s analysts remain available to run tailored sensitivity scenarios for your asset base, provide supplier due-diligence workshops, and support negotiation strategy for intelligent completion programs being tendered in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent Well Completion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com