

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Dairy Packaging Market to Reach USD 33.17B by 2032; 4.89% CAGR
By pmarketresearch, 2026-07-22
Dairy Packaging Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented introduction to our full Dairy Packaging Market study. This preview synthesizes macro trajectory, regulatory shocks, technology inflection points, and competitive dynamics that will matter to executives planning through 2026 and beyond. It demonstrates the analytical depth you can expect from the full report while intentionally withholding the detailed subsegment datasets and commercial tables reserved for subscribers.
Dairy Packaging Market
Market Trajectory: Scale, Momentum, and What It Means
The dairy packaging market has been resilient through 2020–2025, expanding from approximately USD 18.5 billion in 2020 to USD 23.7 billion in 2025 (base year). Our forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of roughly 4.89%, projecting a market size north of USD 33 billion by 2032. These macro figures underline two strategic truths for 2026 planning:
Dairy Packaging Market
- Growth is steady, not meteoric. Companies should prioritize margin capture and portfolio optimization over pure-volume bets.
- Incremental innovation—material substitutions, aseptic processing efficiencies, and packaging format redesign—will be the primary drivers of share shifts rather than market expansion alone.
The market concentration metrics further sharpen the competitive lens: the top three and top five suppliers together account for a relatively modest share of global revenue (CR3 ≈ 28.5%; CR5 ≈ 35.2%), signifying a moderately fragmented ecosystem. For large multinational suppliers this means scale advantages can be leveraged, but specialty and regional players retain clear niches and acquisition appeal.
Dairy Packaging Market
Dynamics Shaping Strategic Choices in 2026
Three intersecting dynamics will disproportionately influence commercial outcomes next year:
- Regulation and producer responsibility — Since 2025, regulatory action on recycled-content mandates and producer responsibility schemes has accelerated. Notable examples include state-level mandates that phase in minimum post-consumer recycled content requirements and national/regional packaging laws that set binding recycled-content targets with clear enforcement timelines. These rules are reshaping upstream resin demand, qualification cycles for recycled feedstocks, and the economics of mono-material vs. multi-layer barriers.
- Sustainability-driven material change — Suppliers and brand owners are rapidly trialing paper-based barriers, bio-attributed polymers, and recycled-content plastics. Aseptic paper barrier solutions and alu-free carton architectures are moving from pilot to early commercial deployment, enabled by equipment upgrades and barrier technology advances.
- Operational resilience and supply-chain volatility — Resin price swings, feedstock availability for PCR (post-consumer recycled) materials, and capacity constraints for aseptic filling lines are creating premium returns for integrated suppliers who can guarantee material specifications and on-time delivery.
These dynamics translate into concrete near-term pressure points: capital allocation to retrofit or replace filling lines, tighter technical and contractual specifications for recycled resins, and an acceleration of supplier consolidations and cross-sector partnerships.
Competitive Landscape: Who’s Shaping the Agenda
The market features a blend of legacy carton specialists, flexible-packaging innovators, resin producers, and converters. Key players we profile in the report include global carton-system leaders, flexible-packaging multinationals, and resin suppliers that are rapidly moving downstream through partnerships and product attribution programs.
- Tetra Pak (Pully, Switzerland) — Continued leadership in aseptic carton systems, with investments to scale paper-based barrier solutions into higher-speed filling lines.
- SIG Combibloc Group (Neuhausen, Switzerland) — Active in aluminum-free, full-barrier aseptic cartons and early commercial rollouts across European and emerging markets.
- Elopak (Oslo, Norway) — Expanding sustainable carton capacity in North America and emphasizing gable-top formats for both dairy and plant-based beverages.
- Amcor, Berry Global, Huhtamaki — Large converters leaning into flexible films, bottles, and paperboard trays while balancing recycled content mandates and functional barrier needs.
- SABIC, INEOS Styrolution — Resin suppliers active in bio-attributed and recycled polymer streams; their feedstock strategies and certification capabilities are becoming strategic assets for converters and brand owners.
- Specialists like ProAmpac, Winpak, Alfipa — High-performance flexible solutions, butter wraps, PET bottles and closures remain critical to category differentiation and SKU-level economics.
Recent developments exemplify the competitive themes above: the first commercial deployments of alu‑free aseptic cartons in Europe, paper-based barrier cartons scaled to high-speed lines in Asia, new regional sustainable-production capacity in the United States, and launches using recycled-content polystyrene in retail channels. These moves reflect suppliers converting R&D into commercial propositions that directly address 2026 regulatory and customer requirements.
What the Full Report Delivers (Practical, Transaction‑Ready Tools)
Our comprehensive study goes beyond high-level narrative to provide the operational intelligence that procurement, R&D, and corporate strategy teams need to act in 2026. Highlights include:
- Scenario models that stress-test volume, price, and raw-material assumptions under alternative regulatory timelines and feedstock availability.
- Supplier scorecards that evaluate technical capability, sustainability credentials, geographic reach, and capital intensity—designed for rapid sourcing decisions and RFP shortlists.
- Investment playbooks for plant retrofits and packaging-line upgrades, including CAPEX/OPEX trade-offs and payback sensitivity across material alternatives.
- Commercial levers and SKU rationalization frameworks for SKU-level margin recovery, substitution strategies, and cost-to-serve optimization.
- Policy-impact matrices that translate pending and enacted regulations into action steps for product design, labeling, and reporting obligations.
Note: while the full report includes granular breakdowns across material types, packaging formats, and regional markets, this preview intentionally omits those subsegment tables and datasets to preserve our subscribers’ competitive advantage.
Strategic Imperatives for 2026
For executives mapping capital, procurement, and M&A decisions in 2026, five priorities emerge:
- Define a materials roadmap — Establish a 3–5 year plan for recycled and alternative-material adoption that aligns R&D, procurement, and customer commitments. Prioritize certification pathways for recycled feedstocks and bio-attributed resins early in the adoption curve.
- Flex capital toward modularity — Invest in modular filling and converting equipment that supports multiple formats (aseptic cartons, spouted pouches, bottle sizes). Flexibility reduces obsolescence risk amid shifting consumer and regulatory requirements.
- Secure feedstock through partnerships — Long-term offtakes, joint ventures with resin producers, and investments in PCR sorting/processing reduce exposure to volatile spot markets and ensure compliance with recycled-content mandates.
- Use procurement as a competitive weapon — Move beyond price-only sourcing: specify circularity clauses, supply continuity SLAs, and joint innovation KPIs in contracts with converters and resin suppliers.
- Target bolt-on M&A and strategic partnerships — Fragmentation and emerging material technologies create opportunities to acquire niche capabilities (e.g., barrier coatings, aseptic filling retrofits, or regional converter footprints) at attractive valuations.
Scenarios and Risks — What Could Upset the Base Case
Our base-case projection (CAGR ~4.89%) assumes phased regulatory implementation and steady adoption of sustainable materials. Upside risks include faster-than-expected consumer adoption of long-life aseptic formats and a rapid scaling of affordable recycled feedstocks. Downside risks are centered on supply-chain disruptions, unexpected regulatory stringency that raises compliance costs, and technological setbacks in barrier technologies that impede substitution of incumbent plastics.
Preparing for volatility means stress-testing supply agreements, building inventory and dual-sourcing where feasible, and investing in rapid qualification pipelines for new materials.
How to Use This Preview
Consider this document a roadmap to the decision points your executive team will face in 2026. Use it to frame board-level debates, prioritize capital requests, and align cross-functional owners around a coordinated materials and procurement strategy. For teams preparing bids, tender responses, or plant investment proposals, the full PW Consulting report supplies the datasets, supplier rankings, and scenario models required to substantiate recommendations and secure approvals.
Next Steps
PW Consulting’s full Dairy Packaging Market report contains the proprietary subsegment tables, regional and application splits, and transaction-grade supplier profiles that underpin the strategic insights summarized here. To access the complete dataset, interactive dashboards, and our team’s advisory services (including scenario workshops and supplier selection support), please visit the PW Consulting report page.
In a market defined by steady growth, rising regulatory pressure, and rapid material innovation, 2026 will reward companies that convert strategic clarity into operational readiness. This preview maps the landscape—our full analysis provides the tactical instruments to win within it.
For detailed analysis of this topic, please visit the official page: Dairy Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Computer Cart Market to Grow at 6.98% CAGR, Reaching USD 344.8M by 2032
By pmarketresearch, 2026-07-22
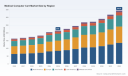
Medical Computer Cart Market — Strategic Preview for 2026 Decision-Makers
As health systems accelerate digital transformation and seek to improve point-of-care efficiency, medical computer carts have emerged as essential infrastructure for bedside documentation, medication administration, telehealth, and mobile diagnostics. PW Consulting’s latest study, with a 2025 base year and a forecast spanning 2026–2032, quantifies this momentum: the global market expanded from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.98% into the forecast window, approaching roughly USD 345 Million by 2032. For executives planning purchases, product road maps, partnerships, or M&A activity in 2026, this report provides the actionable intelligence needed to convert macro momentum into competitive advantage.
Medical Computer Cart Market
Why This Study Matters for 2026 Strategic Decisions
-
Timing and scale: With consistent mid-single-digit CAGR and a clearly defined growth arc from post-pandemic stabilization into renewed capital cycles, providers and suppliers must align 2026 investments with the market’s second growth phase. Decisions made this year—on procurement cycles, product launches, or strategic alliances—will determine share capture as adoption broadens across care settings.
Medical Computer Cart Market -
Concentration and competitive dynamics: The market shows clear leader clustering (CR3 ~62.5%, CR5 ~78.3%), which creates both barriers and opportunities. Incumbents leverage scale, standards compliance, and integrated solutions; challengers can win by specializing in vertical niches, aftermarket services, or rapid innovation in power management and telehealth integration.
Medical Computer Cart Market -
Regulatory and reimbursement clarity: Baseline regulatory expectations—electrical safety standards (UL/EN/IEC 60601-1), quality systems (ISO 13485:2016, ISO 9001:2015), and FDA 510(k) routes when diagnostic or powered subsystems are integrated—are now well established. Reimbursement for carts typically falls under durable medical equipment constructs rather than new CPT/DRG carve-outs, meaning commercialization strategies must emphasize procurement economics and return-on-workflow rather than reliance on new billing codes.
Market Trajectory: The Numbers You Need (High-Level)
The headline figures are instructive: a clearly growing installed base and rising average unit sophistication. Between 2020 and 2025, the market experienced steady expansion driven by three vectors—digitization of bedside workflows, heightened infection control demands, and the rapid normalization of telehealth. Looking ahead, the projected CAGR of 6.98% signals continued healthy demand through 2032. These aggregated figures validate investments in modular, standards-compliant platforms and battery/power management innovations that extend uptime and support continuous point-of-care use.
Key Strategic Imperatives for 2026
-
Design for interoperability and standards compliance: Buyers prioritize carts that integrate cleanly with EHRs and medical devices and that meet UL/EN/IEC 60601-1 safety standards. Vendors without a robust compliance and documentation capability will face longer procurement cycles and credentialing friction in large health systems.
-
Differentiate on power and uptime: Battery management systems and fast-swap architectures are shifting from convenience features to procurement decision criteria. Carts that demonstrably reduce downtime, simplify charging logistics, and extend battery health will command pricing premiums and stronger procurement preference.
-
Embed infection prevention into product and service offers: Antimicrobial coatings, easy-to-disinfect surfaces, and service contracts that ensure ongoing sanitation are increasingly table stakes. These features are particularly persuasive in acute care purchasing committees and in systems prioritizing hospital-acquired infection reduction.
-
Service and lifecycle economics win RFPs: As reimbursement regimes do not create new revenue streams for carts themselves, procurement decisions are driven by total cost of ownership (TCO) and lifecycle service agreements. Vendors offering multi-year warranties, on-site maintenance, and remote monitoring of battery and usage analytics are best positioned.
-
Leverage telehealth as a differentiator: Integrated camera positioning, device mounting, and platforms optimized for remote consultations are now decisive features for carts used in virtual care workflows. Products that make telehealth a native capability—rather than an afterthought—unlock new buyer segments outside traditional inpatient procurement flows.
Competitive Landscape — Who to Watch
The market is a mix of established ergonomics and medical hardware companies, specialist cart manufacturers, and global electronics firms that have adapted industrial platforms for healthcare. Key players exemplify strategic approaches worth benchmarking:
-
Capsa Healthcare (Canal Winchester, Ohio): Known for integrated mobile computing workstations and telehealth platforms, their Trio series and updated Tryten telehealth cart demonstrate a strategy focused on point-of-care EHR access, medication management, and remote consultations—exactly the capabilities health systems prioritize today.
-
Ergotron (Eagan, Minnesota): Ergotron’s CareFit Slim and Mosaic product lines emphasize certified medical safety, ergonomic adjustability, and integrated power systems—attributes that play well in acute care and imaging environments where standards compliance and ergonomics influence adoption.
-
RDP Health (Burgess Hill, UK): With tailored workstations designed for NHS workflows (EPR, EPMA, and phlebotomy), RDP’s warranty and battery-indicator features illustrate how specialization for public health systems can create defensible procurement wins.
-
Lund Industries / DataCart (Northbrook, Illinois): Their focus on customization, antimicrobial coatings, and multi-year warranties shows the commercial value of integrating infection control and long-term service into the core proposition.
-
Advantech (Taiwan / US operations): Advantech’s AMiS series blends industrial-grade electronics with hospital-grade usability for medication administration and telehealth, highlighting the growing role of systems-level integrations from electronics OEMs.
-
Parity Medical (Bromborough, UK): UK-designed and assembled workstations illustrate how localized manufacturing and regulatory alignment can shorten procurement lead times for national health systems.
Recent industry moves underline these thematic dynamics: an FDA listing in mid-2024 for a new advanced cart; product upgrades that embed battery management systems; and renewed trade-show activity through early 2025. These events collectively reflect the industry’s emphasis on safety, uptime, and telehealth readiness.
Regulation, Reimbursement, and Certification — Operational Realities
-
Regulatory pathways: Integrating powered subsystems or diagnostic accessories typically triggers 510(k) obligations in the U.S. Vendors must factor regulatory timelines into time-to-market and product road maps.
-
Certification expectations: Buyers expect ISO 13485:2016 and ISO 9001:2015 quality systems as baseline credentials. Demonstrable adherence reduces purchase friction and supports rapid deployment within health systems’ supplier vetting processes.
-
Reimbursement context: As carts are generally managed under durable medical equipment frameworks without special CPT/DRG treatment, commercial strategies should rationalize pricing against workflow gains and TCO reductions rather than anticipated incremental reimbursement.
What the Full Report Contains (Practical, Executable Content)
PW Consulting’s full market study goes beyond descriptive analysis to provide operational tools and decision frameworks that procurement, product and corporate development teams can use immediately:
-
Market-sizing and scenario models calibrated to 2020–2025 history and iterated through 2026–2032 forecasts, enabling rapid sensitivity testing of adoption, price, and technology scenarios.
-
Go-to-market playbooks for vendors segmented by buyer persona (large integrated delivery networks, specialty clinics, ambulatory surgical centers) with procurement triggers and procurement committee levers mapped to product features.
-
Competitive benchmarking templates and capability matrices covering certification, battery tech, telehealth integration, warranty, and aftermarket service—designed to support RFP responses and M&A diligence.
-
Supply-chain and manufacturing risk heat maps, highlighting lead-time exposures, component concentration risks, and compliance bottlenecks that affect commercial continuity in 2026 and beyond.
-
Commercial models and TCO calculators to quantify buyer ROI for integrated battery systems, antimicrobial finishes, and managed service contracts—tools that help sellers justify price premiums in procurement negotiations.
-
Regulatory timelines and checklist templates for 510(k) submissions and CE/IEC conformity, enabling product teams to embed compliance milestones into development sprints and launch plans.
Note: this preview intentionally omits granular regional and application split data and other protected segmentation tables that are included in the full study. Those detailed breakdowns are critical for tactical decisions—such as exact market prioritization by country or specific product mix optimization—and are accessible in the full report.
How to Use These Insights in 2026
-
For vendors: Prioritize product investments that reduce buyer TCO and demonstrate compliance. Differentiate with service bundles and analytics that convert carts into managed assets rather than one-off capital purchases.
-
For health systems: Use the TCO framework to shift procurement criteria from lowest unit cost to lifecycle value, particularly when evaluating battery systems, warranties, and end-to-end telehealth enablement.
-
For investors and M&A teams: Target assets that fill capability gaps (battery management, telehealth integration, aftermarket services) and consider roll-up strategies to consolidate service-intensive niches where higher margins and stickiness reside.
Conclusion — From Momentum to Market Leadership
The medical computer cart market is no longer a peripheral accessories segment; it is an enabler of digital clinical workflows and virtual care. With an established growth trajectory and clear leader concentration, 2026 is the inflection point for turning product and commercial bets into sustained market presence. PW Consulting’s full study equips decision-makers with both the high-level market architecture and the practical tools—models, benchmarks, and templates—needed to translate the macro growth story into winning strategies. For teams that require the segmentation granularity, regional and application breakdowns, and downloadable decision-support tools, the full report provides the proprietary data and executable analyses that close the gap between insight and action.
To access the complete intelligence suite and the proprietary datasets that underpin our forecasts and playbooks, please consult the full Medical Computer Cart Market report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Medical Computer Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrical Steels Market to Reach USD 39.65 Billion by 2032 at 5.82% CAGR
By pmarketresearch, 2026-07-22
Electrical Steels Market 2026: Strategic Imperatives from PW Consulting’s Industry Study
As PW Consulting’s lead industry analyst, I present a succinct strategic preview of our comprehensive Electrical Steels Market study (base year 2025, forecast period 2026–2032). This briefing is purposefully structured as a “trailer”: it surfaces the analysis, signals the decision levers executives must act on in 2026, and deliberately withholds granular split tables and line-by-line segment forecasts to drive the next step — a download or briefing of the full report.
Electrical Steels Market
Executive snapshot
The global electrical steels market is entering a multi-year growth phase as electrification and grid modernization converge with industrial demand. On the macro scale, total industry revenues rose to USD 26.5 Billion in 2025 and, under our base forecast, expand at a compound annual growth rate (CAGR) of roughly 5.8% through 2032 to reach just under USD 40 Billion. That topline trajectory masks a complex interaction of technology substitution, regional supply chain reconfiguration, trade measures and input cost volatility — all active forces shaping 2026 strategic choices.
Electrical Steels Market
Why this matters for 2026 decisions
- Timing of investments: With sustained mid-single-digit CAGR, incremental capacity and product-line investments made in 2026 will capture demand across multiple cycles through the end of the decade.
- Policy and trade sensitivity: Regulatory shifts and trade actions are no longer peripheral risks; they are determinative of margin and access to markets. Firms must bake policy scenarios into capital allocation models.
- Product & customer segmentation: Demand drivers for core product families (low-loss grades for grid applications vs. hyper-thin grades for electric mobility) require different technology roadmaps and go-to-market approaches.
Core themes executives must prioritize
1. Supply-side reconfiguration and localization
2025–2026 saw renewed activity in plant investments and capacity realignment. Leading global producers are expanding or relocating capability closer to strategic end-markets to serve electrification and reduce import exposure. For decision-makers, the key question in 2026 is not whether to localize, but where and at what scale. Capital deployment needs to be selective: target hubs with stable policy regimes, predictable input access, and proximity to anchor customers such as EV OEMs and large utilities.
Electrical Steels Market
2. Product differentiation: loss, thickness and coating
Electrical steels are competing on finely tuned technical attributes: core loss for transformer steels, lamination thickness and magnetic permeability for motor steels, and surface/coating systems for manufacturability. Our analysis shows that premiumization of certain grades (driven by EV traction motor efficiency and smart-grid needs) will justify price premiums for producers who can sustain consistent quality and reliable supply. R&D and quality control budgets should be viewed as strategic enablers, not overhead.
3. Regulatory regimes reshape competitive advantage
Beginning in 2026 regulators have introduced market mechanisms and trade remedies that materially affect cost competitiveness for import-reliant buyers and exporters. Carbon-related mechanisms and updated benchmark rules for upstream processes change the calculus on whether raw material substitution, supplier requalification, or vertical integration is preferred. For corporate strategy this translates into dual actions: (a) align sourcing strategies to lower-carbon, compliant suppliers; and (b) stress-test pricing models under a range of carbon and tariff scenarios.
4. Input volatility and risk management
Ferrosilicon and other specialty alloy inputs experienced notable price swings in 2025, and volatility remains a realistic base case for 2026. Procurement strategies must therefore combine physical hedging, multi-sourcing, and supplier partnership models that include inventory smoothing and cost passthrough provisions. Firms that lock in supply and quality at competitive terms will outperform peers during cyclical input spikes.
5. Consolidation & cooperation pathways
Market concentration metrics indicate space for both scale players and specialized niche producers. For acquirers and investors, 2026 is a tactical window: consolidation can secure route-to-market advantages and technical capabilities, while targeted joint ventures allow faster access to regional demand without full greenfield exposure. Where regulatory constraints limit M&A, strategic alliances on coating technologies, thin-gauge processing, or recycling can yield similar benefits with lower political friction.
Competitive landscape — who matters and why
The competitive set comprises global integrated steelmakers and specialized electrical-steel producers. Several groups stand out as strategic benchmarks and potential partners or competitors in 2026 decisions:
- Global flat-rolled leaders that have pivoted to low-carbon processes and are scaling non-grain-oriented product lines to serve traction motor demand.
- Large integrated producers with advanced grain-oriented grades optimized for power transformers and renewable grid infrastructure.
- Regional specialists and engineering-driven firms that supply industrial motors and niche transformer applications, often leveraging tight customer relationships and service capabilities.
Across this set, companies that combine strong metallurgy know-how with supply-chain agility and regulatory alignment will be best positioned to capture the forecast growth.
Recent market signals to monitor in 2026
- Greenfield and retrofit investments in key producing regions that aim to shorten supply chains for high-value grades.
- Policy actions affecting import flows and carbon compliance obligations for steelmakers and buyers.
- Ongoing trade remedies and anti-dumping/anti-subsidy proceedings that can rapidly re-map supplier economics.
- Raw material price spikes and logistical interruptions that compress margins for unhedged producers.
Actionable recommendations for leadership teams (2026 planning cycle)
- Adopt scenario-based capital allocation: Build three capex scenarios (conservative, base, aggressive) tied to regulatory and trade outcomes. Prioritize modular plant designs and flexible lines that can shift between core grades.
- Reassess sourcing with carbon compliance as a core filter: Update approved vendor lists and include carbon-intensity KPIs. Negotiate long-term offtakes with paired decarbonization clauses.
- Product roadmap triage: Allocate R&D effort to two paths — performance optimization for EV traction motors and loss-minimization for utility transformers — while protecting intellectual property through joint development agreements where capital is constrained.
- Hedge input exposure smartly: Combine financial hedges for key alloy inputs with operational levers (safety stocks, upstream partnerships, alternative alloy trials) to dampen price shocks.
- Prepare tariff- and carbon-compliant pricing frameworks: Implement dynamic pricing models that can transparently pass through verified carbon or duty-related cost changes to customers.
- Refine M&A and partnership playbooks: Target bolt-on acquisitions that add technical capability or market access rather than scale alone. Use JV structures in politically sensitive markets to limit regulatory pushback.
- Invest in market intelligence and rapid response: Set up a dedicated monitoring cell to track material regulatory changes, trade investigations and competitor investments in real time.
How PW Consulting’s full report supports 2026 execution
Our complete Electrical Steels Market study goes beyond high-level themes to deliver practical decision tools for 2026 and beyond, including:
- Scenario-modeled demand forecasts across the forecast horizon (2026–2032) with sensitivity to regulatory and trade outcomes.
- Strategic capex calculators for greenfield vs. retrofit investments that incorporate carbon-compliance cost assumptions and break-even timelines.
- Supplier and region risk heatmaps tied to raw material exposure, logistical complexity and policy risk indices.
- Competitor profiles and playbooks summarizing technological strengths, likely strategic moves, and potential partnership fit for each major producer.
- Commercial tools: pricing templates that integrate pass-through mechanics for carbon and duty layers, and customer segmentation guides for OEMs and utilities.
Concluding perspective
The electrical steels market in 2026 is not just growing — it is re-sorting. Growth is meaningful at the macro level, but the enduring value will accrue to companies that converge capability in three dimensions: metallurgical excellence, supply-chain resilience, and regulatory foresight. Executives who embed flexible investment frameworks, carbon-aware sourcing, and disciplined product prioritization into their 2026 plans will convert mid-single-digit CAGR into above-market returns.
Next steps — where to get the full intelligence
This preview intentionally omits the granular regional, product and application splits that underlie our revenue and margin forecasts. Those line-level datasets, supported by proprietary supplier mappings and capex models, are available in the full PW Consulting Electrical Steels Market report and accompanying analyst briefings. To schedule a tailored executive briefing or to access the detailed tables and scenario models that will inform precise 2026 capital and commercial plays, contact PW Consulting through our website or request the report download.
Our team stands ready to translate the study’s findings into a bespoke action plan aligned to your firm’s risk tolerance, market exposure and growth ambitions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Electrical Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blue Laser Diodes Market to Hit USD 326M by 2032 at 8.15% CAGR
By pmarketresearch, 2026-07-22
Blue Laser Diodes Market: Strategic Imperatives for 2026 Decision-Makers
The blue laser diodes market is entering a phase of sustained, technology-driven expansion. PW Consulting’s newest study — with a base year of 2025, a historical window covering 2020–2025, and a forecast horizon spanning 2026–2032 — shows the market expanding from USD 120.5 million in 2020 to USD 188.5 million in 2025, with a projected rise to USD 326.0 million by 2032. Our model indicates a compound annual growth rate (CAGR) of 8.15% across the 2026–2032 forecast period. For executives planning near‑term investments in 2026, this trajectory creates both opportunity and urgency: market momentum is real, but value will accrue to actors who align technology, supply chain and regulatory strategy in the next 12–24 months.
Blue Laser Diodes Market
Why this study matters for decisions in 2026
-
Timing of investment: 2026 is a hinge year where incremental improvements in diode efficiency and supply-chain resilience translate directly into competitive advantage.
Blue Laser Diodes Market -
Procurement and sourcing: volatile upstream markets and export controls make supplier diversification and strategic contracting (long-term, conditional) non-negotiable.
Blue Laser Diodes Market -
Product roadmaps and go‑to‑market: improvements in wall‑plug efficiency and power density reshape application fit across industrial, medical and consumer segments.
-
M&A and partnership windows: market concentration metrics show meaningful aggregation among leading suppliers, creating differentiated M&A and alliance opportunities.
Key market dynamics shaping 2026 strategy
-
Solid multi-year growth: the market’s leap between 2020 and the 2025 base year — and our projection to 2032 — validates both demand-side expansion and ongoing technology adoption across applications.
-
Technology acceleration: suppliers are pushing higher optical power and improved wall‑plug efficiencies. Recent product introductions exemplify a competitive push to reduce system-level power and thermal costs, which accelerates adoption in energy-sensitive industrial and medical deployments.
-
Supply‑side concentration: the market exhibits a moderate degree of concentration among top suppliers. The CR3 and CR5 metrics in our study highlight that leading players already control a majority of market revenue, which influences pricing dynamics, qualification timelines and access to advanced device roadmaps.
-
Raw material exposure: gallium remains a critical input. Market signals in 2026 show upward price pressure and regional price divergence driven by export licensing regimes and capacity constraints. Companies that model gallium exposure explicitly and implement hedging or direct-sourcing strategies will materially reduce cost and delivery risk.
-
Regulatory and defense demand tailwinds: export controls and strategic procurement programs (including significant defense spending on photonics) are reconfiguring demand pathways and supplier selection criteria for certain applications.
Competitive landscape — strategic implications
The competitive field is populated by incumbents with differentiated capabilities in device design, manufacturing scale and go-to-market focus. PW Consulting’s assessment of core players highlights the strategic postures to watch:
-
Nichia Corporation — deep expertise in high-power blue laser diodes and a product portfolio oriented to industrial and projector applications. Strengths: R&D cadence and production maturity. Implication: new entrants and OEMs should assume long qualification cycles and plan multi-source strategies when Nichia is a preferred supplier.
-
ams‑OSRAM AG — pushing high-efficiency devices (notably recent releases showing strong wall‑plug efficiency metrics). Strengths: integrated optoelectronics platform and system-level partnerships. Implication: their efficiency-led products lower system cost and will set competitive performance baselines; suppliers and customers must respond on performance or cost.
-
Sharp Fukuyama Laser — focused on consumer and automotive segments with manufacturing strengths tailored to high-volume, cost-sensitive applications. Implication: competitive pressure on price and qualification timelines in consumer-facing routes.
-
Sony Semiconductor Solutions — delivering blue‑violet diodes for optical storage and automotive systems with strong systems integration capabilities. Implication: strategic wins in automotive can cascade into cross-supply opportunities with existing Sony platform customers.
-
KYOCERA SLD Laser — positions around GaN-based high-performance diodes for lighting and fiber-coupled uses. Implication: differentiation in fiber and illumination applications where coupling efficiency and ruggedness matter.
-
BluGlass Limited — smaller, innovation-led supplier with GaN-on-diamond and niche-market traction in defense, quantum and biotech. Implication: attractive partner for co-development and for buyers seeking specialized device features rather than commodity supply.
Notably, ams‑OSRAM’s March 2025 product introduction (a high‑power blue laser diode with double-digit improvements in wall‑plug efficiency) exemplifies the technical leaps influencing procurement specifications and thermal management budgets in customer designs. Firms that fail to monitor such product moves risk designing to yesterday’s performance envelope.
What the PW Consulting report delivers (practical contents)
-
Action‑oriented executive summary with board-level implications for 2026 capital planning.
-
Top‑down market sizing and bottom‑up demand models (base year 2025; historical 2020–2025; forecast 2026–2032), denominated in USD (Million).
-
Supply‑chain heatmaps identifying single‑point‑of‑failure nodes (including upstream gallium exposure and licensing risk).
-
Competitive intelligence dossiers on major suppliers, including product roadmaps, capacity footprints and likely moves over 12–36 months.
-
Scenario analyses and sensitivity testing that quantify outcomes under supply shocks, regulatory tightening, or faster/slower efficiency improvements.
-
Commercial playbooks: procurement contracting templates, supplier scorecards, go‑to‑market segmentation heuristics and pricing strategy frameworks.
-
M&A screening and valuation guidance for roll-up or capability-acquisition plays, and an investor checklist for de‑risking diligence.
Note: this preview intentionally omits proprietary, granular segmentation tables and client‑grade breakouts. Those detailed figures and interpolated models are available in the full PW Consulting report.
Immediate strategic actions for 2026
-
Operationalize gallium risk management: map exposure, pursue alternative suppliers, and negotiate indexed long‑term contracts or strategic inventory buffers where project economics justify it.
-
Re‑prioritize R&D spend toward efficiency and thermal boundary improvements; even small wall‑plug efficiency gains can change system BOM and lifetime costs.
-
Qualify at least two suppliers per critical product family; accelerate qualification timelines via joint test programs and shared engineering resources.
-
Pursue selective partnerships or minority investments in specialist innovators to capture niche performance advantages (e.g., fiber‑coupled or high‑power modules) without heavy capex.
-
Embed regulatory monitoring into commercial forecasting — defense procurement and export control shocks materially change accessible addressable markets.
-
Use scenario triggers: (a) gallium price spikes beyond defined thresholds; (b) confirmed export licensing escalation; (c) competitor launches that materially improve WPE — to prompt contingency activations such as hedging, qualification acceleration or pricing adjustments.
How to use this intelligence in boardroom deliberations
-
Translate TAM and forecast outputs into three prioritized capital asks (capacity, R&D, inventory) with NPV and payback scenarios under conservative and optimistic adoption paths.
-
Construct a supplier stress test for Q3–Q4 2026 procurement cycles: quantify delivery risk, price exposure and qualification lead times.
-
Align product roadmaps with anticipated performance baselines: decide whether to compete on cost, performance, or platform integration for each target application.
Closing — next step
For 2026, executives need more than high‑level conviction: they need actionable, quantified pathways to reduce risk and capture upside. PW Consulting’s Blue Laser Diodes Market study provides the models, supplier intelligence and scenario playbooks required to do just that. This article is a strategic preview designed to surface the most consequential dynamics; detailed segment breakouts, unit‑level forecasts, supplier capacity maps and downloadable models are available in the full report. Visit PW Consulting’s market research portal to access the complete data set, spreadsheets and decision templates tailored for investors, OEMs and procurement leaders.
For detailed analysis of this topic, please visit the official page: Blue Laser Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solar Encapsulation Market to Reach USD 9.95 Billion by 2032 at 7.83% CAGR
By pmarketresearch, 2026-07-22
Solar Encapsulation Materials Market: Strategic Imperatives for 2026 Decision‑Makers
Market snapshot — why 2026 is a strategic inflection point
The solar encapsulation materials market is in clear expansion mode. Our baseline assessment (base year 2025) values the global market at approximately USD 5.87 Billion and projects steady expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 7.83%, reaching an expected market size near USD 9.95 Billion by 2032. These headline figures understate important structural shifts: technology-driven demand for higher-performance films, rising qualification and warranty requirements for next‑generation modules, and an increasingly strategic approach to supply‑chain localization are re-shaping supplier economics and buyer priorities.
Solar Encapsulation Materials Market
What this report delivers — an action-oriented playbook (high level)
PW Consulting’s Solar Encapsulation Materials Market study is designed as an operational intelligence product for executives making capex, procurement, product development, and M&A decisions in 2026. The study blends a granular data backbone with strategic narratives and executable frameworks, including:
Solar Encapsulation Materials Market
- Market sizing and seven‑year forecasts by material class and module architecture (historical 2020–2025 baseline + 2026–2032 outlook).
- Technology deep dives covering polymer chemistries, co‑extrusion architectures, and key performance metrics (moisture ingress, PID resistance, UV stability, and gel content expectations for commercial qualification).
- Supplier landscape and scorecards evaluating capacity, IP position, quality systems, and route‑to‑market competence.
- Procurement playbooks — scenario‑based sourcing strategies, dual‑sourcing templates, and cost‑to‑serve models suited to module manufacturer profiles.
- Risk and regulatory matrix — warranty exposure analysis, regional trade and localization pressures, and regulatory tests that materially affect LCOE and bankability.
- Opportunity maps for technology partnerships, licensing, and targeted capacity expansion projects that balance speed, cost, and qualification risk.
Market dynamics reshaping supplier and buyer strategies
Several overlapping dynamics are accelerating demand and reframing margins across the value chain:
Solar Encapsulation Materials Market
- Module architecture transition: The move to bifacial, TOPCon and other high‑efficiency cell technologies is driving buyers to specify encapsulants with improved PID resistance and enhanced moisture barriers. These functional requirements are increasingly codified in module qualification protocols and in warranty commitments that module manufacturers must meet.
- Material innovation and product differentiation: Co‑extruded films, POE variants optimized for TOPCon, UV‑stabilized formulations and perovskite‑compatible encapsulants are becoming commercial imperatives for players targeting premium module segments. Incremental efficiency and reliability gains can translate to meaningful price premiums for premium films — buyers must balance the cost‑benefit across module BOM (bill of materials) and lifetime energy yield.
- Supply‑chain localization and geopolitical considerations: Strategic moves to establish production footholds closer to major module assembly centers — including North America and Southeast Asia — are reducing qualification timelines and mitigating import exposure. Domestic facility expansions and near‑market capacity are increasingly factored into procurement scorecards.
- Consolidation and market concentration: The market structure exhibits significant concentration, with leading suppliers commanding a meaningful share of global supply. This concentration creates both risk (single‑source dependencies) and opportunity (partnerships, co‑development, and premium pricing) for module makers and downstream buyers.
- Cost‑performance tradeoffs and warranty economics: Encapsulant selection is no longer a component decision in isolation. It feeds into warranty risk, bankability, and LCOE calculations. Higher upfront material cost can be justified when the incremental performance reduces degradation and warranty reserves over a 25‑year contractual horizon.
Competitive lens — who matters and how they are positioning
The competitive map is a mix of global chemical majors, specialized polymer houses, and regionally focused film producers. Our assessment highlights a set of companies that are shaping product roadmaps, capacity footprints, and qualification dynamics:
- Hangzhou First PV Material Co., Ltd. — positioned as a global leader in EVA and POE films, with commercialized co‑extruded solutions tailored to high‑efficiency module formats.
- Jiangsu Sveck New Material Co., Ltd. and Zhejiang Sinopont Technology Co., Ltd. — regional champions focusing on co‑extrusion and TOPCon‑compatible POE developments to capture growth in fast‑expanding module assembly hubs.
- Shanghai HIUV New Materials and Changzhou Betterial Film Technologies — technology‑centric players prioritizing UV resistance, long‑term stabilization chemistries, and solutions for tandem/perovskite architectures.
- Major chemical conglomerates (3M, Dow, DuPont, Mitsui Chemicals, Eastman) — offer breadth of material platforms and the global qualification reach that multinational module makers require.
- Regional suppliers in India and other emerging markets (RenewSys, Alishan Green Energy) — rapidly scaling capacity and introducing specialized fast‑cure and UV‑functional products to serve local OEMs with shortened supply chains.
These supplier trajectories are reflected in recent commercial activity: facility expansions in North America, capacity scale‑ups in South and Southeast Asia, and commercial launches of high‑barrier co‑extruded films and perovskite encapsulation solutions. Such moves accelerate qualification cycles for buyers but also create windows for strategic sourcing and co‑development.
Strategic implications for 2026 decisions — what executives must act on now
For corporate leaders — procurement heads, product R&D chiefs, and strategy teams — the window to position for 2026 outcomes is narrow. The following implications should frame boardroom deliberations:
- Revisit encapsulant selection as a system design choice. Procurement checklists must expand beyond unit price and delivery to include demonstrated PID resistance, moisture ingress performance, and third‑party qualification track records aligned with 25‑year warranty regimes.
- Prioritize dual‑track sourcing for premium segments. Maintain relationships with global majors for consistency and qualification leverage, while piloting regional specialized suppliers to reduce lead times and improve cost flexibility.
- Accelerate technical validation cycles. Invest in accelerated aging labs or co‑funded qualification programs with suppliers to compress the time from material selection to module certification.
- Embed market scenarios into supply‑chain capital decisions. Use scenario modeling — reflecting adoption rates of bifacial and TOPCon modules — to size internal inventory buffers, negotiate long‑term take‑or‑pay terms, and plan capex for back‑integrated film lamination capacity where justified.
- Be alert to premium pricing dynamics. Certain high‑performance films command price premiums tied to measurable module efficiency and warranty outcomes; quantify those tradeoffs in LCOE and financing models rather than treating them as line‑item costs.
- Evaluate M&A and strategic alliance opportunities. For firms seeking rapid capability buildup, acquiring or partnering with specialized film producers can shortcut multi‑year R&D and qualification timelines.
Practical next steps — a 90‑day playbook for 2026 planning
For teams tasked with implementing the strategic pivots above, we recommend a focused 90‑day agenda:
- Week 1–4: Conduct a supplier risk audit, mapping single‑source exposure, qualification timelines, and geopolitical risk vectors.
- Week 5–8: Run a technical gap analysis comparing existing module warranties and degradation assumptions against supplier performance data and new film chemistries.
- Week 9–12: Launch one pilot co‑development program (e.g., POE/TOPCon or perovskite encapsulation) with a shortlist of suppliers and establish success metrics tied to qualification milestones and cost targets.
Why PW Consulting’s study matters for 2026
This report is purpose‑built to inform decisions that materially affect capital allocation, product roadmaps, and supply‑chain risk in 2026. We combine transparent, auditable market sizing (2020–2025 historical series and 2026–2032 forecast), supplier benchmarking, and hands‑on playbooks that translate analysis into executable initiatives. The goal is not simply to describe market trends but to enable governance bodies and operating teams to act with speed and confidence.
Final note — what we intentionally withhold (and why)
This overview demonstrates the analysis depth and practical orientation of our full study while preserving the proprietary segmentation tables, supplier scorecards, and granular regional/application splits that deliver the operational value for which PW Consulting is engaged. If your 2026 strategy requires detailed material‑by‑application demand curves, supplier capacity maps, or price‑elasticity grids, those datasets — along with scenario models and downloadable financial templates — are available in the complete report and accompanying client portal.
Call to action
For executive briefings, customised supplier benchmarking, or access to the full dataset and scenario models, contact PW Consulting to schedule a tailored walkthrough. The decisions you make in 2026 about encapsulant strategy will reverberate across product reliability, warranty outcomes, and cost of energy for the next decade — make them with calibrated insight.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Continuously Variable Transmissions (CVT) Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
The PW Consulting CVT Market study provides a concise, decision-focused view of an evolving powertrain component market that matters far beyond transmission lines. Measured on a USD Billion basis, the market grew from roughly USD 15.6 Billion in 2020 to USD 18.65 Billion in our base year 2025, and we forecast continued expansion through 2032 at a compound annual growth rate (CAGR) of approximately 4.5% to reach about USD 25.65 Billion. These headline figures mask important asymmetries across technologies, vehicle segments, and supply chains — asymmetries that will determine winners and losers in 2026 and beyond.
Continuously Variable Transmissions (CVT) Market
Why this study matters for 2026 strategic decisions
-
Investment prioritization: A steady mid-single-digit CAGR combined with pockets of differentiated technology demand means capital allocation decisions (R&D, capacity expansion, tooling) must be selective. The report identifies where incremental investment unlocks outsized returns versus where commoditization risks margin erosion.
Continuously Variable Transmissions (CVT) Market -
Product & technology roadmaps: CVT variants (belt, chain, toroidal and hydrostatic approaches, among others) are at different maturity and cost points relative to hybrid and electrified powertrains. The study maps techno-economic trade-offs so product teams can align next-generation CVT programs with OEM electrification timetables.
Continuously Variable Transmissions (CVT) Market -
Supply-chain resilience: Specialty inputs (for example, engineered steel push-belts and precision pulleys) create concentrated supplier risk. Our analysis translates that vulnerability into contract, inventory, and dual-sourcing strategies tailored for 2026 procurement cycles.
-
Regulatory positioning: Emissions and fuel-economy standards remain a primary demand driver for CVT adoption in ICE and hybrid applications. We synthesize recent regulatory materials and cost-estimation approaches used by agencies to help compliance and policy teams anticipate regulatory impacts on CVT product mixes and cost modeling.
What the PW Consulting CVT Market Study contains
-
Top-line market sizing & forecast (2020–2032): Full historical tracking and granular forecasts that reconcile macro demand drivers with vehicle production trajectories. The study includes sensitivity scenarios to stress-test forecasts against faster electrification or accelerated policy tightening.
-
Technology segmentation & maturity mapping: Comparative assessments of belt-driven, chain-driven, toroidal, hydrostatic and other CVT architectures — including lifecycle cost curves, performance envelopes, and compatibility with hybrid and mild-hybrid architectures.
-
Competitive benchmarking: Detailed profiles of incumbent and challenger manufacturers, product portfolios, manufacturing footprints, and capability gaps. (Note: the preview omits granular share-by-segment tables — these are included in the full report.)
-
Supply-chain and raw material analysis: Mapping of critical upstream suppliers, single-source exposures, lead times, and cost pass-through risks for 2026 contracting negotiations.
-
Regulatory impact and cost modeling: Reconciliation of agency cost-estimation methods with industry learning curves, plus quantification of how fuel-economy credits and compliance pathways alter OEM transmission sourcing economics.
-
Commercial playbooks: Go-to-market strategies for suppliers and OEMs — pricing levers, channel strategies, and recommended partnership models to accelerate adoption or defend share.
-
Transaction and M&A screening kit: A prioritized list of capability gaps, attractive target profiles, and valuation sensitivities for 2026 M&A planning (full target identities and valuations are in the complete deliverable).
Competitive landscape — what matters
The CVT supplier ecosystem remains concentrated, with the largest players collectively holding a significant portion of global supply. This concentration translates into defendable scale advantages on product development, manufacturing efficiency, and OEM access — but it also creates opportunity windows for focused challengers that can offer differentiated value (cost, integration with electrified architectures, or regional proximity).
-
JATCO Ltd (Yokohama, Japan) — Recognized as a global leader in CVT technology. JATCO’s broad portfolio and continuous improvements in CVT designs provide a competitive baseline for many front-wheel drive platforms. Their scale permits ongoing investment in variants that improve NVH and fuel economy for mass-market applications. More: https://www.jatco.co.jp/english/
-
Aisin Seiki Co., Ltd. (Kariya, Japan) — Focuses on advanced CVT configurations, including models with launch gear and other innovations that target both fuel efficiency and transient response. Aisin’s systems are positioned to serve OEMs balancing drivability with regulatory demand. More: https://www.aisin.com/en/
-
Nissan Motor Co., Ltd. (Yokohama, Japan) — Not only an OEM user but also an influential developer and promoter of CVT technology via the Xtronic line. Nissan’s recent 2025 product communications reiterated two decades of refinement and reliability improvements in Xtronic units — messaging intended to re-anchor consumer and fleet perceptions as new models launch. More: https://www.nissanusa.com/
-
Honda Motor Co., Ltd. (Tokyo, Japan) — Implements CVT broadly across models for fuel-efficiency gains and seamless drivability; its in-house engineering capability creates a strong pull-through for suppliers that align with Honda’s integration requirements. More: https://automobiles.honda.com/
-
Subaru Corporation (Tokyo, Japan) — Uses and supplies Lineartronic CVTs in many models to balance efficiency and off-highway drivability, offering niche advantages where torque-handling and driver feel are prioritized. More: https://www.subaru.com/
Dynamics, headwinds and regulatory noise
-
Regulatory cost accounting and learning curves: Recent technical support documents from regulatory agencies have formalized methodologies to estimate direct manufacturing costs and to apply learning curve factors to CVT production economics. These approaches affect how OEMs and regulators evaluate the cost-effectiveness of CVTs in compliance demonstrations — and they should be incorporated into 2026 capital and pricing models.
-
Historical penetration and projection inconsistencies: Public agency estimates from previous market snapshots illustrate how historical CVT penetration can diverge from model projections under different compliance scenarios. Clients should treat single-source public penetration estimates as inputs to scenario analysis rather than deterministic outcomes.
-
Raw-material and supplier fragility: The CVT value chain depends on a small number of specialized suppliers for critical components (notably steel push-belts and precision pulleys). Disruptions in these nodes produce outsized production delays and cost volatility — a primary operational risk for 2026 sourcing strategies.
-
Fuel economy and electrification interaction: CVTs remain an effective lever for incremental fuel-economy improvement in internal-combustion and mild-hybrid powertrains, which helps OEMs meet near-term emissions targets. However, medium-to-long-term electrification trajectories change the addressable market and product requirements for CVT providers. Our scenarios explicitly model alternative EV adoption curves to show breakeven timings for continued CVT investment.
Using this study in your 2026 playbook
-
Procurement & supplier strategy: Use the report’s supplier-risk heat map and cost-driver analysis to prioritize dual-sourcing, long-lead inventory, and contract clauses for raw-material pass-throughs ahead of 2026 negotiations.
-
R&D and product portfolio decisions: Align CVT R&D investments with vehicle electrification roadmaps and with segments where CVT remains the most efficient solution for the next 5–7 years. The study identifies technical thresholds where investment yields diminishing returns.
-
M&A and partnership screening: Apply the included transaction checklist to evaluate bolt-on acquisitions that fill capability gaps (e.g., coating technologies for belts, advanced clutch integration for hybrid systems) or provide regional manufacturing leverage.
-
Regulatory engagement: Leverage the report’s reconciliation of agency cost estimation methods to prepare evidence-based submissions or to anticipate regulatory shifts that could alter technology economics in 2026 compliance cycles.
What we deliberately withhold in this overview
This preview is intentionally selective. To preserve the report’s tactical value for commercial and procurement decision-making, we have omitted detailed subsegment tables (regional and application-level percentage splits), granular vendor market shares by sub-technology, and the full list of M&A targets and valuation sensitivities. These elements are available in the full PW Consulting CVT Market report and the accompanying data workbook, which are designed to be executable tools for your 2026 planning cycle.
Next steps
For executive teams, the critical near-term actions are clear: reconcile your 2026 capital and sourcing plans with the scenarios that reflect both continued CVT relevance in specific vehicle niches and the accelerating competition from electrified alternatives; re-assess supplier dependency for critical components; and use the report’s transaction filters to identify strategic partners or targets. PW Consulting stands ready to translate the report’s findings into a tailored implementation roadmap — from procurement playbooks to bespoke M&A diligence.
To access the full report, complete datasets, and the interactive forecasting model — including the subsegment detail necessary to operationalize these recommendations — please contact your PW Consulting representative or visit our report page. The full deliverable equips your team with the granular inputs required for confident capital, product, and sourcing decisions in 2026.
For detailed analysis of this topic, please visit the official page: Continuously Variable Transmissions (CVT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: WiFi Thermostats Market to Reach USD 17.35M by 2032 at 21.07% CAGR
By pmarketresearch, 2026-07-22
WiFi Thermostats Market — 2026 Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused executive preview of our WiFi Thermostats Market research — a tactical briefing designed to shape corporate decisions in 2026. This preview demonstrates the analytical depth and strategic framing contained in the full study while intentionally withholding the detailed segment tables and proprietary matrices that are accessible in the full report. Consider this a high-fidelity trailer: enough insight to inform priorities and immediate moves, but not the full playbook reserved for subscribers and clients.
WiFi Thermostats Market
High-level market trajectory you cannot ignore
The WiFi thermostats market has moved from a niche connected device into a mainstream energy-management platform. Our modeled time series shows a clear inflection: the market advanced from roughly USD 1.75 Million (revenue, Million USD) in 2020 to USD 4.55 Million in the 2025 base year, and is projected to expand at a compound annual growth rate of about 21.07% through our forecast horizon (2026–2032). By 2026 the market crosses an important adoption threshold and is projected to reach roughly USD 5.6 Million, ultimately approaching an estimated USD 17.35 Million by 2032 under the central scenario (all figures in USD Million).
WiFi Thermostats Market
Those dynamics tell a simple strategic truth for 2026: the addressable market is large enough and growing fast enough that incumbents and new entrants alike must prioritize product differentiation, channel optimization, and regulatory capture if they hope to defend or grow share.
WiFi Thermostats Market
What the full report delivers (practical, decision-ready content)
- Actionable market sizing and scenarios: Transparent modeling from 2020–2025 (historical) and a 2026–2032 forecast window with base-year calibration (2025). We deliver a central case plus conservative and upside scenarios to stress-test investment decisions.
- Growth-driver heatmaps: Detailed identification and quantification of demand levers — including smart-home interoperability standards, utility rebate programs, certification regimes, and consumer energy-savings economics — with sensitivity analysis for each lever.
- Regulatory and incentive map: A jurisdiction-by-jurisdiction guide to where certification and rebate rules materially change purchase economics and installation flows. It includes compliance checklists aligned to the major programs and regulations active through 2026.
- Go-to-market playbooks: Channel segmentation, pricing tactics, and distribution models for OEMs, retailers, utilities, and installers — plus scripts for utility partnership negotiations and retailer planograms optimized for 2026 promotions.
- Technology & product roadmap benchmarking: Comparative analysis of feature sets (connectivity standards, sensors, AI/learning, IAQ, video integration), integration risks, upgrade paths, and likely ASP trajectories under different hardware/software bundling strategies.
- Competitive intelligence & M&A scouting: Profiles of leading and fast-following vendors, market concentration metrics, and a short-list of acquisition/partnership targets ranked by strategic fit and integration complexity.
- Operational playbook for utilities and energy programs: Implementation guidance for rebate and enrollment programs that maximizes participation while reducing installation friction and fraud risk.
Competitive landscape: strategic implications (selected players)
The market’s competitive texture is best described as moderately concentrated. Our concentration metrics place the top three suppliers at roughly 45% CR3 and the top five at about 52% CR5 — enough heft for incumbents to set expectations, yet leaving meaningful room for challengers and niche specialists.
- Resideo Technologies, Inc. (Honeywell Home portfolio) — Resideo remains a primary incumbent with strong retail and channel reach. Recent product moves — including Matter-enabled models and the 2025/2025 launches of the X2S and the premium X8S (large touchscreen, integrated video/live doorbell stream, IAQ monitoring, and HVAC diagnostics) — reinforce a dual strategy: defend the mainstream by iterating connectivity and energy features while expanding into premium, integrated home hubs. For competitors, Resideo’s strategy raises the bar for cross-device integration and post-sale service expectations. For strategic buyers, Resideo’s activity signals where to expect consolidation pressure (software/hardware integration assets are high-value targets).
- ecobee Inc. — ecobee is differentiated by sensor technologies (including radar presence sensing) and air-quality monitoring across its Essential, Premium, and Enhanced lines. Their focus on consumer-facing measurement and direct-to-consumer channel optimization positions them as the prime threat in the premium/comfort-first segment. Strategic implication: companies optimizing for energy-savings partnerships must match or exceed ecobee’s environmental sensing to capture utility and health-conscious segments.
- Google (Nest) — Nest continues to leverage AI learning and broad platform integration (voice, cloud, matter). Google’s advantage lies in platform-level synergies and data-driven services. For incumbents and service providers, the defensive response must be either deeper platform partnerships or a clear migration strategy that preserves customer relationships independent of the large cloud ecosystems.
- Emerson Electric Co. (Sensi) — Emerson’s Sensi line is positioned toward reliable OEM-grade integrations and installer-friendly propositions. Emerson’s legacy in HVAC control positions it well for channel partnerships with HVAC contractors and commercial installers; corporate strategy here should focus on tightening installer workflows and pursuing managed-service contracts with commercial and multi-family customers.
Key regulatory and incentive drivers you need on your radar
- Certification regimes setting technical compliance floors and enabling market access: certain jurisdictions require occupant-controlled smart thermostats to meet specific certification standards to qualify for codes or rebates.
- Utility rebate programs materially change purchase economics: a number of incentive programs through 2026 offer cash incentives for ENERGY STAR-certified smart thermostats and tie eligibility to installation and registration workflows.
- These regulatory and rebate mechanisms are a double-edged sword: they accelerate adoption for compliant products but increase the compliance burden and create lock-in for vendors who can scale lifecycle support (registration, firmware updates, proof-of-installation).
Strategically, pre-certifying models for key rebate programs and designing installation-to-registration paths that minimize friction can unlock incremental demand without proportionate marketing spend.
How executives should use this study in 2026
- Product roadmap prioritization: Use the feature-valuation and willingness-to-pay matrices to sequence hardware upgrades vs. software services. Invest early in interoperability (Matter), IAQ sensing, and installer-oriented UX if targeting utility programs or enterprise channels.
- Channel & pricing decisions: Calibrate pricing bands against rebate capture and expected ASP evolution. Use the go-to-market playbooks to reallocate marketing spend toward program-enabled channels (utilities, retailers with rebate integrations, and pro-install networks).
- Regulatory capture & compliance budgeting: Treat certification and rebate-enabling investments as go-to-market capital. The report provides a timeline and jurisdictional priority list to focus compliance resources in 2026.
- M&A and partnership screening: Apply our fast-scan scoring to shortlist targets offering sensor IP, installation/registration platforms, or utility program management capabilities to accelerate market access.
- Utility and procurement negotiations: Use the operational playbook to design rebate structures that reduce fraud, increase beneficiary stickiness, and create data-sharing agreements that are privacy-compliant and monetizable.
Methodology, scope, and what’s intentionally withheld in this preview
The study synthesizes primary interviews with OEMs, channel partners, utilities, and installers; a product-level technology survey; and a bottoms-up revenue model calibrated to shipment proxies and average selling price trajectories. Historical coverage runs from 2020–2025 with 2025 as the base year and an explicit forecast window from 2026–2032. All revenue figures in this preview are stated in USD (revenue unit: Million). The central forecast assumes a 21.07% CAGR across the forecast window, with scenario variants provided in the full report.
To preserve the strategic value proposition of the full dataset, this preview does not disclose the detailed regional, price-tier, or end-use split tables, nor the proprietary market-share roll-ups that drive segment-level NPV models. The full report includes those tables, granular model access, workbook exports, and an annex of primary-source interviews and vendor product catalogs.
Final recommendation — immediate 90-day agenda for leadership
- Secure product certifications for the top three rebate programs in your priority market list and document the implementation timeline in Q2 2026.
- Run a four-week rapid audit of installer and self-install UX to eliminate registration friction that blocks rebate capture.
- Prioritize one tactical partnership with a utility or national retailer to test an incentivized bundle that includes installation and registration services.
- Initiate a focused M&A scan for sensor or registration-platform targets that can be integrated within 6–12 months to accelerate rebate-driven sales.
For teams preparing budgets, sales targets, or M&A pipelines in 2026, the choices you make in the next 90–180 days — around certification, channel integration, and product-defining features — will determine whether you capitalize on a market expanding from a few million in 2025 to a multi-fold larger market by 2032.
Access to the full PW Consulting WiFi Thermostats Market study will provide the segment-level datasets, tactical playbooks, and the vendor scorecards needed to act with precision. Visit our report page to download the complete report and the model workbook, or contact our advisory team for a one-on-one strategic briefing that maps the findings to your organization’s objectives.
For detailed analysis of this topic, please visit the official page: WiFi Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Ambient Lighting to Top USD 5,887 Million by 2032 at 10.5% CAGR
By pmarketresearch, 2026-07-22
Automotive Ambient Lighting Market — Strategic Primer for 2026 Decision-Makers
As vehicle interiors evolve from purely functional cabins into curated, emotionally resonant spaces, ambient lighting has moved from a niche comfort option to a strategic design and systems integration lever. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) synthesizes quantitative forecasting with hands-on commercial guidance to equip executives, product heads, and procurement leaders for the critical decisions they will make in 2026. Our modelling shows a robust industry trajectory — a compound annual growth rate (CAGR) of roughly 10.5% over the forecast window — reflective of accelerated OEM adoption, higher content-per-vehicle, and the increasing role of lighting in brand differentiation and human-machine interaction.
Automotive Ambient Lighting Market
Why this study matters to 2026 strategy
Two strategic forces converge in 2026. First, the buyer expectation: consumers now treat cabin ambiance as part of vehicle identity, not an optional luxury. Second, platform complexity: the move to zonal electrical architectures, higher-bandwidth domain controllers, and electrified powertrains creates both opportunity and integration risk. For leadership teams planning product roadmaps, supplier strategies, or M&A activity next year, our report translates market momentum into executable choices — showing where to allocate R&D spend, how to negotiate supplier contracts under downward ASP pressure, and what partner archetypes to prioritize for rapid, cost-effective integration.
Automotive Ambient Lighting Market
Market trajectory — the big-picture numbers you need
PW Consulting’s top-line sizing places the market at approximately USD 2,925 Million in 2025 and projects expansion to roughly USD 5,887 Million by 2032 under a baseline scenario. In absolute terms, the market is expected to breach the USD 3.3 Billion mark as early as 2026 as OEMs increase ambient lighting content density and electrified vehicle platforms bootstrap new feature sets. These headline figures are conservatively constructed from five-year historical performance (2020–2025) and a scenario framework that tests demand elasticity, component ASP erosion, and supplier concentration effects.
Automotive Ambient Lighting Market
Importantly for corporate planning, the market’s structure is neither a pure commodity race nor a winner-takes-all intellectual property contest. Our concentration analysis indicates that the top three suppliers command a strong share of OEM business, while the broader top five capture a clear majority of high-value contracts — a dynamic that favors established lighting systems integrators but still leaves whitespace for specialist component suppliers and software-enabled entrants.
What the report contains — practical, action-oriented deliverables
- Proven sizing and forecasting methodology: transparent assumptions, sensitivity runs, and scenario outputs tailored to 2026 procurement cycles.
- Commercial playbook: negotiation matrices for component sourcing (including bundled optics, LED modules, and control electronics), price erosion mitigation tactics, and supplier scorecards for rapid qualification.
- Product and systems roadmaps: technology adoption timelines for multi-zone RGB controls, PWM/DMX interface choices, and integration checkpoints with domain controllers.
- Regulatory and compliance tracker: implications of recent safety regulations, homologation timelines, and recommended compliance workflows for global programs.
- Supply-chain resilience analysis: concentration risk mapping of LED upstream suppliers, tariff-scenario cost modeling, and alternative sourcing strategies.
- Competitive landscaping and vendor dossiers: strategic profiles, capability matrices, and acquisition/partnering playbooks for incumbent and challenger firms.
- Commercial metrics and KPIs: content-per-vehicle models, lifetime cost-of-ownership for module suppliers, and go-to-market milestones for 12–24 month product launches.
Competitive landscape — positioning the major players
The ambient lighting value chain spans emitters and optics, driver ICs and control modules, to full-system integrators who deliver software-defined lighting experiences. Our qualitative and quantitative assessment highlights distinct archetypes among leading suppliers:
- Systems-focused integrators (e.g., long-established Tier 1s) — firms with deep OEM relationships that bundle lighting into larger interior or electrical architecture packages. Their scale and systems integration capability make them preferred partners for platform-level programs.
- Component and semiconductor specialists — producers of high-precision LEDs, driver ICs, and calibration tools who capture margin through differentiated technology (e.g., integrated color calibration, EMC-optimized PWM control, automotive qualification certifications).
- Module and optics specialists — suppliers focusing on fiber-optic distribution, micro-lightguides, and advanced lensing to produce thin, uniform illumination with minimal power draw.
- OEM captive or group suppliers — in-house or captive firms serving a single OEM group with tight co-development cycles and guaranteed content floors.
Recent market developments exemplify how technology leads commercial opportunity. For instance, the launch of advanced intelligent LED driver ICs with built-in color calibration and automotive-grade qualification marks a turning point for multi-zone control strategies, enabling scalable ECUs and simplifying software calibration at the vehicle level. Similarly, product unveilings that prioritize cabin personalization and multi-color effects demonstrate the strategic pivot from basic illumination to experiential lighting.
Dynamics, headwinds, and points of paralysis
The sector’s upside is tempered by four practical dynamics that every 2026 plan must address:
- Price erosion in LED modules: Average selling prices for LED modules have declined materially since 2020 (on the order of high single-digits annually). Suppliers must therefore combine volume scale with technology-led differentiation to protect gross margins.
- Supply-chain concentration: Key upstream LED and component capacity remains concentrated in Asia, which creates vulnerability to geopolitical shocks and logistics bottlenecks. Scenario-level procurement contingencies and dual-sourcing strategies are mandatory.
- Regulatory normalization: Recent safety regulations in major markets now include interior lighting standards — not just for illumination but for driver distraction and safety. That raises development and homologation costs, but also sets a baseline that creates competitive advantage for compliant suppliers.
- Tariff and trade risk: Tariff escalations between major blocs can materially increase bill-of-materials costs for cross-border assembly. Commercial teams must factor potential tariff passes and redesign for local content where margin sensitivity is high.
Actionable recommendations for 2026
Based on our analysis, PW Consulting recommends the following tactical moves for decision-makers preparing 2026 budgets and go-to-market plans:
- Prioritize platform deals that lock in content-per-vehicle: Secure program commitments on platform architectures rather than per-vehicle spot buys. The cumulative value of zonal lighting and software features compounds across model lifecycles.
- Invest selectively in calibration and control software: Intellectual property in color calibration and driver IC control logic is a durable differentiator as hardware ASPs compress.
- Operationalize supply resilience: Implement dual-sourcing for critical emitters, create buffer strategies for lead times, and negotiate flexible commercial terms to manage ASP declines.
- Embed compliance early: Make homologation and safety acceptance part of the earliest engineering gates to avoid late-stage rework and program delays.
- Test partnership-first M&A: For companies seeking scale, consider bolt-on acquisitions that fill specific gaps (e.g., optics, calibration IP) rather than broad horizontal deals that create integration drag.
How PW Consulting’s intelligence accelerates 2026 outcomes
Clients who adopt the insights in this study will be able to compress cycle times for supplier selection, reduce program cost overruns tied to late regulatory requirements, and identify high-ROI technology investments that withstand ASP deflation. Our scenario planning provides not only point forecasts but also tactical trigger points — the specific market and cost thresholds that should prompt contract renegotiation, platform design adjustments, or go/no-go decisions on new feature rollouts.
Finally, our vendor dossiers and scorecards convert a crowded supplier landscape into an actionable shortlist aligned to five buyer archetypes (mass-market OEMs, premium OEMs, EV-native brands, system integrators, and captive suppliers). This reduces the discovery-to-decision interval for procurement teams and helps product managers prioritize integration trials during 2026 development sprints.
Next steps — access the full intelligence
This article is a strategic preview: it signals high-conviction trends, recommended actions, and the commercial levers companies must master in 2026. The full PW Consulting report contains the granular models, supplier scorecards, regulatory compliance checklists, and scenario outputs that operational teams require to execute. For teams planning budgets, supplier negotiations, or product launches next year, the full dataset and executable playbooks are indispensable.
To engage with the complete study, our interactive datasets, and a tailor-made briefing for your executive team, please contact PW Consulting. Our analysts are ready to run customized scenarios using your portfolio and program parameters so decisions in 2026 are confident, defensible, and value-accretive.
For detailed analysis of this topic, please visit the official page: Automotive Ambient Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com