

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Optical Distribution Frame Market to Reach USD 1,685.09 Million by 2032
By pmarketresearch, 2026-07-22
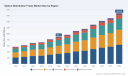
Optical Distribution Frame Market — Strategic Intelligence for 2026 Decision-Making
As communications networks scale to meet the demands of AI, cloud-native services and densified metro and edge access, the Optical Distribution Frame (ODF) market is entering a decisive growth chapter. PW Consulting’s latest industry study — anchored on a 2025 base year and projecting through 2032 — translates historic performance and forward-looking scenarios into a practical strategic playbook for executives, product leaders and investors planning actions in 2026. This preview highlights the report’s strategic value, outlines the market trajectory and competitive dynamics, and describes the operational deliverables that will directly inform capital allocation, product roadmaps and go-to-market choices. To preserve the tactical edge our clients pay for, detailed sub-segment tables and granular regional splits are intentionally withheld here; those datasets are available in the full report.
Optical Distribution Frame Market
Why this research matters in 2026
- Align CAPEX with structural growth: The ODF market has shifted from steady replacement cycles to capacity-driven expansion. Executives need validated forecasts to justify multi-year procurement and manufacturing investments.
- Prioritize product architecture choices: Decisions between ultra-high-density hyperscale designs, modular rack systems and service-oriented wall/floor mounts have material margin and lifecycle implications. Our analysis maps expected demand profiles to technical trade-offs.
- Mitigate supply-chain and sourcing risks: The study identifies bottlenecks, alternative materials and supplier concentration risks that will influence lead times and component cost volatility during 2026 procurement windows.
- Guide M&A and partnership activity: With the market showing measurable concentration among incumbents, targeted acquisitions and JV frameworks can accelerate scale or bring complementary technology into your portfolio.
- Inform go-to-market segmentation: Field sales and channel strategies must balance hyperscale wins against large telco and enterprise accounts. The report provides the evidence base to reweight commercial investments.
Market trajectory — the macro story
ODF demand has shown consistent expansion over the past half-decade and is poised to accelerate as network operators and data center builders densify fiber terminations. PW Consulting’s topline sizing traces this evolution: the global market expanded meaningfully during 2020–2025 as fiber deployments and data-center capacity ramped, and our baseline projection anticipates a near-term uplift in 2026 followed by sustained growth through 2032. Quantitatively, the study uses a 2025 base-year figure to calibrate models and applies scenario-driven adoption curves to generate a forecast path that converges on a multi-hundred-percent cumulative increase by the end of the planning window. The underlying compound annual growth rate (CAGR) we apply for the forecast period is 9.5%, reflecting a mix of replacement cycles, new-build hyperscale installations and accelerated last-mile fiberization initiatives.
Optical Distribution Frame Market
Two implications drive the strategy we recommend: first, investment timing matters — early movers who scale pre-assembled, high-density ODF platforms will capture premium hyperscale and enterprise projects; second, flexibility is essential — modular and front-access platforms will remain attractive to customers seeking lower-risk integration and staged deployment.
Optical Distribution Frame Market
Demand drivers and technology vectors
- Hyperscale data-center densification: AI workloads and converged routing fabrics are increasing fiber terminations per rack. High-splice-count, pre-assembled ODFs that simplify installation and reduce fiber handling are gaining traction.
- Telco fiberization and PON wave: Continued national broadband initiatives and operator upgrades to higher-split PONs drive telecom-grade ODF adoption in both central offices and cabinetized deployments.
- Edge and micro data centers: As computing moves closer to end users and devices, demand for compact, easy-to-service ODFs in non-traditional facilities is rising.
- Serviceability and automation: Features such as tracer fiber circuits, light-guidance for identification and tool-less modularity materially reduce mean time to repair and installation labor costs — differentiators in procurement decisions.
Competitive landscape — positioning and dynamics
The ODF market combines incumbent scale players with specialized manufacturers delivering verticalized solutions for hyperscale, telecom and enterprise customers. Market concentration metrics show that the top three vendors account for a substantive share of global revenue, and the top five further extend that concentration — a structure that favors firms with integrated product portfolios and world-class channel footprints.
- Amphenol Network Solutions (Liberty Lake, WA): Traditionally focused on high-performance connectivity, Amphenol has pushed into the hyperscale ODF niche with pre-assembled, very-high-splice-count frames that emphasize rapid deployment and lower onsite labor. Recent product introductions highlight single-fiber splicing support and tracer-fiber guidance — capabilities that directly address AI-driven data center mesh requirements.
- Huawei Technologies (Shenzhen): Huawei continues to field indoor-focused ODF series tailored for carrier access and cabinet applications. Their product set targets compatibility with standard rack sizes and high port counts in a compact footprint — a profile that appeals to telco operators modernizing access fabrics.
- CommScope (Hickory, NC): CommScope’s modular ODF platforms emphasize front-access serviceability, tool-less installation and ecosystem interoperability. Their platforms are positioned to win in environments that prioritize staged growth and cross-vendor patching simplicity.
Strategically, these vendors illustrate three viable go-to-market archetypes: hyperscale-first (pre-assembled, ultra-dense frames), carrier-optimized (space-constrained, standard cabinet compatibility) and modular-serviceable (field-configurable, integration-friendly). Each archetype carries distinct margin profiles, channel requirements and R&D imperatives.
Recent industry signals
Product innovation is accelerating. For example, a notable 2026 product launch introduced a hyperscale ODF capable of very high splice counts per frame and integrated tracer-fiber identification, packaged for pre-assembled deployment. This kind of product underscores how suppliers are responding to labor scarcity, on-site deployment risk and the need to compress build-out schedules for AI-capable facilities.
What the full PW Consulting report delivers
Our full study is structured to be immediately actionable for commercial, product and corporate development teams. Highlights include:
- Comprehensive market sizing and validated forecasts (historical 2020–2025 base, 2026–2032 forecast) with scenario modelling calibrated to infrastructure spend cycles and data-center capacity plans.
- Demand-driver analysis that links fiber counts, splice requirements, and deployment typologies to product specifications and service-cost outcomes.
- Supplier and product benchmark profiles, including technology capabilities, manufacturing footprint considerations and route-to-market assessments.
- Commercial playbooks for targeting hyperscale, telco and enterprise accounts — including tender positioning, specification negotiation levers and value-based pricing templates.
- Supply-chain risk mapping and mitigation options, highlighting critical components, lead-time hedges and alternative sourcing strategies.
- Scenario-based financial models and an interactive dataset that allows executives to stress-test revenue, margin and investment outcomes under different adoption curves.
- Go-to-market checklists, procurement-ready RFP language, and M&A screening criteria tailored to the ODF space.
Note: granular sub-segment tables and regional breakdowns are part of the full dataset; they are excluded from this preview to preserve the proprietary value delivered to PW Consulting’s clients.
Strategic takeaways and recommended actions for 2026
- For the C-Suite: Treat ODF strategy as a capacity-and-serviceability decision, not just a component purchase. Use the 9.5% forecast growth framework to align three-year CAPEX plans with anticipated order cadence, and prioritize suppliers who can guarantee delivery windows and pre-assembly options.
- For Product Leaders: Accelerate development of modular, tool-less designs and integrated tracer or identification features. A differentiated serviceability story reduces lifecycle operating expense — an increasingly persuasive procurement argument.
- For Supply-Chain Leaders: Secure long-lead items with multi-year purchase agreements and qualify second-source suppliers for critical polymer and metal components. Reducing lead-time variability is a high ROI activity in 2026.
- For Go-to-Market Teams: Create parallel plays: one focused on hyperscale and cloud builders with turnkey, pre-assembled offers; another that addresses telco retrofit and cabinetized installations with flexible rack and wall-mount options.
- For Corporate Development: Use the market concentration landscape to identify bolt-on acquisitions that either increase share in a target archetype or add niche capabilities (e.g., tracer fiber tech, splice automation) that accelerate differentiation.
How to use this briefing and next steps
This article is a strategic preview: it sets the agenda and outlines the action priorities for 2026. Executives ready to translate these insights into executable plans should access the full PW Consulting report for the underlying datasets, segmented forecasts and supplier scorecards. The full deliverable includes editable financial models, RFP language and an interactive dashboard to explore scenarios by geography, installation type and buyer segment — tools necessary to convert insight into competitive advantage.
PW Consulting is available to run bespoke workshops in which our analysts will apply the report’s models to your specific network plans and procurement timelines, producing a prioritized, time-phased investment and sourcing roadmap for 2026–2028.
Closing perspective
ODFs are no longer commoditized junctions in fiber networks — they are strategic enablers that influence deployment speed, operating cost and long-term serviceability. With the market expanding on a trajectory that implies durable demand growth, decisions made in 2026 about product architecture, supplier relationships and inventory strategies will materially affect competitive position through the next cycle. The PW Consulting study equips leaders with the quantitative baseline, competitive context and tactical playbooks necessary to navigate this inflection point. For the detailed segment tables, vendor scorecards and actionable models that power procurement and strategic decisions, consult the full report.
For detailed analysis of this topic, please visit the official page: Optical Distribution Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Logistics Robots Market Set to Soar at 16.8% CAGR Through 2032
By pmarketresearch, 2026-07-22
Logistics Robots Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As supply chains transition from episodic automation pilots to fleet-wide orchestration, 2026 marks a decisive year for enterprise leaders deciding where — and how fast — to invest in logistics robotics. PW Consulting’s Logistics Robots Market research (base year: 2025) synthesizes five years of historical performance and a seven-year forecast to 2032, translating market momentum into executable strategy. Our aim here is to preview the strategic value of the full study: enough technical and commercial depth to inform boardroom debate, while reserving the granular segmentation that drives vendor selection and ROI modelling for the full report.
Logistics Robots Market
Market Trajectory: What the numbers signal for 2026 decisions
The logistics robotics market has moved from niche automation to rapidly scaling operational platforms. According to our base-year calibration, the market expanded materially between 2020 and 2025, rising from roughly the low double‑digit millions to a mid‑hundreds figure in 2025 (USD, Million). Our forecast projects that the market will continue to expand at a robust compound annual growth rate of 16.8% across the 2026–2032 horizon, reaching approximately USD 295.0 million by 2032. Put simply: the industry is not only growing — it is compounding — and that growth is concentrated in use cases that integrate robotics with software-first orchestration and service economics (RaaS and managed automation).
Logistics Robots Market
For decision-makers, three implications are immediate: first, early adopters who standardize on modular, upgradeable architectures will extract disproportionate value; second, procurement windows in 2026 will be shaped by supplier roadmaps and component constraints (steel, control electronics); third, capital allocation should prioritize integration and change management as much as hardware acquisition.
Logistics Robots Market
Why 2026 is an inflection year
- Standards and regulations are converging. The updated ANSI/A3 R15.06-2025 safety standard and related global harmonization efforts raise the bar for functional safety and cybersecurity in logistics robotics. Enterprises that anticipate compliance costs and build them into total cost of ownership calculations will avoid downstream remediation expenses and delays to go‑live.
- Commercial models are maturing. The services economy in robotics (RaaS) has been growing rapidly; industry data documented a sharp increase in RaaS uptake and a near‑term shift to subscription and outcome-based contracting. This changes procurement calculus from CapEx-first to operational agility and lifecycle economics.
- Supply-chain pressures are real. Raw material and tariff dynamics, notably steel-related cost increases in 2025, have altered vendor pricing and lead times. Procurement in 2026 must balance speed-to-automation against negotiated supply guarantees and localization tradeoffs.
What the PW Consulting report delivers (practical, action-oriented)
This research is structured to be an operational playbook for 2026 decision cycles, not a theoretical survey. Key deliverables include:
- Executive dashboards that translate market-scale forecasts into budgetary scenarios and expected payback periods under three adoption profiles (pilot, phased roll-out, and enterprise-wide deployment).
- Vendor shortlists and capability maps that align solution archetypes (mobile fleets, robotic arms, high-density systems, humanoid and embodied platforms) with business objectives and warehouse typologies — without prescribing a one-size-fits-all supplier.
- Implementation roadmaps with milestone checklists for site surveys, safety validation (including updated standards), systems integration, change management, and KPIs for operational acceptance.
- Risk matrices covering regulatory, supply-chain, cybersecurity, and labour transition exposures — each with mitigation playbooks and contract clause templates tailored to 2026 negotiating contexts.
- Financial tools: configurable TCO calculators, CapEx vs OpEx modelling (including RaaS), and sensitivity analysis for input-cost inflation and throughput variability.
- Scenario-based projections linking robotics investments to service-level improvements, workforce re-skilling needs, and carbon/energy outcomes.
Competitive landscape: strategic reads on leading suppliers
The market shows moderate concentration with the top three players accounting for a meaningful share and the top five commanding a clear majority of revenue, signaling that scale and integrated solutions matter. However, specialist innovators continue to redefine use cases and price-performance.
- Geek+ (Hong Kong, https://www.geekplus.com) — A leader in embodied intelligence and AMR fleets. Geek+’s integrated platform strategy positions it well for large fulfillment customers seeking an end-to-end vendor capable of scaling across sites. Their recent trade-show unveilings underscore a continued push on software-first fleet orchestration.
- Locus Robotics (United States, https://locusrobotics.com) — Focused on pick-optimized AMRs and multi-robot coordination. Locus has become a preferred partner for retailers and 3PLs balancing throughput gains with incremental deployment risk.
- SEER Robotics (Europe, https://seer-robotics.ai) — A profile to watch: SEER’s recent product launches in 2026 (AI Delivery P300, embodied wheeled humanoid base) reflect aggressive moves into final-mile and intra-site humanoid-enabled logistics. Their early deliveries of embodied intelligent forklifts show an applied approach to niche, high-value workflows.
- Rapyuta Robotics (Japan, https://www.rapyuta-robotics.com) — Specializes in cloud-robotics and ASRS augmentation. Rapyuta’s platform-centric upgrades showcased at MODEX 2026 highlight the commercialization of cloud-native orchestration for mixed fleets.
- Addverb Technologies (India, https://www.addverb.com) and Exotec (France, https://www.exotec.com) — Both vendors continue to push density and throughput boundaries with carousel and Skypod-like systems. Product refreshes in early 2026 signal incremental densification and software advancements that affect site footprint decisions.
- Major integrators and robotics veterans — Amazon Robotics, Symbotic, ABB, KUKA, Toyota Industries, Fanuc, Yaskawa, KION Group, Daifuku and others remain influential through proprietary deployments, OEM partnerships, and global service networks. Their scale advantages and ecosystem reach are decisive for multi-site, multinational rollouts.
- Emerging form factors — Companies such as Agility Robotics are commercializing humanoid tote-handling capabilities that reframe automation beyond today’s pallet-and-shelf paradigms. These entrants create strategic optionality for logistics executives planning five‑plus year transformation roadmaps.
Recent vendor activity through 2026 — from product launches to live demonstrations — is accelerating the rate at which proof-of-concept results migrate to site-wide adoption. Our competitive profiles in the full report go beyond press releases: we validate claims through deployment telemetry, integration case studies, and independent performance benchmarks.
Market dynamics and risks to model in 2026 plans
- Regulatory headwinds and tailwinds. New safety standards and targeted national strategies (for example, regulatory innovation pathways for delivery robots) will create both compliance burdens and clearer routes-to-market. Early alignment with standards reduces change-order risk.
- Cost volatility. Input-price inflation, tariff regimes, and localized manufacturing incentives will create heterogenous TCOs across geographies. Procurement strategies should lock favorable terms for long-lead components and consider diversified sourcing.
- Software and integration risk. Hardware is increasingly commoditized; value accrues through orchestration, telemetry, and AI-driven optimization. Prioritize vendors with open APIs, active SDKs, and strong third-party integration references.
- Labor and social license. Workforce implications are material. Successful deployments pair automation with reskilling programs and clear communication strategies to maintain productivity and community support.
How to use this research in your 2026 decision cycle
- Use the report’s scenario models to set budget envelopes for Q2–Q4 procurement cycles and to stress-test payback timelines under input-cost and throughput variability.
- Apply the vendor capability maps and shortlists to reduce RFP cycles; combine our recommended technical must-haves with your operational KPIs to create non-negotiable selection criteria.
- Adopt the report’s phased implementation templates to align IT, facilities, compliance, and HR stakeholders around a single integrated launch plan — the velocity of benefit capture depends as much on organizational readiness as on vendor performance.
- Leverage our risk matrices when negotiating contracts to transfer key supply and compliance risks to vendors or insurers, and to structure milestone-based payments tied to verified performance metrics.
Conclusion: the strategic choice in 2026
Enterprise leaders face a binary strategic test in 2026: treat logistics robotics as an incremental efficiency program, or reposition it as the operating model around which fulfillment and distribution competitiveness is built. The market’s trajectory — demonstrated by the five‑year historical expansion and a forecasted climb to roughly USD 295.0 million by 2032 at a 16.8% CAGR over 2026–2032 — favours organizations that act decisively and architect for upgradeability.
PW Consulting’s full Logistics Robots Market report converts market-scale insight into concrete acquisition, integration, and governance actions. It intentionally preserves certain granular segmentation metrics and vendor-level performance matrices within the full document to enable validated procurement. Contact us or visit the report landing page to access the complete analysis, vendor scorecards, and the interactive financial tools that will be essential for your 2026 investment cycle.
For detailed analysis of this topic, please visit the official page: Logistics Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oligosaccharide Market to Hit USD 261 Million by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-22
Oligosaccharide Market — A 2026 Strategic Primer for Corporate Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise yet deep strategic briefing to orient executives and investment committees preparing decisions in 2026. Oligosaccharides are no longer a niche ingredient: they sit at the intersection of infant nutrition, functional foods, pharmaceuticals, and animal nutrition, and are being reshaped by technological, regulatory and supply-chain shifts. This note synthesizes the macro trajectory, competitive dynamics, and the actionable implications you need to prioritize — while preserving the granular, transaction‑level segmentation that is reserved for the full PW Consulting report.
Oligosaccharide Market
Market snapshot: trajectory and scale
From a PW Consulting base-year of 2025, the global oligosaccharide market demonstrates a steady expansion driven by diversity in product applications and ongoing investment in next‑generation manufacturing. The market grew consistently through the 2020–2025 historical window and reached approximately USD 170 Million in 2025. Under our central forecast (2026–2032), the market is expected to expand at a compound annual growth rate (CAGR) of roughly 6.5%, reaching an expected market size in the low‑hundreds of millions of USD by 2032. This pace reflects both continued adoption of traditional prebiotic ingredients and the rapid commercialization of higher‑value Human Milk Oligosaccharides (HMOs) enabled by precision fermentation and enzymatic synthesis.
Oligosaccharide Market
Why 2026 is an inflection point
- Regulation is tightening and aligning: Recent regulatory updates in leading markets are converging toward Codex and EFSA norms for infant and functional food applications. These changes compress time‑to‑market for compliant formulations but also raise the bar for dossier quality and post‑market monitoring. Corporates must align dossier, clinical and quality processes now to avoid costly reformulations.
- Manufacturing paradigms are shifting: Precision fermentation and advanced enzymatic routes are transitioning from pilot to commercial scale for HMOs and tailored oligosaccharide fractions. This opens new product differentiation but introduces capital intensity and new supplier types into incumbent supply chains.
- Input cost volatility matters: Feedstock dynamics — notably sucrose-linked prices and electricity cost variance in certain geographies — materially shape the unit economics for enzymatic FOS production. Procurement strategies and localisation choices will increasingly determine margin outcomes.
- Capacity and consolidation signals: Several suppliers announced capacity expansions in 2025–2026. Combined with a market concentration profile that leaves substantial share to a limited number of global producers, these moves affect both raw‑material demand and contract negotiation leverage for offtakers.
What the PW Consulting report delivers (practical, transaction‑ready outputs)
- Actionable demand models and scenario planners for 2026–2032 (base case, upside on accelerated HMO adoption, downside on regulatory slowdown).
- Supply‑side mapping including a capacity atlas, capital intensity benchmarks, and a vendor risk matrix to prioritize supplier diversification or backward integration.
- Regulatory playbook and dossier checklist tailored for infant nutrition and functional food claims across major markets — identifying the windows where clinical evidence investments unlock premium positioning.
- Cost‑to‑serve and margin decompositions for common product forms (powder, syrup, purified HMO fractions), enabling rapid go/no‑go commercial modeling.
- Competitive intelligence with strategic profiles, capability heatmaps and a near‑term M&A and JV pipeline assessment to support inorganic strategy.
- A granular risk heatmap covering feedstock volatility, energy exposure, regulatory bottlenecks, and product‑level safety/claims risks.
Note: core granular tables — including the full split by product type, application and region, detailed pricing curves, and company revenue by subsegment — are intentionally withheld here to preserve the integrity of our proprietary modeling. Access to those datasets is provided within the full PW Consulting report.
Oligosaccharide Market
Competitive landscape: reading the players and recent moves
The market structure reflects a mix of legacy carbohydrate ingredient producers, dairy‑origin specialists, and newer biotech entrants. Industry concentration measures indicate a marketplace where the top three players do not dominate outright but where the top five command meaningful influence — a structure that supports both competition and opportunistic consolidation.
- BASF SE: An incumbent with capabilities in enzymatic and fermentation routes, focusing on higher‑value HMOs for infant nutrition. Their integration of fermentation know‑how and nutrition customers gives them a strategic advantage in supplying formulation‑grade HMOs.
- DSM‑Firmenich: A strategic player in HMOs through partnerships and acquisitions; their R&D‑led approach and established infant‑nutrition client base position them to capture premium HMO demand.
- Shandong Bailong Chuangyuan Bio‑Tech: A large Chinese manufacturer with a broad oligosaccharide portfolio for food and infant applications. Their scale in conventional prebiotics positions them as a competitive, cost‑sensitive supplier to regional markets.
- Galam Ltd.: Focused on short‑chain FOS and niche branded ingredients, Galam’s recent capacity additions and automation investments signal intent to meet global prebiotic demand with high‑throughput, quality‑controlled output.
- FrieslandCampina Ingredients: A dairy‑origin specialist whose branded GOS offerings are well entrenched in infant formula markets; strategic expansions in dairy ingredient capacity indicate a push towards integrated value propositions.
- Van Wankum Ingredients: A specialist supplier of GOS and IMO in multiple delivery forms, serving food and supplement customers with flexible commercial terms and production formats.
- BENEO: Combining traditional FOS from chicory with developing HMO capabilities, BENEO has recently progressed commercial supply partnerships that accelerate HMO availability via precision fermentation.
- Sensus America Inc.: Focused on inulin‑type FOS for food and supplements, Sensus maintains a strong position in ingredient innovation for functional formulations.
Notable near‑term developments to monitor: a major precision‑fermentation 2’‑fucosyllactose supply alliance announced in 2025, multiple FOS capacity expansions brought online in 2025–2026, and strategic dairy‑ingredient facility upgrades. These moves collectively increase supply of both conventional prebiotics and next‑gen HMOs, compressing time‑to‑market for novel formulations while heightening competitive intensity.
Strategic implications and a practical 2026 playbook
- Prioritize regulatory‑led product roadmaps: For companies targeting infant nutrition or health claims, invest in clinical/technical dossiers now — regulatory alignment in key jurisdictions is increasingly a gating factor for premium pricing and market access.
- Hedge feedstock and energy exposure: Build procurement hedges, explore regional sourcing, and legally ring‑fence long‑term offtakes where feasible. For higher margin HMO lines, consider location choices that favour stable energy and fermentation‑friendly cost bases.
- Decide on make vs. buy with a 24–36 month horizon: For firms seeking control over supply and margin, contract manufacturing or backward integration into enzymatic/fermentation capacity can be justified — but only after stress‑testing scenarios against our forecasted demand and capital payback profiles.
- Use M&A selectively: Targets with validated IP in HMO synthesis, stable regulatory dossiers, or regional manufacturing footprints can accelerate entry. Prioritize deals that close material capability gaps rather than horizontal scale alone.
- Differentiate commercial propositions: Move beyond commodity pricing to offer formulation support, claim substantiation, and supply certainty. Bundling oligosaccharides with complementary nutrition ingredients is a proven route to protect margin.
- Prepare contingency playbooks: Regulatory delays, feedstock shocks, or clinical setbacks can create abrupt demand swings. Scenario playbooks should include rapid reformulation, dual‑sourcing triggers, and contract exit options.
- Embed sustainability into sourcing and claims: Given buyer sensitivity and emerging policy frameworks, credible sustainability narratives — traceability of feedstock and low‑carbon processing routes — will be commercial differentiators by 2028.
How PW Consulting helps in execution
For 2026 planning cycles, PW Consulting delivers tailored advisory support ranging from discrete financial modeling for capital projects to full M&A due diligence and regulatory dossier gap analyses. Our integrated approach aligns commercial research with operational feasibility and regulatory timelines so that leadership teams can move from strategy to executable roadmaps within quarter‑by‑quarter milestones.
In closing: the oligosaccharide market offers growth with clear avenues to margin uplift — but success in 2026 depends on integrating regulatory foresight, supply‑chain resilience and targeted capability investments. This briefing outlines the strategic contours; the proprietary datasets, granular segmentation, and transaction‑level recommendations are available in the full PW Consulting Oligosaccharide Market report. Contact our team to access the models and scenario toolkits that support board‑level decisioning.
For detailed analysis of this topic, please visit the official page: Oligosaccharide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Daylight Fluorescent Pigments Market to Expand at 8.2% CAGR
By pmarketresearch, 2026-07-22
Daylight Fluorescent Pigments Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking briefing on the Daylight Fluorescent Pigments market designed to orient executive decision-making in 2026. This preview highlights the structural forces, competitive moves, and near-term inflection points that will determine winners and laggards over the forecast horizon — while intentionally withholding granular segment and regional tables found in our full study to preserve proprietary value and drive direct engagement for transaction-grade intelligence.
Daylight Fluorescent Pigments Market
Market at a glance
The daylight fluorescent pigments market is on a clear growth trajectory following strong recovery and steady expansion through the base year 2025. Our consolidated model shows the market enlarging from a mid-three-hundreds million USD base in the early 2020s to approximately USD 465.4 Million in 2025, with a projected compound annual growth rate (CAGR) of 8.2% over the forecast window beginning 2026. By the end of the forecast horizon, this growth dynamic supports a materially larger global market, reflecting both sustained end-market demand and value capture from premiumized, sustainable formulations.
Daylight Fluorescent Pigments Market
- Base year and historical context: 2020–2025 data capture the post-pandemic rebound and early-stage sustainability-driven reformulation investments.
- Forecast framing: 2026–2032 modeling embeds scenario-based sensitivities for regulation, raw material inflation, and technology substitution (e.g., LED-optimized pigments).
Key market dynamics shaping 2026 decisions
- Regulatory pressure as a catalyst for product change: Systematic restrictions on legacy chemistries (notably around certain azo compounds) under frameworks such as the EU’s REACH are accelerating reformulation investments. Firms that anticipate testing and certification timelines will shorten commercialization lead times and protect channel access.
- Sustainability and formulation innovation: Buyers increasingly demand lower-VOC carriers, bio-based feedstocks, and aqueous-compatible dispersions. Recent launches of eco-focused pigment lines from incumbent manufacturers indicate that product differentiation will increasingly hinge on regulatory compliance and environmental credentials.
- Input-cost volatility: Upward pressure on petrochemical inputs (melamine, toluene and allied feedstocks) is stressing gross margins for commodity-grade pigments. Effective 2026 strategies will combine supplier hedging, formula redesign to reduce dependence on high-cost intermediates, and value-based pricing for premium, compliant offerings.
- Trade and tariff friction: Recent tariff classification decisions and evolving import controls add friction to global supply chains. Manufacturers and buying organizations must embed tariff-scenario planning into sourcing and nearshoring evaluations to avoid margin erosion.
- Application-driven adoption and technology adjacency: Demand remains strong across traditional product families — paints & coatings, plastics, and printing inks — while newer opportunities emerge from LED-optimized decorative paints and specialty cosmetic applications. Success requires co-development and validated performance claims (lightfastness, dispersibility, pigment stability under LED exposure).
Competitive landscape — what incumbents and challengers are doing
The market exhibits a moderate level of concentration: the top three players collectively command just over half of the market, with the top five approaching six-tenths. This structure rewards scale players for distribution reach and formulation R&D, while leaving space for specialized players to capture premium niches.
Daylight Fluorescent Pigments Market
- DayGlo Color Corp (Cleveland, Ohio): The historical market leader is leveraging its brand and formulations expertise with a recent push into bio-based raw materials and eco-series pigments. For corporate strategists, DayGlo’s move signals that brand equity plus sustainability is a defensible playbook for packaging and textile customers who prioritize verified green credentials.
- Radiant Color N.V. (Houthalen, Belgium): Radiant’s expansion into resin technology and the opening of a Resin Centre of Excellence signals an upstream integration strategy: proprietary resin carriers and dispersion science can create higher switching costs with OEMs that require tight process compatibility and regulatory traceability.
- Wanlong Chemical (Ruian, China): Wanlong’s active participation in major trade shows and promotion of high-brightness AX series underscores how Chinese manufacturers are pushing both price and performance. They remain a critical part of the global supply map — especially for converters seeking competitive cost structures — but will need to integrate sustainability claims to maintain access to regulated markets.
- SINLOIHI (Japan): Focused on ultra-bright, durable pigments and LED-specific formulations, SINLOIHI demonstrates the value of narrow technological specialization that addresses rising demand for LED-compatible decorative and industrial coatings.
- Regional and niche specialists: Suppliers such as Aron Universal, LuminoChem and Huangshan Jiajia illustrate differentiated plays — from textile and sportswear colorants to eco-safe aqueous chemistries and capacity expansion for packaging applications. These firms are the likely targets for strategic partnerships or bolt-on acquisitions by larger pigment players seeking rapid capability access.
Implications for commercial and M&A strategies
- Premiumization and margin recovery: Manufacturers that layer verified sustainability features and validated performance (e.g., LED resistance, washfastness for textiles) can reframe pricing discussions. Commercial teams should develop TCO narratives for customers that internalize formulation longevity and regulatory risk mitigation.
- De-risking the supply chain: Given trade and feedstock volatility, companies should pursue multi-sourcing, local blending hubs, and strategic inventory buffers for critical intermediates. A short list of qualified upstream partners and a supplier scorecard is essential to preserve production continuity.
- M&A and partnership criteria: Targets that deliver regulatory expertise, resin carrier IP, aqueous-dispersion capabilities, or regional footholds in fast-growing end markets are high-priority. Bolt-on plays can be faster and cheaper than greenfield R&D in achieving compliant formulations at scale.
- R&D and go-to-market playbooks: Investment in rapid prototyping, accelerated stability testing under LED/UV exposure, and validated OEM compatibility will shorten sales cycles. Co-development pilots with major coatings and plastics converters serve as both technical proof points and embedded commercial pathways.
What PW Consulting’s full report provides (practical, transaction-grade deliverables)
Our complete Daylight Fluorescent Pigments Market study provides the operational intelligence that executive teams and investment committees need to make defensible 2026 decisions. Key components include:
- Verified historical market sizing (2020–2025) and a transparent forecasting model (2026–2032) built on bottom-up demand drivers and price-volume dynamics.
- Scenario-based revenue and margin models incorporating regulatory shock cases, raw material inflation pathways, and tariff stress-tests.
- Detailed competitive benchmarking and supplier scorecards covering R&D capability, geographic footprint, sustainability credentials, and commercial reach.
- CapEx and capacity maps, highlighting recent expansions and near-term bottlenecks — enabling capacity planning and contract negotiation strategies.
- Regulatory risk heatmaps (REACH and other jurisdictional regimes), plus a compliance timeline that flags critical decision points for reformulation and testing.
- Go-to-market playbooks and commercial templates: value messaging for premium formulations, distributor segmentation strategies, and an OEM partnership checklist.
- M&A playbook: target selection criteria, valuation multiples observed in related specialty chemical transactions, synergy levers, and integration risk mitigants.
- Practical tools: supplier diligence checklist, sample technical specification templates for pigments and dispersions, and pilot-to-scale validation protocols.
Note: The full report contains granular segmentation matrices (by type, application and region), unit-price trajectories, and channel-specific demand shares. Per this preview’s “trailer” intent, those tables and model outputs are gated in the core deliverable.
Priority actions for decision-makers in 2026
- Initiate an immediate compliance review of product portfolios against REACH and evolving North American/Asian environmental controls; prioritize reformulation projects with the shortest regulatory lead times.
- Implement raw-material hedging and dual-sourcing policies for key petrochemical inputs; build scenario-based inventory policies to absorb short-term shocks without pushing prices to contract customers.
- Pursue partnerships or licensing agreements with resin and dispersion specialists to accelerate market entry for aqueous and bio-based pigment systems.
- Accelerate pilot deployments for LED-optimized pigments with selected coatings and plastics OEMs to convert application-specific performance into commercial contracts.
- For investors: prioritize targets with proprietary carrier chemistry, regulatory dossiers, and validated customer trials; expect value creation through operational integration rather than top-line rerating alone.
Conclusion: With a robust CAGR and expanding application set, the daylight fluorescent pigments market offers attractive growth — but not without strategic complexity. Regulatory headwinds, input-cost pressure, and evolving application requirements create both risk and opportunity. Incumbents with scale can defend positions via brand and distribution, while nimble specialists that own formulation IP or sustainability credentials can command premium pricing and strategic partnerships.
To convert these directional insights into actionable plans — including the full set of segment-level tables, regional allocations, price models, and the proprietary scenario workbook — access PW Consulting’s comprehensive report and model. The full deliverable contains the transaction-grade detail required to make confident 2026 investment, sourcing, and commercial decisions.
For detailed analysis of this topic, please visit the official page: Daylight Fluorescent Pigments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: Medical Cyclotron Market Poised for 6.9% CAGR Through 2032
By pmarketresearch, 2026-07-22
Medical Cyclotron Market — Strategic Brief for 2026 Decision Makers
As the senior industry analyst at PW Consulting, I prepared this advance strategic brief to frame the decision-making landscape for organisations considering investments, partnerships, or operational shifts in the medical cyclotron value chain in 2026. Think of this as the trailer to our full Market Research report: it surfaces the decisive macro trends, competitive posture, regulatory inflection points, and recommended strategic responses — while intentionally withholding granular segment-level tables and proprietary model outputs to preserve the report’s tactical value and invite deeper engagement.
Medical Cyclotron Market
Market trajectory at a glance
The medical cyclotron market is in a sustained growth phase driven by accelerating adoption of cyclotron-produced isotopes for both diagnostic and therapeutic (theranostic) use. On a macro basis, the market expanded from approximately USD 189 Million in 2020 to USD 252 Million in our 2025 base year and is projected to continue expanding at a compound annual growth rate (CAGR) of roughly 6.9% over the 2026–2032 forecast horizon, reaching an estimated USD 398 Million by 2032.
Medical Cyclotron Market
These headline numbers reflect two complementary dynamics: (1) steady replacement and augmentation capex in established diagnostic circuits as PET/SPECT demand grows; and (2) a disproportionately faster uplift in investments tied to theranostics (alpha- and beta-emitter production) as clinical approvals and reimbursement pathways widen. For executives evaluating capital allocation in 2026, it is critical to treat the headline growth rate as directional — instructive for portfolio sizing and scenario planning — but to rely on detailed, location- and application-specific modeling when finalising plant capacity, financing structure, and partner selection.
Medical Cyclotron Market
Why 2026 is a strategic inflection point
-
Regulatory momentum has lowered technical and commercial barriers. Recent regulatory actions — including FDA clearances and target action dates for cyclotron-produced Ga-68 processes and approvals expanding theranostic radioligands — convert several previously theoretical use-cases into commercially actionable opportunities. These developments materially affect demand profiles for both compact on-site units and higher-energy production cyclotrons.
-
Reimbursement codification for cyclotron-produced isotopes is beginning to map to billing pathways, changing business model economics for hospital-based production and third-party radiopharmacies. Decision-makers must model reimbursement timing and sensitivity carefully when evaluating project IRRs in 2026.
-
Technology differentiation and consolidation are both increasing. The market is concentrated among a small set of global vendors (top three firms account for a significant majority of market revenue; top five capture an even larger share), which creates a dual risk and opportunity: established OEMs can accelerate adoption through bundled solutions, but specialised entrants and manufacturing-focused players can win by aligning to vertical manufacturing or service models.
Competitive landscape — profiles that matter for 2026
The competitive map in 2026 is shaped by legacy OEMs that combine proven cyclotron platforms with global service footprints, specialist manufacturers focused on high-throughput or high-energy machines, and nimble new entrants that pair compact cyclotrons with integrated radiopharmaceutical manufacturing. Key company archetypes to watch include:
-
IBA (Louvain-la-Neuve, Belgium) — A long-standing leader in particle accelerator technology offering a portfolio that spans routine PET isotope production through to platforms engineered for alpha emitter manufacture. Recent product introductions focused on industrial-scale At‑211 production underscore IBA’s strategy to capture the emerging alpha-therapy manufacturing opportunity while minimising operational exposure and footprint for customers.
-
GE HealthCare (Chicago, US) — Leveraging both installed base and integrated imaging and radiopharmacy workflows, GE continues to position its cyclotrons as part of on-site precision medicine ecosystems. Recent installations at academic medical centres illustrate a strategy to combine device sales with long-term service and consumables revenue.
-
Advanced Cyclotron Systems Inc. (ACSI) (Canada) — Focused on high-output machines that target both PET/SPECT supply and larger-scale isotope production. Investments in manufacturing capacity point to a play for global supply contracts and OEM partnerships.
-
Ionetix (US) — Representative of the compact superconducting cyclotron camp, Ionetix pairs smaller footprint devices with full-service radiopharmaceutical manufacturing capabilities — an attractive model for health systems seeking verticalised on-site production.
-
Sumitomo Heavy Industries (Japan) — A regional stronghold with reliable compact machines and strong after-sales support in established markets, fitting the needs of conservative hospital buyers and national programmes focused on operational reliability.
Recent corporate moves in 2025–2026 illustrate tactical themes: product launches optimised for alpha emitters, new facility construction to expand manufacturing throughput, and strategic installations at leading academic medical centres to demonstrate production models for advanced radiopharmaceuticals. These developments signal that incumbents are simultaneously defending installed bases and pivoting to capture theranostics growth.
Practical contents of the full PW Consulting report
Our full Market Research report is operationally focused to support board- and C-suite-level decisions in 2026. The deliverables include:
- Proprietary market model (historical 2020–2025, base-year 2025; segmented forecasts through 2032) with interactive scenario toggles (pricing, regulatory timing, reimbursement speed, and capacity utilisation).
- Investment case templates and capital budgeting models for compact and high-energy cyclotron projects (including capex/opex benchmarks, payback sensitivity, and financing structures).
- Go-to-market playbooks for OEMs, radiopharma manufacturers, and hospital purchasers, including channel strategies, service economics, and consumables monetisation.
- Vendor scorecards and a vendor short-list based on technology fit, service footprint, regulatory readiness, and strategic alignment with theranostics demand.
- Regulatory and reimbursement tracker with implication matrices tied to commercial scenarios — specially curated for North America and other priority markets.
- Supply chain risk assessments and mitigation options for critical components, maintenance services, and workforce training needs.
- M&A and partnership heatmaps highlighting targets by capability (manufacturing scale, isotope expertise, distribution reach) and illustrative deal structures.
- Primary interview synthesis from operators, radiochemists, hospital procurement leads, and OEMs validating model assumptions and near-term adoption barriers.
Note: In this brief we intentionally do not publish the detailed segment tables, regional split matrices, unit economics and customer-level forecasts that are part of the full deliverable. Those elements are the actionable core of the report and are best consumed in the full product or via a PW Consulting advisory engagement.
How to use this intelligence in 2026 — five priority moves
-
Align capital plans to regulatory and reimbursement cadence: Accelerate or delay final investment decisions based on the timing of documented regulatory approvals and newly codified billing pathways. Even a six‑to‑twelve month shift in approval or reimbursement windows materially changes project IRR for greenfield facilities.
-
Choose product architecture to match business model: Hospitals and radiopharmacies targeting localised, flexible supply should prioritise compact superconducting units bundled with integrated manufacturing services. Organisations focused on contract manufacturing or national supply should evaluate higher-energy, high-throughput platforms.
-
Factor vendor concentration into counterparty risk: With industry concentration skewed toward a handful of leaders, buyers should include dual-sourcing, robust service SLAs, and contingency plans in procurement contracts.
-
Prepare for workforce and compliance lift: Theranostics production introduces additional handling, radioprotection, and quality systems complexity. Early investment in training, process validation and regulatory submissions reduces time-to-market and operational risk.
-
Evaluate vertical partnership models: For many players, partnering (OEM + radiopharma + healthcare system) is a lower-capex route to secure supply chains and accelerate patient access; consider revenue-share or output-based contracts as alternatives to outright capital ownership.
Risk considerations and mitigation
Key risks that decision-makers must stress-test in 2026 include: regulatory delays or narrower-than-expected approvals, slower reimbursement roll-out, supply-chain fragility for critical cyclotron components, and operational complexity tied to alpha-emitter production. Effective mitigations include staged investment, modular expansions, contractual service guarantees from OEMs, and defensive inventory strategies for consumables and spare parts.
Next steps — how PW Consulting can help
If you are evaluating manufacturing capacity, considering an OEM selection, or planning market entry, the full PW Consulting Medical Cyclotron Market report and a short advisory engagement will equip your team with the granular forecasts, vendor benchmarking, and executable business cases required to act confidently in 2026. Our engagements typically combine the report’s quantitative model with a tailored workshop to translate scenarios into board-ready investment proposals and procurement specifications.
To access the full intelligence package, methodology appendices, and proprietary segment models — or to schedule a briefing with our consultants — visit the PW Consulting report page or contact our business development team. This brief is intended to start the conversation; the full report contains the tactical tables and scenario outputs you will need to execute.
For detailed analysis of this topic, please visit the official page: Medical Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind Power Coatings Market Poised for 10.8% CAGR Through 2032
By pmarketresearch, 2026-07-22
Wind Power Coating Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present an evidence‑based strategic primer designed to orient C‑suite teams, corporate development leads, supply‑chain managers, and product strategists as they make pivotal decisions in 2026. This piece synthesizes our latest Wind Power Coating Market research (base year 2025) and highlights the strategic levers and near‑term uncertainties that will determine competitive outcomes over the 2026–2032 forecast horizon.
Wind Power Coating Market
High‑level market trajectory: what the headline numbers mean for strategy
The wind power coating market is on a sustained growth path — our baseline model, anchored by a 2025 market size and projecting through 2032, implies a compound annual growth rate of 10.8% across the forecast period. In practical terms, the market grows from an established base in 2025 into a materially larger opportunity by 2032, driven by a combination of new turbine installations, blade and tower refurbishment cycles, and a progressive shift to higher performance, longer‑life coating systems.
Wind Power Coating Market
For 2026 decision‑makers this trajectory creates three strategic imperatives: (1) secure raw‑material resilience and price hedges; (2) align product roadmaps to stricter regulatory and testing standards; and (3) structure commercial models that capture aftermarket and service revenue as installations age. The market size growth provides the financial scope for targeted R&D investments, bolt‑on M&A, and channel expansion — but only when those actions are informed by granular segment economics and scenario planning (which our full study delivers).
Wind Power Coating Market
Drivers of demand — and where growth really comes from
- Fleet expansion and blade scaling: Larger rotors and higher turbine capacities increase coating surface areas and intensify performance requirements (UV, erosion, corrosion resistance).
- Aftermarket and repairs: As installed bases mature, demand for leading‑edge repair systems, touch‑up gels, and on‑site remediation grows faster than new‑build coatings in many markets.
- Offshore acceleration: Offshore environments demand premium protective systems; higher capex per asset translates into higher per‑unit coating value and longer product lifecycles.
- Regulatory and standards convergence: Emerging test standards for ice adhesion, hail resistance, and increasingly stringent emissions rules are elevating specifications and favoring compliant, higher‑margin formulations.
These drivers create product‑ and channel‑specific demand pockets. However, precise segment allocations and regional breakdowns are intentionally withheld here to encourage stakeholders to consult the full dataset and interactive models in our report — those deliver the actionable granularity needed for capital allocation and commercial planning.
Supply‑side structure and concentration — implications for competition
The market exhibits moderate concentration: the top three suppliers account for a significant share of industry revenue while the top five raise that share further, leaving a meaningful long tail of specialized and regional players. This concentration profile creates a dual reality for strategists:
- Incumbent advantage: Large coatings manufacturers benefit from scale in R&D, global service networks, and access to major OEM contracts, enabling rapid adoption of new specification‑grade systems.
- Opportunity windows: Niche innovators and formulators can capture premium aftermarket and repair niches by delivering differentiated performance (e.g., fast‑curing, solvent‑free epoxies or specialized leading‑edge elastomers).
Understanding where your company sits along this spectrum — incumbent, challenger, or niche supplier — determines the optimal blend of product investment, partnership, and M&A tactics in 2026.
Competitive feature map: what leading suppliers are emphasizing
- Integrated system providers (large multinationals): Focus on end‑to‑end solutions that include resins, coatings, and global application support. They leverage scale to offer validated systems for blades, towers, nacelles and foundations.
- Specialist formulators: Emphasize high‑performance niche chemistries such as fluoropolymer topcoats, elastomeric repair systems, and rapid‑cure in‑mould gelcoats optimized for production throughput.
- Raw‑material innovators (polymer resin suppliers): Target upstream innovation in polyurethane and epoxy intermediates to influence OEM specifications and lock in supply relationships.
Recent industry moves illustrate these priorities. There have been product launches in 2025–2026 focusing on solvent‑free, fast‑curing epoxy in‑mould gelcoats that enhance processing speeds, and updates to leading‑edge repair formulations that materially shorten repair time while improving erosion resistance. These developments underscore a market where performance, compliance, and production efficiency are intertwined.
Regulation, standards, and material volatility — non‑price risks that demand strategy
Regulatory pressure and evolving technical standards are a core part of the operating environment. Across Europe and key export markets, restrictions on solvent‑based chemistries are tightening, and new ISO technical specifications for ice‑adhesion and hail resistance are shaping product acceptance criteria. These changes are not peripheral: they alter formulation roadmaps, test protocols, and time‑to‑market.
Concurrently, upstream raw materials — notably isocyanates, epoxy resins, and fluoropolymer intermediates — remain exposed to petrochemical price swings. Firms that fail to integrate material‑price risk management into procurement and product pricing will see margin compression or face abrupt R&D reprioritization. In 2026, leading players will combine long‑term supplier contracts, strategic inventory, and formulation flexibility to mitigate this exposure.
Practical plays for 2026 — prioritized actions with immediate ROI
- Product strategy: Accelerate development and validation of low‑VOC, solvent‑free systems and engineered repair kits that pass the latest standardized tests. Prioritize short cycle‑time solutions that reduce downtime for operators.
- Commercial model: Expand service‑led offerings (application training, on‑site repair crews, performance warranties). Aftermarket services are a high‑margin lever and a defensible lock‑in mechanism.
- Supply‑chain resilience: Secure conditional offtake or tiered pricing agreements for key resin inputs; evaluate backward integration where scale justifies it.
- M&A and partnerships: Pursue tuck‑ins that bring specialized chemistries or regional channel access; form co‑development alliances with OEMs to embed your systems into new turbine builds.
- Regulatory readiness: Integrate compliance roadmaps into product development and pre‑qualification programs to avoid lost time in certification cycles.
Scenario planning — monitoring the triggers that shift strategy
Use the following three scenarios to stress‑test plans and KPIs in 2026:
- Base Case (aligned with our 10.8% CAGR): Gradual offshore expansion, steady aftermarket growth; invest selectively in product upgrades and service scale.
- Upside: Accelerated offshore rollouts and aggressive repowering programs expand addressable coating surface area faster than forecast — accelerate capacity expansion and prioritize premium product launches to capture value.
- Downside: Raw‑material shocks combined with stricter solvent bans slow procurement and push OEMs to extend service intervals — emphasize cost‑effective formulations, flexible contracts, and defensible service revenue.
Key leading indicators to track monthly: offshore capacity announcements, OEM blade size trends, regulatory publication timelines, resin price indices, and aftermarket service contract volumes. These will give you advance signal to reallocate capital or accelerate commercialization.
What our full report delivers — practical, executable outputs
PW Consulting’s full Wind Power Coating Market study translates this strategic narrative into operational tools that leaders use to make confident 2026 decisions. Highlights include:
- Granular, model‑backed market sizing and a segmented forecast with sensitivity testing across adoption curves and price scenarios.
- Value‑chain maps with cost and margin waterfalls for coatings, resins, and services.
- Competitive benchmarking profiles and product‑feature matrices for leading suppliers.
- Regulatory and standards tracker with compliance timelines and product impact scoring.
- Commercial playbooks for OEM engagement, aftermarket monetization, and supply‑chain hedging strategies.
- Investment and M&A screening criteria, including an actionable short list of targets and partnership archetypes.
Note: this primer is intentionally a strategic overview. We deliberately withhold the segmented numeric breakdowns and regional allocations here — those granular datasets, interactive models, and downloadable spreadsheets are available in the full report and through our tailored advisory engagements.
Concluding recommendation — action in 90 days
For 2026, prioritize three immediate actions: (1) finalize a raw‑material risk assessment and secure conditional supply arrangements; (2) launch a compliance fast‑track for solvent‑free and test‑aligned formulations; and (3) pilot a service‑led aftermarket offering in one priority geography to validate unit economics. These moves position your organization to capture the upside of the market’s 10.8% growth trajectory while insulating margins from regulatory and input volatility.
To convert this strategic guidance into executable plans — including the segment‑level forecasts, regional opportunity maps, and supplier scorecards that underpin capital allocation and commercial targeting — download our full Wind Power Coating Market report or contact PW Consulting for a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Wind Power Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Train Seat Market to Hit USD 207.6M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-22
Train Seat Market 2026: Strategic Imperatives for Operators, OEMs and Tier-1 Suppliers
Introduction
As the rail sector reconfigures for a greener, more connected decade, seating — long treated as a commodity — has become a decisive competitive element. This PW Consulting briefing introduces our latest Train Seat Market research (base year 2025, historical 2020–2025, forecast 2026–2032). It distills the strategic implications C-level executives, procurement leads and product teams must weigh in 2026, while deliberately preserving the granular segmentation and proprietary datasets that make the full report an indispensable decision tool.
Train Seat Market
Executive snapshot: the market at a glance
After steady expansion through the pandemic recovery, the global train seat market reached an important inflection in our 2025 base year. Historical tracking from 2020–2025 shows persistent demand driven by infrastructure roll-outs, rolling-stock renewals and rising passenger expectations. Our projections through 2032 deliver a compounded annual growth rate (CAGR) of 5.2%, positioning the market for continued, predictable expansion into the early 2030s.
Train Seat Market
What this means in practice: capital planning horizons for operators and OEMs should assume sustained procurement and retrofit activity, with meaningful upside for suppliers that can couple comfort, durability and regulatory compliance with cost-efficient production.
Train Seat Market
Why this research matters for 2026 decision cycles
- Align CapEx with demand trajectories — The report translates macro growth into procurement scenarios and multi-year spend envelopes so asset owners can prioritize refurbishment versus new-build seating strategies.
- De-risk product roadmaps — We map how regulatory headwinds (notably fire-resistance and interior safety standards) and material cost volatility affect development timelines and BOM choices.
- Design-to-cost and lifecycle optimization — The study provides TCO frameworks enabling product teams to balance lightweight materials, modularity and recyclability without sacrificing compliance.
- Supply chain and footprint decisions — For manufacturers and Tier-1s, our analysis supports nearshoring, expansion or consolidation options aligned to demand clusters and cost pressures.
- M&A and partnership playbooks — Investors and strategic buyers get scorecards and integration considerations that spotlight where consolidation or capability investments yield the highest returns.
What’s inside the full PW Consulting report (practical, operational outputs)
- Robust market-sizing and forecast model (2020–2032) with scenario runs (base, upside, downside) suitable for board-level planning.
- Demand-driver decomposition and surfacing of structural shifts: modal shift, urban transit expansion, long-distance high-speed programs and retrofit cycles.
- Cost and input-material sensitivity analysis: aluminium, foam, composites and subassembly labor metrics tied to margin implications.
- Regulatory and standards mapping with practical compliance checklists and impact scoring on time-to-market.
- Supplier due-diligence templates and a competitive heatmap that ranks incumbents and challengers across capability, scale and innovation.
- Procurement playbooks and spec-for-cost templates for operators deciding between modular retrofits and full OEM seating packages.
- Case studies and lessons learned from recent fleet introductions and product launches to accelerate decision cycles and reduce implementation risk.
Competitive landscape: who matters and why
The market exhibits moderate concentration: the top three players account for a meaningful share of revenue while the top five approach parity with a still sizable independent supplier base. This structure fosters both scale advantages for established suppliers and opportunity windows for specialised, fast-moving entrants.
- GRAMMER AG (Ursensollen, Germany) — A full-line supplier with deep pedigree across driver and passenger seating. Their integrated product suites and aftermarket services make them a logical anchor for operators seeking single-source solutions and lifecycle management.
- Franz Kiel GmbH (Nördlingen, Germany) — Known for modular, vandalism-resistant designs and material innovation. Recent moves (a high-tech recyclable monomaterial seating platform unveiled at a major trade fair and a new production site to expand capacity) underscore a playbook focused on sustainability at scale.
- RECARO Rail (Poland) — A comfort- and customization-focused player targeting intercity and metro applications. Their strength lies in highly individualized seating systems and durability credentials valuable for premium service tiers.
- Freedman Seating Company (USA) — A North American specialist in commuter and light-rail seating, with proven competence in volume delivery and local compliance — an attractive partner for operators with regional fleets.
- Compin Fainsa (France/Spain) — Specialist in high-speed and ergonomic seating for European operators, built around modularity and rapid integration into new-build platforms.
- Transcal Ltd (UK) — Offers design-to-manufacture capability with emphasis on lightweight and modular options; a candidate for OEM partnerships where bespoke engineering is required.
- Aisin Shiroki Corporation (Japan) — Brings automotive-grade materials and processes to rail seating, accelerating lightweight, ergonomic and high-durability solutions that can reduce lifecycle costs.
Recent fleet introductions (notably multiple flagship trains introduced across Europe and North America in 2025) are already reshaping demand profiles and supplier selection criteria. Manufacturers that can demonstrate verified compliance, repeatable quality and flexible capacity will capture a disproportionate share of the forthcoming procurement waves.
Key trends and market dynamics through 2032
- Regulatory tightening elevates time-to-market costs — Stricter fire and interior safety standards lengthen development cycles and raise compliance costs for seat makers. Firms must bake compliance verification early into design sprints.
- Sustainability and recyclability as procurement filters — Operators seek seats engineered for disassembly and material recovery; recyclable monomaterial platforms are becoming procurement differentiators.
- Material-price volatility — Aluminium, foams and composite costs remain a primary margin pressure. Hedging strategies and alternative material R&D are now core strategic initiatives.
- Modularity and retrofitability — Given constrained operator budgets, modular seating platforms enabling staged upgrades will outcompete bespoke full-interior replacements in many segments.
- Competition and price pressure in liberalized markets — Lower ticket prices in some regions translate into tighter operator budgets, shifting the conversation toward TCO and maintenance efficiency rather than upfront unit price alone.
- Infrastructure growth drives baseline demand — Urban transit expansions and intercity capacity programs underpin a reliable market floor for seats, though product mix varies by application.
Actionable recommendations for 2026 (short- and medium-term)
- For operators: adopt a TCO-first procurement framework that weights durability, maintenance cadence and recyclability equally with unit price. Pilot modular platforms on low-risk corridors to validate lifecycle claims before fleet-wide rollouts.
- For OEMs and suppliers: prioritize certifiable materials and pre-approved safety pathways to compress lead-times. Invest selectively in regional capacity where demand density aligns with logistics savings and regulatory compatibility.
- For investors and corporate strategists: target bolt-on acquisitions that fill capability gaps (e.g., recyclable-material engineering, rapid-prototyping centres) rather than scale-only deals. Use the market’s fragmented mid-tier as consolidation fodder to build integrated seating lifecyle services.
- Cross-cutting: embed scenario-sensitivity into every capital allocation decision — model material-price shocks, regulatory shifts and shifts in retrofit vs replacement mix to stress-test business plans.
How PW Consulting’s Train Seat Market study supports 2026 decision-making
Our study combines granular, auditable market-sizing with operational playbooks and supplier benchmarking calibrated to the 2026 procurement landscape. The deliverables include customizable spreadsheets, procurement templates and a supplier scorecard that lets teams rank partners by capability, cost and compliance readiness. For boards and executive teams, the report provides prioritized, time-bound initiatives that translate market signals into executable roadmaps.
To preserve the competitive value of our proprietary segmentation and supplier scorecards, this briefing intentionally omits core regional and application splits. The full report contains those detailed matrices, along with downloadable models that executive teams can run against their own fleet and capex schedules.
Next steps
Leaders preparing budgets and product roadmaps for 2026 should treat seating as a lever for passenger experience, regulatory resilience and lifecycle cost reduction. PW Consulting’s full Train Seat Market study equips you to convert that insight into contracts, products and strategic investments with measurable ROI. For stakeholders ready to convert analysis into action, the full dataset and playbooks are available through our research portal.
For detailed analysis of this topic, please visit the official page: Train Seat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tracheostomy Market to Grow at 5.67% CAGR Through 2032
By pmarketresearch, 2026-07-22
Tracheostomy Market — 2026 Strategic Outlook and Executive Introduction
The tracheostomy devices market is at a tactical inflection point for 2026. PW Consulting’s newest study (base year 2025, forecast period 2026–2032) synthesizes primary research, regulatory documentation and proprietary financial modelling to give executives the forward-looking intelligence they need to shape product strategy, capital allocation and commercial execution. Our topline modelling shows continued expansion from a 2025 base to materially larger market scale by 2032, underpinned by a compound annual growth rate (CAGR) of 5.67% over the forecast window. This introduction explains the strategic value of the study for 2026 decision-making, highlights the practical deliverables inside the full report, and previews the competitive and regulatory dynamics shaping opportunities and risks.
Tracheostomy Market
Why this study matters for 2026 decision-makers
- Investor readiness: validates revenue run‑rate assumptions and stress-tests acquisition targets against scenario-driven demand and regulatory risk.
- R&D and portfolio prioritization: identifies where incremental technology investment (materials, cuff design, introducer systems) is likely to deliver outsized return on addressable demand.
- Commercial optimization: informs pricing, channel and tender strategies by mapping procedure shifts (ICU vs step‑down; percutaneous vs surgical) to product requirements and procurement cycles.
- Regulatory and quality planning: consolidates the evolving compliance landscape to reduce time‑to‑market and mitigate post‑market exposure.
- Supply‑chain resilience: flags single‑source inputs, sterilization capacity constraints and regional manufacturing dynamics to de‑risk supply interruptions.
What the full report delivers — practical, executable content
- Transparent market sizing and methodology: a reproducible approach with historical series (2020–2025), a 2026 baseline and scenario projections to 2032, including sensitivity levers for procedure volume, adoption curves and pricing.
- Demand-side segmentation framework: product and procedure archetypes mapped against buyer personas (acute care buyers, ambulatory surgery centers, long‑term care providers) and commercial pathways.
- Actionable competitor dossiers: verified profiles, technology footprints, regulatory history and near‑term development signals for incumbents and regional scale players.
- Regulatory & reimbursement compendium: consolidated citations (standards, 510(k) precedents, material guidance and coding implications) with implications for submission strategy and payer engagement.
- Supplier and manufacturing matrix: critical raw materials, sterilization routing, and low‑cost manufacturing pools with risk scores and mitigation playbooks.
- Tools for deal teams: valuation harmonics, integration checklists, post‑acquisition cost synergy templates and a prioritized M&A roadmap by strategic objective.
- Operational toolkits: go‑to‑market playbooks for product launches, tender responses, and hospital adoption campaigns, plus downloadable Excel models and dashboards for executive briefings.
Market dynamics and growth drivers
The market’s mid‑single digit CAGR reflects converging drivers and constraints. On the demand side, demographic shifts, higher survival rates from complex respiratory and neurological care, and expanding use of prolonged ventilation support in step‑down settings sustain baseline procedure volumes. Technology evolution — including more compliant cuff materials, introducer sets that simplify percutaneous procedures, and modular inner‑cannula designs — is creating new premium and differentiated product tiers.
Tracheostomy Market
At the same time, payer behavior and care‑setting migration (from in‑patient to ambulatory or home‑based care) are changing the commercial logic for device vendors. As providers seek lower total cost of care, purchasers increasingly evaluate lifecycle costs: sterilization needs, consumable frequency and procedure throughput. Firms that can demonstrate durable safety records, sterilization efficiency and clear reimbursement pathways will capture preferential access to high‑volume accounts.
Tracheostomy Market
Competitive landscape — implications for incumbents and challengers
The competitive map combines global medical device majors with specialized and regional manufacturers. Market concentration metrics indicate a fragmented market structure; the top three and top five players together do not dominate the sector, leaving space for differentiated entrants and consolidation by strategic buyers. Key strategic archetypes and implications include:
- Global platform leaders (e.g., large medtech OEMs) : These players compete on brand, broad clinical relationships and integrated respiratory portfolios. Recent regulatory clearances for next‑generation flexible tracheostomy tubes highlight continued investment in premium product lines. For buyers, partnering or licensing with platform leaders accelerates clinical adoption but commands premium valuation.
- Specialist OEMs and European innovators : Firms focused on cannula mechanics and materials engineering bring technical depth (twist, stability and dimensionally stable designs) attractive to procedural opinion leaders. They are logical M&A targets for companies seeking differentiated IP and regional distribution strength.
- Regional low‑cost manufacturers : Cost‑competitive producers in emerging markets sustain volume demand for basic disposable tubes and clean & care consumables. Strategic buyers must evaluate their quality systems and regulatory compliance history before scaling procurement or channel partnerships.
- Emerging challengers : Firms offering percutaneous introducer technology or improved cuff systems are shortening clinical learning curves and changing adoption dynamics; these are high‑value targets for integration into broader respiratory device portfolios.
Representative profiles included in the study (non‑exhaustive) cover leading OEMs and regional producers, summarizing headquarters, product specialties and recent regulatory or post‑market developments. Notable recent signals that we track in the report include new 510(k) clearances for flexible tube variants by a major OEM, and ongoing adverse event reporting for specific cannula designs that underscore the importance of post‑market surveillance and supplier audits.
Regulatory, reimbursement and material considerations to monitor in 2026
- Standards compliance: ISO guidance continues to dictate design and labelling expectations for tracheostomy tubes of standard internal diameters; compliance is a pre‑requisite for major markets and hospital procurement committees.
- Material evolution: manufacturers are moving to medical‑grade polymers and newer plasticizers to balance biocompatibility and manufacturability; sterilization modality (EO vs gamma) and packaging strategies materially affect unit costs and distribution logistics.
- Reimbursement dynamics: procedure and device reimbursement frameworks vary by market and code; while unit‑level and procedure reimbursements exist, the full revenue capture requires careful coding strategy and payer engagement, particularly for bundled care in respiratory and rehab pathways.
- Post‑market vigilance: MAUDE and equivalent systems are active sources of clinical signal; adverse event clusters can rapidly shift hospital purchasing behavior and generate regulatory scrutiny, with implications for stock availability and liability exposure.
Strategic playbook — six priority actions for 2026
- Re‑prioritize R&D to clinical pain points: focus on cuff reliability, introducer ergonomics and reusable/disposable cannula interfaces that reduce length of stay or dressing time.
- Lock in sterilization and raw‑material supply chains: secure dual sources for critical polymer grades and validated sterilization partners to avoid single‑point failure during demand spikes.
- Strengthen regulatory dossiers and surveillance: upgrade post‑market plans and complaint handling to shorten review cycles and reduce recall risk.
- Align commercial models with care migration: develop bundled offerings and subscription models for consumables that reflect outpatient and home‑care economics.
- Pursue targeted tuck‑ins: prioritize small, capability‑adding acquisitions (introducer tech, specialty cannulas) that accelerate clinical differentiation without large integration drag.
- Engage payers and hospital GPOs early: quantify total cost-of-care impact by device family to support favorable coding and inclusion on formularies and tender lists.
How PW Consulting’s study helps you act in 2026
This executive introduction signals the type of actionable intelligence contained in the full report: reproducible financials, scenario modelling, primary market interviews, regulatory timelines and a competitor matrix. For leadership teams making 2026 bets — whether launching a new tracheostomy line, structuring an acquisition, or tightening post‑market surveillance — the study translates market science into decision frameworks and executable workstreams.
To preserve the strategic value of the dataset, the full report retains detailed segment tables, regional demand breakdowns, and proprietary unit price modelling behind our client access portal. PW Consulting’s deliverables include the raw Excel models and a one‑page investment memo tailored to your strategic thesis.
Contact PW Consulting or visit our publications page to request the full Tracheostomy Market report and to schedule a briefing with our industry leads. The 2026 window favours organizations that move decisively on product differentiation, regulatory rigour and payer engagement — this study is designed to make those moves both informed and executable.
For detailed analysis of this topic, please visit the official page: Tracheostomy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com