

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: WiFi Thermostats Market to Reach USD 17.35M by 2032 at 21.07% CAGR

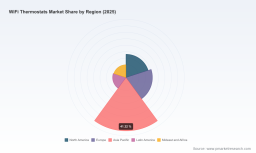
WiFi Thermostats Market — 2026 Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused executive preview of our WiFi Thermostats Market research — a tactical briefing designed to shape corporate decisions in 2026. This preview demonstrates the analytical depth and strategic framing contained in the full study while intentionally withholding the detailed segment tables and proprietary matrices that are accessible in the full report. Consider this a high-fidelity trailer: enough insight to inform priorities and immediate moves, but not the full playbook reserved for subscribers and clients.
WiFi Thermostats Market
High-level market trajectory you cannot ignore
The WiFi thermostats market has moved from a niche connected device into a mainstream energy-management platform. Our modeled time series shows a clear inflection: the market advanced from roughly USD 1.75 Million (revenue, Million USD) in 2020 to USD 4.55 Million in the 2025 base year, and is projected to expand at a compound annual growth rate of about 21.07% through our forecast horizon (2026–2032). By 2026 the market crosses an important adoption threshold and is projected to reach roughly USD 5.6 Million, ultimately approaching an estimated USD 17.35 Million by 2032 under the central scenario (all figures in USD Million).
WiFi Thermostats Market
Those dynamics tell a simple strategic truth for 2026: the addressable market is large enough and growing fast enough that incumbents and new entrants alike must prioritize product differentiation, channel optimization, and regulatory capture if they hope to defend or grow share.
WiFi Thermostats Market
What the full report delivers (practical, decision-ready content)
- Actionable market sizing and scenarios: Transparent modeling from 2020–2025 (historical) and a 2026–2032 forecast window with base-year calibration (2025). We deliver a central case plus conservative and upside scenarios to stress-test investment decisions.
- Growth-driver heatmaps: Detailed identification and quantification of demand levers — including smart-home interoperability standards, utility rebate programs, certification regimes, and consumer energy-savings economics — with sensitivity analysis for each lever.
- Regulatory and incentive map: A jurisdiction-by-jurisdiction guide to where certification and rebate rules materially change purchase economics and installation flows. It includes compliance checklists aligned to the major programs and regulations active through 2026.
- Go-to-market playbooks: Channel segmentation, pricing tactics, and distribution models for OEMs, retailers, utilities, and installers — plus scripts for utility partnership negotiations and retailer planograms optimized for 2026 promotions.
- Technology & product roadmap benchmarking: Comparative analysis of feature sets (connectivity standards, sensors, AI/learning, IAQ, video integration), integration risks, upgrade paths, and likely ASP trajectories under different hardware/software bundling strategies.
- Competitive intelligence & M&A scouting: Profiles of leading and fast-following vendors, market concentration metrics, and a short-list of acquisition/partnership targets ranked by strategic fit and integration complexity.
- Operational playbook for utilities and energy programs: Implementation guidance for rebate and enrollment programs that maximizes participation while reducing installation friction and fraud risk.
Competitive landscape: strategic implications (selected players)
The market’s competitive texture is best described as moderately concentrated. Our concentration metrics place the top three suppliers at roughly 45% CR3 and the top five at about 52% CR5 — enough heft for incumbents to set expectations, yet leaving meaningful room for challengers and niche specialists.
- Resideo Technologies, Inc. (Honeywell Home portfolio) — Resideo remains a primary incumbent with strong retail and channel reach. Recent product moves — including Matter-enabled models and the 2025/2025 launches of the X2S and the premium X8S (large touchscreen, integrated video/live doorbell stream, IAQ monitoring, and HVAC diagnostics) — reinforce a dual strategy: defend the mainstream by iterating connectivity and energy features while expanding into premium, integrated home hubs. For competitors, Resideo’s strategy raises the bar for cross-device integration and post-sale service expectations. For strategic buyers, Resideo’s activity signals where to expect consolidation pressure (software/hardware integration assets are high-value targets).
- ecobee Inc. — ecobee is differentiated by sensor technologies (including radar presence sensing) and air-quality monitoring across its Essential, Premium, and Enhanced lines. Their focus on consumer-facing measurement and direct-to-consumer channel optimization positions them as the prime threat in the premium/comfort-first segment. Strategic implication: companies optimizing for energy-savings partnerships must match or exceed ecobee’s environmental sensing to capture utility and health-conscious segments.
- Google (Nest) — Nest continues to leverage AI learning and broad platform integration (voice, cloud, matter). Google’s advantage lies in platform-level synergies and data-driven services. For incumbents and service providers, the defensive response must be either deeper platform partnerships or a clear migration strategy that preserves customer relationships independent of the large cloud ecosystems.
- Emerson Electric Co. (Sensi) — Emerson’s Sensi line is positioned toward reliable OEM-grade integrations and installer-friendly propositions. Emerson’s legacy in HVAC control positions it well for channel partnerships with HVAC contractors and commercial installers; corporate strategy here should focus on tightening installer workflows and pursuing managed-service contracts with commercial and multi-family customers.
Key regulatory and incentive drivers you need on your radar
- Certification regimes setting technical compliance floors and enabling market access: certain jurisdictions require occupant-controlled smart thermostats to meet specific certification standards to qualify for codes or rebates.
- Utility rebate programs materially change purchase economics: a number of incentive programs through 2026 offer cash incentives for ENERGY STAR-certified smart thermostats and tie eligibility to installation and registration workflows.
- These regulatory and rebate mechanisms are a double-edged sword: they accelerate adoption for compliant products but increase the compliance burden and create lock-in for vendors who can scale lifecycle support (registration, firmware updates, proof-of-installation).
Strategically, pre-certifying models for key rebate programs and designing installation-to-registration paths that minimize friction can unlock incremental demand without proportionate marketing spend.
How executives should use this study in 2026
- Product roadmap prioritization: Use the feature-valuation and willingness-to-pay matrices to sequence hardware upgrades vs. software services. Invest early in interoperability (Matter), IAQ sensing, and installer-oriented UX if targeting utility programs or enterprise channels.
- Channel & pricing decisions: Calibrate pricing bands against rebate capture and expected ASP evolution. Use the go-to-market playbooks to reallocate marketing spend toward program-enabled channels (utilities, retailers with rebate integrations, and pro-install networks).
- Regulatory capture & compliance budgeting: Treat certification and rebate-enabling investments as go-to-market capital. The report provides a timeline and jurisdictional priority list to focus compliance resources in 2026.
- M&A and partnership screening: Apply our fast-scan scoring to shortlist targets offering sensor IP, installation/registration platforms, or utility program management capabilities to accelerate market access.
- Utility and procurement negotiations: Use the operational playbook to design rebate structures that reduce fraud, increase beneficiary stickiness, and create data-sharing agreements that are privacy-compliant and monetizable.
Methodology, scope, and what’s intentionally withheld in this preview
The study synthesizes primary interviews with OEMs, channel partners, utilities, and installers; a product-level technology survey; and a bottoms-up revenue model calibrated to shipment proxies and average selling price trajectories. Historical coverage runs from 2020–2025 with 2025 as the base year and an explicit forecast window from 2026–2032. All revenue figures in this preview are stated in USD (revenue unit: Million). The central forecast assumes a 21.07% CAGR across the forecast window, with scenario variants provided in the full report.
To preserve the strategic value proposition of the full dataset, this preview does not disclose the detailed regional, price-tier, or end-use split tables, nor the proprietary market-share roll-ups that drive segment-level NPV models. The full report includes those tables, granular model access, workbook exports, and an annex of primary-source interviews and vendor product catalogs.
Final recommendation — immediate 90-day agenda for leadership
- Secure product certifications for the top three rebate programs in your priority market list and document the implementation timeline in Q2 2026.
- Run a four-week rapid audit of installer and self-install UX to eliminate registration friction that blocks rebate capture.
- Prioritize one tactical partnership with a utility or national retailer to test an incentivized bundle that includes installation and registration services.
- Initiate a focused M&A scan for sensor or registration-platform targets that can be integrated within 6–12 months to accelerate rebate-driven sales.
For teams preparing budgets, sales targets, or M&A pipelines in 2026, the choices you make in the next 90–180 days — around certification, channel integration, and product-defining features — will determine whether you capitalize on a market expanding from a few million in 2025 to a multi-fold larger market by 2032.
Access to the full PW Consulting WiFi Thermostats Market study will provide the segment-level datasets, tactical playbooks, and the vendor scorecards needed to act with precision. Visit our report page to download the complete report and the model workbook, or contact our advisory team for a one-on-one strategic briefing that maps the findings to your organization’s objectives.
For detailed analysis of this topic, please visit the official page: WiFi Thermostats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com