

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Computer Cart Market to Grow at 6.98% CAGR, Reaching USD 344.8M by 2032

Medical Computer Cart Market — Strategic Preview for 2026 Decision-Makers
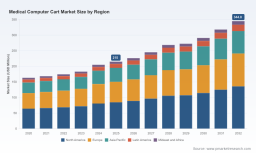
As health systems accelerate digital transformation and seek to improve point-of-care efficiency, medical computer carts have emerged as essential infrastructure for bedside documentation, medication administration, telehealth, and mobile diagnostics. PW Consulting’s latest study, with a 2025 base year and a forecast spanning 2026–2032, quantifies this momentum: the global market expanded from an estimated USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.98% into the forecast window, approaching roughly USD 345 Million by 2032. For executives planning purchases, product road maps, partnerships, or M&A activity in 2026, this report provides the actionable intelligence needed to convert macro momentum into competitive advantage.
Medical Computer Cart Market
Why This Study Matters for 2026 Strategic Decisions
-
Timing and scale: With consistent mid-single-digit CAGR and a clearly defined growth arc from post-pandemic stabilization into renewed capital cycles, providers and suppliers must align 2026 investments with the market’s second growth phase. Decisions made this year—on procurement cycles, product launches, or strategic alliances—will determine share capture as adoption broadens across care settings.
Medical Computer Cart Market -
Concentration and competitive dynamics: The market shows clear leader clustering (CR3 ~62.5%, CR5 ~78.3%), which creates both barriers and opportunities. Incumbents leverage scale, standards compliance, and integrated solutions; challengers can win by specializing in vertical niches, aftermarket services, or rapid innovation in power management and telehealth integration.
Medical Computer Cart Market -
Regulatory and reimbursement clarity: Baseline regulatory expectations—electrical safety standards (UL/EN/IEC 60601-1), quality systems (ISO 13485:2016, ISO 9001:2015), and FDA 510(k) routes when diagnostic or powered subsystems are integrated—are now well established. Reimbursement for carts typically falls under durable medical equipment constructs rather than new CPT/DRG carve-outs, meaning commercialization strategies must emphasize procurement economics and return-on-workflow rather than reliance on new billing codes.
Market Trajectory: The Numbers You Need (High-Level)
The headline figures are instructive: a clearly growing installed base and rising average unit sophistication. Between 2020 and 2025, the market experienced steady expansion driven by three vectors—digitization of bedside workflows, heightened infection control demands, and the rapid normalization of telehealth. Looking ahead, the projected CAGR of 6.98% signals continued healthy demand through 2032. These aggregated figures validate investments in modular, standards-compliant platforms and battery/power management innovations that extend uptime and support continuous point-of-care use.
Key Strategic Imperatives for 2026
-
Design for interoperability and standards compliance: Buyers prioritize carts that integrate cleanly with EHRs and medical devices and that meet UL/EN/IEC 60601-1 safety standards. Vendors without a robust compliance and documentation capability will face longer procurement cycles and credentialing friction in large health systems.
-
Differentiate on power and uptime: Battery management systems and fast-swap architectures are shifting from convenience features to procurement decision criteria. Carts that demonstrably reduce downtime, simplify charging logistics, and extend battery health will command pricing premiums and stronger procurement preference.
-
Embed infection prevention into product and service offers: Antimicrobial coatings, easy-to-disinfect surfaces, and service contracts that ensure ongoing sanitation are increasingly table stakes. These features are particularly persuasive in acute care purchasing committees and in systems prioritizing hospital-acquired infection reduction.
-
Service and lifecycle economics win RFPs: As reimbursement regimes do not create new revenue streams for carts themselves, procurement decisions are driven by total cost of ownership (TCO) and lifecycle service agreements. Vendors offering multi-year warranties, on-site maintenance, and remote monitoring of battery and usage analytics are best positioned.
-
Leverage telehealth as a differentiator: Integrated camera positioning, device mounting, and platforms optimized for remote consultations are now decisive features for carts used in virtual care workflows. Products that make telehealth a native capability—rather than an afterthought—unlock new buyer segments outside traditional inpatient procurement flows.
Competitive Landscape — Who to Watch
The market is a mix of established ergonomics and medical hardware companies, specialist cart manufacturers, and global electronics firms that have adapted industrial platforms for healthcare. Key players exemplify strategic approaches worth benchmarking:
-
Capsa Healthcare (Canal Winchester, Ohio): Known for integrated mobile computing workstations and telehealth platforms, their Trio series and updated Tryten telehealth cart demonstrate a strategy focused on point-of-care EHR access, medication management, and remote consultations—exactly the capabilities health systems prioritize today.
-
Ergotron (Eagan, Minnesota): Ergotron’s CareFit Slim and Mosaic product lines emphasize certified medical safety, ergonomic adjustability, and integrated power systems—attributes that play well in acute care and imaging environments where standards compliance and ergonomics influence adoption.
-
RDP Health (Burgess Hill, UK): With tailored workstations designed for NHS workflows (EPR, EPMA, and phlebotomy), RDP’s warranty and battery-indicator features illustrate how specialization for public health systems can create defensible procurement wins.
-
Lund Industries / DataCart (Northbrook, Illinois): Their focus on customization, antimicrobial coatings, and multi-year warranties shows the commercial value of integrating infection control and long-term service into the core proposition.
-
Advantech (Taiwan / US operations): Advantech’s AMiS series blends industrial-grade electronics with hospital-grade usability for medication administration and telehealth, highlighting the growing role of systems-level integrations from electronics OEMs.
-
Parity Medical (Bromborough, UK): UK-designed and assembled workstations illustrate how localized manufacturing and regulatory alignment can shorten procurement lead times for national health systems.
Recent industry moves underline these thematic dynamics: an FDA listing in mid-2024 for a new advanced cart; product upgrades that embed battery management systems; and renewed trade-show activity through early 2025. These events collectively reflect the industry’s emphasis on safety, uptime, and telehealth readiness.
Regulation, Reimbursement, and Certification — Operational Realities
-
Regulatory pathways: Integrating powered subsystems or diagnostic accessories typically triggers 510(k) obligations in the U.S. Vendors must factor regulatory timelines into time-to-market and product road maps.
-
Certification expectations: Buyers expect ISO 13485:2016 and ISO 9001:2015 quality systems as baseline credentials. Demonstrable adherence reduces purchase friction and supports rapid deployment within health systems’ supplier vetting processes.
-
Reimbursement context: As carts are generally managed under durable medical equipment frameworks without special CPT/DRG treatment, commercial strategies should rationalize pricing against workflow gains and TCO reductions rather than anticipated incremental reimbursement.
What the Full Report Contains (Practical, Executable Content)
PW Consulting’s full market study goes beyond descriptive analysis to provide operational tools and decision frameworks that procurement, product and corporate development teams can use immediately:
-
Market-sizing and scenario models calibrated to 2020–2025 history and iterated through 2026–2032 forecasts, enabling rapid sensitivity testing of adoption, price, and technology scenarios.
-
Go-to-market playbooks for vendors segmented by buyer persona (large integrated delivery networks, specialty clinics, ambulatory surgical centers) with procurement triggers and procurement committee levers mapped to product features.
-
Competitive benchmarking templates and capability matrices covering certification, battery tech, telehealth integration, warranty, and aftermarket service—designed to support RFP responses and M&A diligence.
-
Supply-chain and manufacturing risk heat maps, highlighting lead-time exposures, component concentration risks, and compliance bottlenecks that affect commercial continuity in 2026 and beyond.
-
Commercial models and TCO calculators to quantify buyer ROI for integrated battery systems, antimicrobial finishes, and managed service contracts—tools that help sellers justify price premiums in procurement negotiations.
-
Regulatory timelines and checklist templates for 510(k) submissions and CE/IEC conformity, enabling product teams to embed compliance milestones into development sprints and launch plans.
Note: this preview intentionally omits granular regional and application split data and other protected segmentation tables that are included in the full study. Those detailed breakdowns are critical for tactical decisions—such as exact market prioritization by country or specific product mix optimization—and are accessible in the full report.
How to Use These Insights in 2026
-
For vendors: Prioritize product investments that reduce buyer TCO and demonstrate compliance. Differentiate with service bundles and analytics that convert carts into managed assets rather than one-off capital purchases.
-
For health systems: Use the TCO framework to shift procurement criteria from lowest unit cost to lifecycle value, particularly when evaluating battery systems, warranties, and end-to-end telehealth enablement.
-
For investors and M&A teams: Target assets that fill capability gaps (battery management, telehealth integration, aftermarket services) and consider roll-up strategies to consolidate service-intensive niches where higher margins and stickiness reside.
Conclusion — From Momentum to Market Leadership
The medical computer cart market is no longer a peripheral accessories segment; it is an enabler of digital clinical workflows and virtual care. With an established growth trajectory and clear leader concentration, 2026 is the inflection point for turning product and commercial bets into sustained market presence. PW Consulting’s full study equips decision-makers with both the high-level market architecture and the practical tools—models, benchmarks, and templates—needed to translate the macro growth story into winning strategies. For teams that require the segmentation granularity, regional and application breakdowns, and downloadable decision-support tools, the full report provides the proprietary data and executable analyses that close the gap between insight and action.
To access the complete intelligence suite and the proprietary datasets that underpin our forecasts and playbooks, please consult the full Medical Computer Cart Market report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Medical Computer Cart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com