

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dairy Packaging Market to Reach USD 33.17B by 2032; 4.89% CAGR

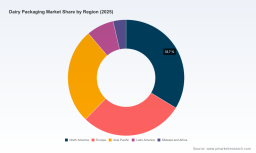
Dairy Packaging Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented introduction to our full Dairy Packaging Market study. This preview synthesizes macro trajectory, regulatory shocks, technology inflection points, and competitive dynamics that will matter to executives planning through 2026 and beyond. It demonstrates the analytical depth you can expect from the full report while intentionally withholding the detailed subsegment datasets and commercial tables reserved for subscribers.
Dairy Packaging Market
Market Trajectory: Scale, Momentum, and What It Means
The dairy packaging market has been resilient through 2020–2025, expanding from approximately USD 18.5 billion in 2020 to USD 23.7 billion in 2025 (base year). Our forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of roughly 4.89%, projecting a market size north of USD 33 billion by 2032. These macro figures underline two strategic truths for 2026 planning:
Dairy Packaging Market
- Growth is steady, not meteoric. Companies should prioritize margin capture and portfolio optimization over pure-volume bets.
- Incremental innovation—material substitutions, aseptic processing efficiencies, and packaging format redesign—will be the primary drivers of share shifts rather than market expansion alone.
The market concentration metrics further sharpen the competitive lens: the top three and top five suppliers together account for a relatively modest share of global revenue (CR3 ≈ 28.5%; CR5 ≈ 35.2%), signifying a moderately fragmented ecosystem. For large multinational suppliers this means scale advantages can be leveraged, but specialty and regional players retain clear niches and acquisition appeal.
Dairy Packaging Market
Dynamics Shaping Strategic Choices in 2026
Three intersecting dynamics will disproportionately influence commercial outcomes next year:
- Regulation and producer responsibility — Since 2025, regulatory action on recycled-content mandates and producer responsibility schemes has accelerated. Notable examples include state-level mandates that phase in minimum post-consumer recycled content requirements and national/regional packaging laws that set binding recycled-content targets with clear enforcement timelines. These rules are reshaping upstream resin demand, qualification cycles for recycled feedstocks, and the economics of mono-material vs. multi-layer barriers.
- Sustainability-driven material change — Suppliers and brand owners are rapidly trialing paper-based barriers, bio-attributed polymers, and recycled-content plastics. Aseptic paper barrier solutions and alu-free carton architectures are moving from pilot to early commercial deployment, enabled by equipment upgrades and barrier technology advances.
- Operational resilience and supply-chain volatility — Resin price swings, feedstock availability for PCR (post-consumer recycled) materials, and capacity constraints for aseptic filling lines are creating premium returns for integrated suppliers who can guarantee material specifications and on-time delivery.
These dynamics translate into concrete near-term pressure points: capital allocation to retrofit or replace filling lines, tighter technical and contractual specifications for recycled resins, and an acceleration of supplier consolidations and cross-sector partnerships.
Competitive Landscape: Who’s Shaping the Agenda
The market features a blend of legacy carton specialists, flexible-packaging innovators, resin producers, and converters. Key players we profile in the report include global carton-system leaders, flexible-packaging multinationals, and resin suppliers that are rapidly moving downstream through partnerships and product attribution programs.
- Tetra Pak (Pully, Switzerland) — Continued leadership in aseptic carton systems, with investments to scale paper-based barrier solutions into higher-speed filling lines.
- SIG Combibloc Group (Neuhausen, Switzerland) — Active in aluminum-free, full-barrier aseptic cartons and early commercial rollouts across European and emerging markets.
- Elopak (Oslo, Norway) — Expanding sustainable carton capacity in North America and emphasizing gable-top formats for both dairy and plant-based beverages.
- Amcor, Berry Global, Huhtamaki — Large converters leaning into flexible films, bottles, and paperboard trays while balancing recycled content mandates and functional barrier needs.
- SABIC, INEOS Styrolution — Resin suppliers active in bio-attributed and recycled polymer streams; their feedstock strategies and certification capabilities are becoming strategic assets for converters and brand owners.
- Specialists like ProAmpac, Winpak, Alfipa — High-performance flexible solutions, butter wraps, PET bottles and closures remain critical to category differentiation and SKU-level economics.
Recent developments exemplify the competitive themes above: the first commercial deployments of alu‑free aseptic cartons in Europe, paper-based barrier cartons scaled to high-speed lines in Asia, new regional sustainable-production capacity in the United States, and launches using recycled-content polystyrene in retail channels. These moves reflect suppliers converting R&D into commercial propositions that directly address 2026 regulatory and customer requirements.
What the Full Report Delivers (Practical, Transaction‑Ready Tools)
Our comprehensive study goes beyond high-level narrative to provide the operational intelligence that procurement, R&D, and corporate strategy teams need to act in 2026. Highlights include:
- Scenario models that stress-test volume, price, and raw-material assumptions under alternative regulatory timelines and feedstock availability.
- Supplier scorecards that evaluate technical capability, sustainability credentials, geographic reach, and capital intensity—designed for rapid sourcing decisions and RFP shortlists.
- Investment playbooks for plant retrofits and packaging-line upgrades, including CAPEX/OPEX trade-offs and payback sensitivity across material alternatives.
- Commercial levers and SKU rationalization frameworks for SKU-level margin recovery, substitution strategies, and cost-to-serve optimization.
- Policy-impact matrices that translate pending and enacted regulations into action steps for product design, labeling, and reporting obligations.
Note: while the full report includes granular breakdowns across material types, packaging formats, and regional markets, this preview intentionally omits those subsegment tables and datasets to preserve our subscribers’ competitive advantage.
Strategic Imperatives for 2026
For executives mapping capital, procurement, and M&A decisions in 2026, five priorities emerge:
- Define a materials roadmap — Establish a 3–5 year plan for recycled and alternative-material adoption that aligns R&D, procurement, and customer commitments. Prioritize certification pathways for recycled feedstocks and bio-attributed resins early in the adoption curve.
- Flex capital toward modularity — Invest in modular filling and converting equipment that supports multiple formats (aseptic cartons, spouted pouches, bottle sizes). Flexibility reduces obsolescence risk amid shifting consumer and regulatory requirements.
- Secure feedstock through partnerships — Long-term offtakes, joint ventures with resin producers, and investments in PCR sorting/processing reduce exposure to volatile spot markets and ensure compliance with recycled-content mandates.
- Use procurement as a competitive weapon — Move beyond price-only sourcing: specify circularity clauses, supply continuity SLAs, and joint innovation KPIs in contracts with converters and resin suppliers.
- Target bolt-on M&A and strategic partnerships — Fragmentation and emerging material technologies create opportunities to acquire niche capabilities (e.g., barrier coatings, aseptic filling retrofits, or regional converter footprints) at attractive valuations.
Scenarios and Risks — What Could Upset the Base Case
Our base-case projection (CAGR ~4.89%) assumes phased regulatory implementation and steady adoption of sustainable materials. Upside risks include faster-than-expected consumer adoption of long-life aseptic formats and a rapid scaling of affordable recycled feedstocks. Downside risks are centered on supply-chain disruptions, unexpected regulatory stringency that raises compliance costs, and technological setbacks in barrier technologies that impede substitution of incumbent plastics.
Preparing for volatility means stress-testing supply agreements, building inventory and dual-sourcing where feasible, and investing in rapid qualification pipelines for new materials.
How to Use This Preview
Consider this document a roadmap to the decision points your executive team will face in 2026. Use it to frame board-level debates, prioritize capital requests, and align cross-functional owners around a coordinated materials and procurement strategy. For teams preparing bids, tender responses, or plant investment proposals, the full PW Consulting report supplies the datasets, supplier rankings, and scenario models required to substantiate recommendations and secure approvals.
Next Steps
PW Consulting’s full Dairy Packaging Market report contains the proprietary subsegment tables, regional and application splits, and transaction-grade supplier profiles that underpin the strategic insights summarized here. To access the complete dataset, interactive dashboards, and our team’s advisory services (including scenario workshops and supplier selection support), please visit the PW Consulting report page.
In a market defined by steady growth, rising regulatory pressure, and rapid material innovation, 2026 will reward companies that convert strategic clarity into operational readiness. This preview maps the landscape—our full analysis provides the tactical instruments to win within it.
For detailed analysis of this topic, please visit the official page: Dairy Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com