

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Solar Encapsulation Market to Reach USD 9.95 Billion by 2032 at 7.83% CAGR

Solar Encapsulation Materials Market: Strategic Imperatives for 2026 Decision‑Makers
Market snapshot — why 2026 is a strategic inflection point
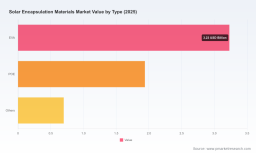
The solar encapsulation materials market is in clear expansion mode. Our baseline assessment (base year 2025) values the global market at approximately USD 5.87 Billion and projects steady expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 7.83%, reaching an expected market size near USD 9.95 Billion by 2032. These headline figures understate important structural shifts: technology-driven demand for higher-performance films, rising qualification and warranty requirements for next‑generation modules, and an increasingly strategic approach to supply‑chain localization are re-shaping supplier economics and buyer priorities.
Solar Encapsulation Materials Market
What this report delivers — an action-oriented playbook (high level)
PW Consulting’s Solar Encapsulation Materials Market study is designed as an operational intelligence product for executives making capex, procurement, product development, and M&A decisions in 2026. The study blends a granular data backbone with strategic narratives and executable frameworks, including:
Solar Encapsulation Materials Market
- Market sizing and seven‑year forecasts by material class and module architecture (historical 2020–2025 baseline + 2026–2032 outlook).
- Technology deep dives covering polymer chemistries, co‑extrusion architectures, and key performance metrics (moisture ingress, PID resistance, UV stability, and gel content expectations for commercial qualification).
- Supplier landscape and scorecards evaluating capacity, IP position, quality systems, and route‑to‑market competence.
- Procurement playbooks — scenario‑based sourcing strategies, dual‑sourcing templates, and cost‑to‑serve models suited to module manufacturer profiles.
- Risk and regulatory matrix — warranty exposure analysis, regional trade and localization pressures, and regulatory tests that materially affect LCOE and bankability.
- Opportunity maps for technology partnerships, licensing, and targeted capacity expansion projects that balance speed, cost, and qualification risk.
Market dynamics reshaping supplier and buyer strategies
Several overlapping dynamics are accelerating demand and reframing margins across the value chain:
Solar Encapsulation Materials Market
- Module architecture transition: The move to bifacial, TOPCon and other high‑efficiency cell technologies is driving buyers to specify encapsulants with improved PID resistance and enhanced moisture barriers. These functional requirements are increasingly codified in module qualification protocols and in warranty commitments that module manufacturers must meet.
- Material innovation and product differentiation: Co‑extruded films, POE variants optimized for TOPCon, UV‑stabilized formulations and perovskite‑compatible encapsulants are becoming commercial imperatives for players targeting premium module segments. Incremental efficiency and reliability gains can translate to meaningful price premiums for premium films — buyers must balance the cost‑benefit across module BOM (bill of materials) and lifetime energy yield.
- Supply‑chain localization and geopolitical considerations: Strategic moves to establish production footholds closer to major module assembly centers — including North America and Southeast Asia — are reducing qualification timelines and mitigating import exposure. Domestic facility expansions and near‑market capacity are increasingly factored into procurement scorecards.
- Consolidation and market concentration: The market structure exhibits significant concentration, with leading suppliers commanding a meaningful share of global supply. This concentration creates both risk (single‑source dependencies) and opportunity (partnerships, co‑development, and premium pricing) for module makers and downstream buyers.
- Cost‑performance tradeoffs and warranty economics: Encapsulant selection is no longer a component decision in isolation. It feeds into warranty risk, bankability, and LCOE calculations. Higher upfront material cost can be justified when the incremental performance reduces degradation and warranty reserves over a 25‑year contractual horizon.
Competitive lens — who matters and how they are positioning
The competitive map is a mix of global chemical majors, specialized polymer houses, and regionally focused film producers. Our assessment highlights a set of companies that are shaping product roadmaps, capacity footprints, and qualification dynamics:
- Hangzhou First PV Material Co., Ltd. — positioned as a global leader in EVA and POE films, with commercialized co‑extruded solutions tailored to high‑efficiency module formats.
- Jiangsu Sveck New Material Co., Ltd. and Zhejiang Sinopont Technology Co., Ltd. — regional champions focusing on co‑extrusion and TOPCon‑compatible POE developments to capture growth in fast‑expanding module assembly hubs.
- Shanghai HIUV New Materials and Changzhou Betterial Film Technologies — technology‑centric players prioritizing UV resistance, long‑term stabilization chemistries, and solutions for tandem/perovskite architectures.
- Major chemical conglomerates (3M, Dow, DuPont, Mitsui Chemicals, Eastman) — offer breadth of material platforms and the global qualification reach that multinational module makers require.
- Regional suppliers in India and other emerging markets (RenewSys, Alishan Green Energy) — rapidly scaling capacity and introducing specialized fast‑cure and UV‑functional products to serve local OEMs with shortened supply chains.
These supplier trajectories are reflected in recent commercial activity: facility expansions in North America, capacity scale‑ups in South and Southeast Asia, and commercial launches of high‑barrier co‑extruded films and perovskite encapsulation solutions. Such moves accelerate qualification cycles for buyers but also create windows for strategic sourcing and co‑development.
Strategic implications for 2026 decisions — what executives must act on now
For corporate leaders — procurement heads, product R&D chiefs, and strategy teams — the window to position for 2026 outcomes is narrow. The following implications should frame boardroom deliberations:
- Revisit encapsulant selection as a system design choice. Procurement checklists must expand beyond unit price and delivery to include demonstrated PID resistance, moisture ingress performance, and third‑party qualification track records aligned with 25‑year warranty regimes.
- Prioritize dual‑track sourcing for premium segments. Maintain relationships with global majors for consistency and qualification leverage, while piloting regional specialized suppliers to reduce lead times and improve cost flexibility.
- Accelerate technical validation cycles. Invest in accelerated aging labs or co‑funded qualification programs with suppliers to compress the time from material selection to module certification.
- Embed market scenarios into supply‑chain capital decisions. Use scenario modeling — reflecting adoption rates of bifacial and TOPCon modules — to size internal inventory buffers, negotiate long‑term take‑or‑pay terms, and plan capex for back‑integrated film lamination capacity where justified.
- Be alert to premium pricing dynamics. Certain high‑performance films command price premiums tied to measurable module efficiency and warranty outcomes; quantify those tradeoffs in LCOE and financing models rather than treating them as line‑item costs.
- Evaluate M&A and strategic alliance opportunities. For firms seeking rapid capability buildup, acquiring or partnering with specialized film producers can shortcut multi‑year R&D and qualification timelines.
Practical next steps — a 90‑day playbook for 2026 planning
For teams tasked with implementing the strategic pivots above, we recommend a focused 90‑day agenda:
- Week 1–4: Conduct a supplier risk audit, mapping single‑source exposure, qualification timelines, and geopolitical risk vectors.
- Week 5–8: Run a technical gap analysis comparing existing module warranties and degradation assumptions against supplier performance data and new film chemistries.
- Week 9–12: Launch one pilot co‑development program (e.g., POE/TOPCon or perovskite encapsulation) with a shortlist of suppliers and establish success metrics tied to qualification milestones and cost targets.
Why PW Consulting’s study matters for 2026
This report is purpose‑built to inform decisions that materially affect capital allocation, product roadmaps, and supply‑chain risk in 2026. We combine transparent, auditable market sizing (2020–2025 historical series and 2026–2032 forecast), supplier benchmarking, and hands‑on playbooks that translate analysis into executable initiatives. The goal is not simply to describe market trends but to enable governance bodies and operating teams to act with speed and confidence.
Final note — what we intentionally withhold (and why)
This overview demonstrates the analysis depth and practical orientation of our full study while preserving the proprietary segmentation tables, supplier scorecards, and granular regional/application splits that deliver the operational value for which PW Consulting is engaged. If your 2026 strategy requires detailed material‑by‑application demand curves, supplier capacity maps, or price‑elasticity grids, those datasets — along with scenario models and downloadable financial templates — are available in the complete report and accompanying client portal.
Call to action
For executive briefings, customised supplier benchmarking, or access to the full dataset and scenario models, contact PW Consulting to schedule a tailored walkthrough. The decisions you make in 2026 about encapsulant strategy will reverberate across product reliability, warranty outcomes, and cost of energy for the next decade — make them with calibrated insight.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com