

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrical Steels Market to Reach USD 39.65 Billion by 2032 at 5.82% CAGR

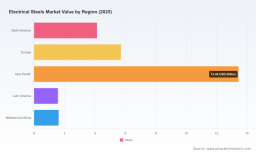
Electrical Steels Market 2026: Strategic Imperatives from PW Consulting’s Industry Study
As PW Consulting’s lead industry analyst, I present a succinct strategic preview of our comprehensive Electrical Steels Market study (base year 2025, forecast period 2026–2032). This briefing is purposefully structured as a “trailer”: it surfaces the analysis, signals the decision levers executives must act on in 2026, and deliberately withholds granular split tables and line-by-line segment forecasts to drive the next step — a download or briefing of the full report.
Electrical Steels Market
Executive snapshot
The global electrical steels market is entering a multi-year growth phase as electrification and grid modernization converge with industrial demand. On the macro scale, total industry revenues rose to USD 26.5 Billion in 2025 and, under our base forecast, expand at a compound annual growth rate (CAGR) of roughly 5.8% through 2032 to reach just under USD 40 Billion. That topline trajectory masks a complex interaction of technology substitution, regional supply chain reconfiguration, trade measures and input cost volatility — all active forces shaping 2026 strategic choices.
Electrical Steels Market
Why this matters for 2026 decisions
- Timing of investments: With sustained mid-single-digit CAGR, incremental capacity and product-line investments made in 2026 will capture demand across multiple cycles through the end of the decade.
- Policy and trade sensitivity: Regulatory shifts and trade actions are no longer peripheral risks; they are determinative of margin and access to markets. Firms must bake policy scenarios into capital allocation models.
- Product & customer segmentation: Demand drivers for core product families (low-loss grades for grid applications vs. hyper-thin grades for electric mobility) require different technology roadmaps and go-to-market approaches.
Core themes executives must prioritize
1. Supply-side reconfiguration and localization
2025–2026 saw renewed activity in plant investments and capacity realignment. Leading global producers are expanding or relocating capability closer to strategic end-markets to serve electrification and reduce import exposure. For decision-makers, the key question in 2026 is not whether to localize, but where and at what scale. Capital deployment needs to be selective: target hubs with stable policy regimes, predictable input access, and proximity to anchor customers such as EV OEMs and large utilities.
Electrical Steels Market
2. Product differentiation: loss, thickness and coating
Electrical steels are competing on finely tuned technical attributes: core loss for transformer steels, lamination thickness and magnetic permeability for motor steels, and surface/coating systems for manufacturability. Our analysis shows that premiumization of certain grades (driven by EV traction motor efficiency and smart-grid needs) will justify price premiums for producers who can sustain consistent quality and reliable supply. R&D and quality control budgets should be viewed as strategic enablers, not overhead.
3. Regulatory regimes reshape competitive advantage
Beginning in 2026 regulators have introduced market mechanisms and trade remedies that materially affect cost competitiveness for import-reliant buyers and exporters. Carbon-related mechanisms and updated benchmark rules for upstream processes change the calculus on whether raw material substitution, supplier requalification, or vertical integration is preferred. For corporate strategy this translates into dual actions: (a) align sourcing strategies to lower-carbon, compliant suppliers; and (b) stress-test pricing models under a range of carbon and tariff scenarios.
4. Input volatility and risk management
Ferrosilicon and other specialty alloy inputs experienced notable price swings in 2025, and volatility remains a realistic base case for 2026. Procurement strategies must therefore combine physical hedging, multi-sourcing, and supplier partnership models that include inventory smoothing and cost passthrough provisions. Firms that lock in supply and quality at competitive terms will outperform peers during cyclical input spikes.
5. Consolidation & cooperation pathways
Market concentration metrics indicate space for both scale players and specialized niche producers. For acquirers and investors, 2026 is a tactical window: consolidation can secure route-to-market advantages and technical capabilities, while targeted joint ventures allow faster access to regional demand without full greenfield exposure. Where regulatory constraints limit M&A, strategic alliances on coating technologies, thin-gauge processing, or recycling can yield similar benefits with lower political friction.
Competitive landscape — who matters and why
The competitive set comprises global integrated steelmakers and specialized electrical-steel producers. Several groups stand out as strategic benchmarks and potential partners or competitors in 2026 decisions:
- Global flat-rolled leaders that have pivoted to low-carbon processes and are scaling non-grain-oriented product lines to serve traction motor demand.
- Large integrated producers with advanced grain-oriented grades optimized for power transformers and renewable grid infrastructure.
- Regional specialists and engineering-driven firms that supply industrial motors and niche transformer applications, often leveraging tight customer relationships and service capabilities.
Across this set, companies that combine strong metallurgy know-how with supply-chain agility and regulatory alignment will be best positioned to capture the forecast growth.
Recent market signals to monitor in 2026
- Greenfield and retrofit investments in key producing regions that aim to shorten supply chains for high-value grades.
- Policy actions affecting import flows and carbon compliance obligations for steelmakers and buyers.
- Ongoing trade remedies and anti-dumping/anti-subsidy proceedings that can rapidly re-map supplier economics.
- Raw material price spikes and logistical interruptions that compress margins for unhedged producers.
Actionable recommendations for leadership teams (2026 planning cycle)
- Adopt scenario-based capital allocation: Build three capex scenarios (conservative, base, aggressive) tied to regulatory and trade outcomes. Prioritize modular plant designs and flexible lines that can shift between core grades.
- Reassess sourcing with carbon compliance as a core filter: Update approved vendor lists and include carbon-intensity KPIs. Negotiate long-term offtakes with paired decarbonization clauses.
- Product roadmap triage: Allocate R&D effort to two paths — performance optimization for EV traction motors and loss-minimization for utility transformers — while protecting intellectual property through joint development agreements where capital is constrained.
- Hedge input exposure smartly: Combine financial hedges for key alloy inputs with operational levers (safety stocks, upstream partnerships, alternative alloy trials) to dampen price shocks.
- Prepare tariff- and carbon-compliant pricing frameworks: Implement dynamic pricing models that can transparently pass through verified carbon or duty-related cost changes to customers.
- Refine M&A and partnership playbooks: Target bolt-on acquisitions that add technical capability or market access rather than scale alone. Use JV structures in politically sensitive markets to limit regulatory pushback.
- Invest in market intelligence and rapid response: Set up a dedicated monitoring cell to track material regulatory changes, trade investigations and competitor investments in real time.
How PW Consulting’s full report supports 2026 execution
Our complete Electrical Steels Market study goes beyond high-level themes to deliver practical decision tools for 2026 and beyond, including:
- Scenario-modeled demand forecasts across the forecast horizon (2026–2032) with sensitivity to regulatory and trade outcomes.
- Strategic capex calculators for greenfield vs. retrofit investments that incorporate carbon-compliance cost assumptions and break-even timelines.
- Supplier and region risk heatmaps tied to raw material exposure, logistical complexity and policy risk indices.
- Competitor profiles and playbooks summarizing technological strengths, likely strategic moves, and potential partnership fit for each major producer.
- Commercial tools: pricing templates that integrate pass-through mechanics for carbon and duty layers, and customer segmentation guides for OEMs and utilities.
Concluding perspective
The electrical steels market in 2026 is not just growing — it is re-sorting. Growth is meaningful at the macro level, but the enduring value will accrue to companies that converge capability in three dimensions: metallurgical excellence, supply-chain resilience, and regulatory foresight. Executives who embed flexible investment frameworks, carbon-aware sourcing, and disciplined product prioritization into their 2026 plans will convert mid-single-digit CAGR into above-market returns.
Next steps — where to get the full intelligence
This preview intentionally omits the granular regional, product and application splits that underlie our revenue and margin forecasts. Those line-level datasets, supported by proprietary supplier mappings and capex models, are available in the full PW Consulting Electrical Steels Market report and accompanying analyst briefings. To schedule a tailored executive briefing or to access the detailed tables and scenario models that will inform precise 2026 capital and commercial plays, contact PW Consulting through our website or request the report download.
Our team stands ready to translate the study’s findings into a bespoke action plan aligned to your firm’s risk tolerance, market exposure and growth ambitions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Electrical Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com