

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Construction Estimating Software Market at USD 1,768M in 2025, set for 11% CAGR
By pmarketresearch, 2026-07-22
Construction Estimating Software Market: Strategic Primer for 2026 Decision-Makers
Market snapshot — why this matters now
The construction estimating software market has moved from a niche productivity toolset to an operational backbone for preconstruction and bid-to-build workflows. Our analysis uses 2025 as the base year and traces historical performance from 2020–2025, then provides a forward-looking forecast through 2032. In broad strokes, the market expanded from just over USD 1.1 billion in 2020 to roughly USD 1.77 billion by 2025, and is forecast to approach the mid-single-digit billions by the end of the 2026–2032 forecast window. That trajectory represents a robust compound annual growth rate (CAGR) of about 11% across the forecast period — a growth profile that elevates estimating platforms from cost-center applications to strategic investments that materially affect bid win rates, margin protection, and project throughput.
Construction Estimating Software Market
Why our 2026 research is strategically valuable
- Timing: 2026 is a pivot year in which cloud-native deployment, embedded AI, and compliance requirements converge. Buyers and investors who act on data this year lock in architecture and partner choices that will shape multi-year TCO and integration pathways.
- Decision focus: The report is designed to inform three executive decisions typical in 2026: platform selection (including migration vs. rip-and-replace timing), supplier due diligence (security and data governance), and product road-mapping (AI automation and API-first strategies).
- Risk mitigation: Given rising regulatory scrutiny and the elevated cost of data breaches, our brief emphasizes controls and contractual design that reduce enterprise exposure while preserving estimator productivity.
What the full PW Consulting report delivers (practical, operational outputs)
We structured the research to be immediately operational for procurement, IT, and preconstruction leaders. Highlights include:
Construction Estimating Software Market
- Decision matrices that map vendor capability to buyer archetype (from regional subcontractors to enterprise general contractors), allowing you to prioritize feature trade-offs under different procurement constraints.
- Integration playbooks detailing realistic timelines and resource estimates for migrating legacy on-premise estimating systems to cloud or hybrid architectures, including change management checkpoints.
- AI adoption scorecards and use-case prioritization—identifying where automated takeoff, symbol recognition, and assembly assistants yield outsized ROI versus where human oversight must remain.
- Security and compliance checklists tuned for construction estimating workflows, including required audit artifacts for SOC 2 Type II readiness and GDPR/CCPA obligations.
- Vendor due-diligence templates, including sample RFP language, SLA expectations for accuracy and uptime, and IP/data exit clauses for contract closeouts.
Competitive landscape — positioning and strategic moves (what to watch)
The market remains neither fully consolidated nor entirely fragmented: the top three vendors control a meaningful share but a long tail of specialist players continues to capture vertical and regional niches. This structure creates both acquisition opportunities for platform leaders and tactical wins for nimble specialists.
Construction Estimating Software Market
- Bluebeam — Known for Revu’s high-precision digital plan review and collaboration capabilites. Its core strength is accuracy in takeoff workflows and a strong reputation among estimators who prioritize plan markup and review fidelity.
- Sage Software — With deep legacy strength in cost databases and multi-estimator collaboration, Sage’s offering is tailored to organizations that require enterprise-grade estimating databases and robust bid-staging workflows.
- Trimble — Focused on mechanical/electrical estimating with pre-populated databases and change-management workflows, Trimble’s suite targets trade-specific complexities where domain content is a competitive differentiator.
- PlanSwift & OnCenter — These specialists continue to deliver focused takeoff performance improvements and are often chosen by teams that need speed and workflow simplicity without broad ERP ties.
- ConstructConnect, Procore, Autodesk — These platforms are racing to combine cloud estimating with upstream project data (BIM, bid discovery, and project lifecycle management). Recent feature launches demonstrate a push toward seamless takeoff-to-proposal flows and tighter plan overlays.
- Buildxact, STACK, UDA Technologies — Newer entrants and growth-stage players are investing heavily in AI assistants, automated assemblies, and residential-contractor workflows. Their momentum is built on faster onboarding and purpose-built automation.
Notable 2026 product activity underlines these competitive dynamics: UDA introduced a centralized Bid Tracking module in January 2026, Buildxact pushed an enhanced AI assistant in May 2026, and Procore rolled out advances in direct takeoff data flow and auto-count that same month. These moves illustrate two concurrent trends: (1) incumbents cementing platform breadth, and (2) specialists accelerating feature-led differentiation through AI.
Dynamics shaping vendor selection and adoption
- AI and labor dynamics: AI-assisted takeoff and symbol recognition are game-changers for repetitive work. In repeatable residential workflows, automated tools can reduce manual takeoff hours substantially; firms must therefore redesign charge-out models and re-skill estimator teams to capture value rather than lose labor utility.
- Cloud vs. on-premise calculus: Cloud deployments accelerate collaboration and updates but introduce new compliance and exit challenges. Enterprise buyers should evaluate encryption, audit logging, and contractual data portability as core procurement criteria.
- Regulatory and security pressures: SOC 2 Type II, GDPR/CCPA alignment, and audit-readiness are no longer optional for enterprise-grade estimating systems. Organizations should budget for third-party compliance costs and design security gates into vendor selection—Sprinto’s market benchmarking shows that SOC 2/GDPR readiness has a quantifiable implementation cost range that firms must plan for.
- Cost and concentration risk: Market concentration indicates there are meaningful platform leaders but also room for high-value niche offerings. Procurement teams should consider the trade-offs between single-vendor integration simplicity and multi-vendor best-of-breed agility.
Strategic implications and recommended actions for 2026
Executives should treat estimating platform decisions as strategic, not tactical. The following playbook is designed for action in 2026:
- Short-term (0–6 months): Run a targeted pilot of AI-assisted takeoff on a spectrum of project types (residential, commercial shell, MEP). Use the pilot to quantify estimator productivity improvements and error-rate reductions. At the same time, perform a focused SOC 2 readiness assessment for any cloud vendors under consideration.
- Medium-term (6–18 months): Decide on the architectural approach—lift-and-shift to cloud modules versus deep integration with an enterprise project management stack. Negotiate contracts with explicit data portability and breach-cost sharing clauses. Begin phased migrations for high-volume, low-complexity bid types to capture immediate ROI.
- Long-term (18+ months): Institutionalize an estimation center of excellence that blends AI oversight, estimator upskilling, and a continuous model-validation process. For firms with diversified trade work, design a hybrid sourcing model that uses best-of-breed trade solutions where domain content matters and unified platforms for cross-trade visibility.
How to use this research in your 2026 planning cycle
Our full report combines market sizing, competitive benchmarking, and operational playbooks. Use it to:
- Align procurement and IT on a single vendor evaluation scorecard;
- Formulate capital allocation scenarios reflecting faster estimation cycles and potential headcount realignment;
- Create a compliance roadmap with cost and artifact milestones tied to SOC 2 and data-protection requirements;
- Build integration timelines that protect bid accuracy during transition windows.
Final note — the limits of this primer
This introduction surfaces the strategic questions and directional answers senior leaders need to act in 2026. The full PW Consulting market research provides the granular decision support — detailed vendor matrices, scenario-based financial models, and implementation templates — that procurement and preconstruction teams require to operationalize these recommendations. To preserve actionable differentiation for paying subscribers, core segment-level breakdowns and contract-level benchmarking are available in the complete report.
For a guided briefing tailored to your business model — procurement, enterprise IT, or preconstruction leadership — contact the PW Consulting insights team to schedule a strategy session and receive the full workbook and vendor playbooks.
For detailed analysis of this topic, please visit the official page: Construction Estimating Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polyurea Coatings Market Set for 6.33% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-22
Polyurea Coatings Market: Strategic Outlook for 2026 — An Executive Briefing
As senior strategists at PW Consulting, we present a focused executive briefing designed to orient executive teams, corporate development groups, and procurement leaders as they finalize strategic plans for 2026. This briefing synthesizes our market model—built on a 2025 base year with historical analysis from 2020–2025 and a 2026–2032 forecast horizon—into the practical implications that will determine winners and losers in the polyurea coatings value chain.
Polyurea Coatings Market
Market snapshot: growth trajectory and structural signals
The polyurea coatings market is no longer a narrow specialty niche. Our model shows a steady expansion from the early-2020s into the mid-decade, with the global market rising sharply through 2025 and projecting to more than double by the end of the forecast horizon. The compound annual growth rate embedded in our base scenario is 6.33% for 2026–2032, reflecting a combination of ongoing infrastructure investment, demand for high-durability waterproofing and protective systems, and increasing adoption in transportation and industrial end‑uses.
Polyurea Coatings Market
Two structural signals are particularly important for 2026 planning:
Polyurea Coatings Market
- Demand is broadening in both traditional end-markets (infrastructure, industrial containment, transportation) and emerging niches (blast mitigation, hardened shelters, specialty flooring), creating multiple entry and expansion pathways.
- Market concentration is meaningful—our concentration metrics indicate that the top three and top five suppliers hold a majority of market influence—implying that scale, channel access, and specification control matter when competing on price, performance, or service.
Why this study matters for 2026 decisions
Companies finalizing budgets, capex, or M&A strategies in 2026 face three parallel uncertainties: the pace of infrastructure programs post-pandemic, raw-material cost volatility (notably isocyanates and amine resins), and accelerating regulatory pressure on product sustainability. Our research converts those uncertainties into actionable choices by combining a robust quantitative market model with qualitative supplier and project-level intelligence.
- For commercial leaders: the study translates growth trajectories into addressable revenue bands by application and channel—enabling prioritization of sales resources and specification campaigns without overcommitting to low-margin segments.
- For operations and supply chain: our scenario analysis quantifies the impact of raw-material cost shocks and capacity squeezes on margin and fulfilment risk, offering concrete hedging and inventory strategies timed to 2026 procurement cycles.
- For corporate development: the concentration profile and technology segmentation in the study highlight acquisition targets that deliver either complementary formulations, regional distribution, or manufacturing scale.
Drivers, constraints and regulatory backdrop
The market dynamics are a mixture of product-led performance advantages and external pressures:
- Performance-led adoption: Polyurea’s rapid cure, extreme abrasion resistance, and long service life continue to drive specification as a lifecycle-cost preferred solution for waterproofing, containment, and protective coatings.
- Sustainability and regulation: polyurea’s 100% solids, low- or no-VOC formulation profile is increasingly attractive to clients operating under stricter environmental requirements. Major chemical suppliers are investing in low-VOC and longer-durability platforms to stay ahead of regulation-driven procurement policies.
- Supply-side risk: volatility in isocyanate and amine resin markets is a high-probability, high-impact risk. Raw‑material price movement and intermittent capacity constraints can compress margins and force regional price differentiation unless proactively managed.
Competitive landscape — strategic implications from supplier behavior
The competitive map is shaped by a mix of specialty formulators, integrated chemical majors, and regional systems houses. Below we summarize the strategic positioning we observed among the leading players in the market and why their moves matter for counterpart strategies in 2026.
- ArmorThane USA Inc. — A systems-focused player with a strong reputation in blast mitigation and hardened shelter programs. Recent contract wins across multiple countries underscore their strength in program-level solutions and government channels. For competitors, ArmorThane’s playbook illustrates the value of coupling technical certification with program delivery capability.
- Huntsman Corporation — Continues to push polymer performance through product innovation (notably intumescent-enhanced polyurea technologies). Huntsman’s launch cadence demonstrates the advantage of R&D-led differentiation in raising barriers for commodity pricing.
- BASF SE — Positioned as an integrated supplier leveraging broader resin and chemistry platforms, with targeted capacity investments to support regional demand. BASF’s moves highlight the upside for players that can provide both formulation expertise and secure supply of intermediate chemistries.
- Covestro AG and Sika AG — Covestro brings upstream feedstock and formulation depth targeted at automotive and large industrial systems, while Sika operates as a market-facing formulator with strong liquid-applied membrane credentials. Both companies illustrate alternative routes to market: raw-material integration versus channel-first product systems.
- Chemline Inc., Specialty Products Inc., and Polymer Nation — These firms exemplify the varied specialist niches: bespoke large-volume industrial coatings, spray-applied systems for protective infrastructure, and decorative/chemical-resistant flooring, respectively. Their agility is a reminder that nimble, application-focused players can defend margins even in concentrated markets.
Recent corporate activity—capacity expansions at major resin sites, product launches improving polymer performance, and contract awards in defense and infrastructure—indicates that incumbents are simultaneously locking in supply, upgrading product performance, and pursuing program-level contracts. These are defensive and offensive plays that influence where new entrants should focus their limited investment capital.
What the full report contains (practical, decision-ready assets)
Our full Polyurea Coatings Market study is structured to be operational from day one. Highlights include:
- Proprietary market model (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario variants that stress raw-material shocks, accelerated regulation, and substitution risk.
- Supplier scorecards and capability heatmaps—assessed across formulation depth, geographic footprint, channel strength, and program delivery capability—designed to support supplier selection and partnership screening.
- Commercial playbooks for three go-to-market archetypes: systems integrator (program sales), formulators (B2B raw-material customers), and regional installers (service-led differentiation).
- Procurement and cost-to-serve templates, including a raw-material pass‑through sensitivity tool and recommended hedge parameters for 12–24 month procurement cycles.
- M&A screening matrix and valuations framework calibrated to the market’s current concentration profile to identify targets that will move the needle on scale, specification ownership, or channel access.
- Implementation checklists: technical specification bundling, RFx templates tailored for polyurea systems, and site-assessment protocols to reduce warranty exposure and optimize TCO messaging.
We intentionally omit granular segmented tables and line-item model outputs from this briefing to preserve the strategic value of the full study. That granular intelligence—application-level demand curves, regional demand splits, and vendor share estimates—is available in the complete report through our research portal.
Actionable recommendations for 2026
For executives preparing 2026 plans, we recommend a three‑pronged approach:
- Secure upstream continuity: Lock in multi-year supply agreements or strategic partnerships with resin suppliers, and build inventory buffers that are sized by our scenario stress tests. Price war games in our model show that early contracting mitigates margin erosion during sudden raw-material spikes.
- Differentiate on specification and total cost of ownership: Invest selectively in R&D or co-development arrangements that reduce cure times, improve intumescent or fire-resistance properties, or extend warranty periods. These features command premium pricing in infrastructure and specialized industrial applications.
- Follow modular expansion over blunt capex: Rather than broad capacity build-outs, prioritize modular capacity additions or toll-manufacturing arrangements in target geographies to match demand elasticity and avoid stranded assets.
How to use this briefing — and what to expect next
Treat this briefing as the strategic north star for immediate decisions entering 2026: it frames where to allocate limited capex, which supplier relationships to prioritize, and how to position product offerings in a market that rewards both scale and specification-led differentiation. For teams preparing investment decks, procurement tenders, or M&A teasers, the full dataset and supplier heatmaps in the complete report will provide the defensible evidence required by boards and investment committees.
PW Consulting’s full Polyurea Coatings Market report contains the detailed segmentation, project-level deal intelligence, and downloadable model templates that substantiate the recommendations summarized here. We have deliberately withheld proprietary segmentation tables and vendor share sheets from this summary to preserve the report’s commercial value and to encourage a fact-driven evaluation—available through our research portal.
Closing note
2026 will be a year when the market’s structural trends—sustainability regulation, infrastructure demand, supply security, and product innovation—create outsized opportunities for firms that combine technical depth with disciplined commercial execution. Use this briefing to align leadership on the key trade-offs; consult the full PW Consulting study for the granular, executable intelligence you need to convert strategy into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Polyurea Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cochlear Implants Market to Reach USD 1,850M in 2025, 7.5% CAGR Forecast
By pmarketresearch, 2026-07-22
Cochlear Implants Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a concise strategic briefing that frames the Cochlear Implants market through the lens of near-term investment, commercialization and policy decisions for 2026. This piece synthesizes our proprietary research and market modelling (base year 2025) to surface the critical inflection points executives, investors, payers and health-system leaders must confront. The narrative deliberately signals the depth and operational utility of the full report while reserving granular segment-level datapoints to encourage direct engagement with our full study.
Cochlear Implants Market
Why this briefing matters in 2026
The cochlear implants market is transitioning from a technology-driven clinical niche into a strategic healthcare category with expanding indications, differentiated product roadmaps and rising payer scrutiny. Our market model (USD, Million) shows robust mid-single-digit to high-single-digit growth—a 7.5% CAGR across the forecast period—with total market value expanding materially from the 2025 base. That trajectory, combined with concentrated vendor dynamics and evolving regulatory decisions in 2024–2025, creates time-sensitive windows for first-mover product strategies, partnership alignments and pricing renegotiations.
Cochlear Implants Market
For executives who must justify capital allocation in 2026, the question is no longer “Is this a growth market?” but “Where within this ecosystem will portfolio investments deliver superior risk-adjusted returns?” The answers rest on commercial agility, regulatory foresight and bespoke evidence-generation—areas where our full report provides operational playbooks.
Cochlear Implants Market
What the PW Consulting study delivers (practical, transaction-oriented)
- Market sizing and forward-looking revenue model (base year 2025, forecast 2026–2032) with scenario analysis under alternative adoption, reimbursement and competitive disruption assumptions.
- Go-to-market playbooks for OEMs and disruptive entrants: product roadmap prioritization, channel economics, hospital contracting strategies and aftermarket service models (including firmware and software monetization tactics).
- Regulatory and reimbursement decision matrices that map clinical evidence needs to coverage outcomes, including pathways for pediatric expansions, adult candidacy changes and device-agnostic CPT/DRG positioning.
- Commercial benchmarking and margin levers: pricing elasticity, service bundle optimization and hospital reimbursement capture strategies tailored to diverse health-system payment architectures.
- M&A and partnership diagnostics: value capture frameworks for bolt-on acquisitions, strategic alliances with audiology networks and JV structures for market access in large public procurement environments.
- Risk register and mitigation playbook covering supply-chain resilience, regulatory delays, pricing pressure from volume-procurement programs, and technology obsolescence risk related to software-driven implants.
These practical modules are designed to be immediately actionable by commercial, clinical and strategy teams. The executive summary and implementation appendix distill the recommendations into prioritized initiatives with estimated impact and resource requirements.
Market dynamics snapshot — size, growth and concentration
Our aggregated market model places the global cochlear implants market on a pronounced growth path. Using 2025 as the analytical anchor, the model forecasts sustained expansion through 2032, underpinned by expanding clinical indications, incremental device feature sets (notably connected implants and firmware-upgrade capability), and an aging population in several large healthcare markets.
From a competitive structure standpoint, the market remains moderately concentrated. The three largest vendors account for a majority share of revenues, and the top five vendors command a dominant presence—conditions that favor incumbents in distribution, clinical relationships and long-term service contracts, while simultaneously presenting openings for focused challengers to win on niche clinical use-cases, technology differentiators or procurement-stage entry strategies.
Two structural trends are particularly relevant for 2026 planning:
- Device-as-platform economics: The emergence of implants that support firmware updates and connected services changes the revenue logic from one-off device sales to recurring software-enabled services and upgrades.
- Procurement consolidation and price pressure: Large public procurement programs and value-based contracting in major markets are reshaping pricing expectations and increasing the importance of lifecycle cost arguments (implant longevity, revision rates, and remote programming capabilities).
Competitive landscape — what leaders are doing
Our competitive analysis profiles the major commercial actors and translates their recent moves into strategic implications:
- Cochlear Limited (Sydney): Continues to invest in platform functionality with the launch of a smart cochlear implant system that supports firmware upgrades. The strategic emphasis appears to be on defending installed base economics and creating recurring revenue streams via software and services. For competitors, this raises the bar for aftermarket differentiation and patient lifecycle monetization.
- MED-EL (Innsbruck): Recent regulatory wins expanding pediatric candidacy widen the clinical addressable market and heighten competitive intensity in early intervention care pathways. Payers and clinicians will increasingly evaluate evidence on developmental outcomes and long-term cost offsets; manufacturers will need robust pediatric outcome registries to capture future adoption.
- Advanced Bionics (Sonova subsidiary, USA): Selection into a major government volume-procurement program in China underscores a critical go-to-market axis—strategic public procurement can rapidly alter national market shares. Firms targeting growth in high-volume, price-sensitive markets must architect margin-preserving strategies such as localized manufacturing, tiered feature sets, and bundled services.
Together, these moves illustrate divergent strategies: platform and aftermarket expansion, clinical-indication growth, and procurement-driven scale plays. Each has distinct implications for how competitors allocate R&D, clinical evidence funding, and commercial investments in 2026.
Regulatory and reimbursement context
The financing and coding environment remains foundational to commercial outcomes. Key dynamics to incorporate into 2026 planning include:
- Coding stability: The primary CPT code for cochlear device implantation remains unchanged through 2025, preserving established billing pathways for clinical providers.
- Coverage consistency: Major public payors continue to provide coverage under existing national policies in key markets; however, the emergence of value-based procurement models in some jurisdictions increases the need to demonstrate cost-effectiveness and real-world outcomes.
- Procurement programs: Government-led volume procurement in certain large markets has already influenced vendor selection and pricing expectations—this is a structural consideration for manufacturers pursuing scale in emerging and price-sensitive geographies.
Anticipating regulatory and payer shifts should be a near-term priority; the firms that align clinical-evidence generation with procurement timelines and payer requirements will secure preferential access and more predictable revenue streams.
Strategic actions for 2026 — decision frameworks
Based on our analysis, we recommend a set of prioritized actions for different stakeholders. Each recommendation is grounded in quantified scenario outcomes and operational levers detailed in the full report.
- For OEMs and device innovators:
- Invest in platform features that enable post-implant software delivery and remote care; monetize maintenance and upgrades where regulators permit.
- Allocate resources to pediatric outcomes studies and registry development to de-risk payer coverage for expanding indications.
- Pursue selective local manufacturing or contract manufacturing partnerships in markets where procurement programs reward domestic supply or low-cost sourcing.
- For hospital systems and clinical networks:
- Negotiate bundled contracts that align implant acquisition with lifetime services (rehabilitation, mapping, tele-audiology), capturing value from post-operative care.
- Standardize outcome measures and data capture to participate in value-based arrangements and to support negotiations with payers and device suppliers.
- For investors and private equity:
- Prioritize assets with recurring revenue potential (software, services) or with expedited access to pediatric/expanded indications; scrutinize margin sustainability in procurement-exposed markets.
- Target tuck-in acquisitions that enhance aftermarket capabilities or local market presence rather than large-scale platform wagers where incumbents enjoy scale advantage.
- For payers and policy makers:
- Design coverage frameworks that emphasize long-term outcomes and total cost of care; incentivize devices and care models that reduce revision rates and enable remote follow-up.
How PW Consulting constructed the insights
Our findings derive from a multi-method research program combining: primary interviews with clinical KOLs, hospital procurement leads and OEM strategy executives; analysis of public regulatory filings and procurement databases; a bottoms-up product and channel cost model; and scenario-based forecasting under alternative adoption and reimbursement assumptions. We stress-tested our projections against conservative and aggressive uptake cases, and the full report includes sensitivity matrices for quick executive use.
To preserve competitive value in this public briefing, we have deliberately withheld segment-level revenue breakdowns and granular regional/application percentages. Those detailed matrices, supplier-by-supplier revenue analytics, and implementable negotiation scripts are available in the full report and the companion data workbook.
Next steps — where to focus first
Leaders preparing 2026 budgets should begin by stress-testing three near-term hypotheses: (1) the commercial impact of software-enabled implants on recurring revenue and service economics; (2) the degree to which pediatric indication expansion accelerates demand in prioritized markets; and (3) exposure to procurement-driven price compression in high-volume jurisdictions. Our full analysis quantifies each of these and provides prioritized initiatives with estimated timelines and resource needs.
PW Consulting’s full Cochlear Implants Market report (base year 2025, forecast to 2032) contains the granular, actionable intelligence required to convert these hypotheses into executable programs. For executives ready to turn strategy into operational plans, our proprietary datasets and implementation templates will accelerate decision cycles and reduce execution risk.
To access the complete study, data workbook and tailored advisory engagements, please follow the link on our website or contact PW Consulting’s Healthcare Strategy team for a briefing tailored to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Cochlear Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Composite Insulators Market to Hit USD 344.8M by 2032 (6.98% CAGR)
By pmarketresearch, 2026-07-22
Composite Insulators Market — Strategic Briefing for 2026 Decision-Makers
Why this briefing matters for 2026
As utilities and electrical-equipment OEMs navigate replacement cycles, grid electrification, and regulatory updates, composite insulators have moved from niche to mainstream in high-voltage asset strategies. Our latest market model shows the global composite insulators market emerging from early-decade volatility to a clear expansion phase: the market reached roughly USD 215 million in 2025 and, under our baseline, is expected to expand at a compound annual growth rate of approximately 6.98% through the 2026–2032 forecast horizon. For boards, procurement leads, and strategy teams planning 2026 capital and MRO budgets, the implications are immediate — choices made this year about supplier footprints, certification roadmaps, and raw-material contracting will materially condition cost, lead time, and risk through the next multi-year upgrade cycle.
Composite Insulators Market
Snapshot: what the macro picture tells us
- Resilient growth trajectory: After modest year-to-year fluctuations in the early 2020s, demand momentum reasserted itself by 2024–2025, setting a platform for steady expansion into 2032. Management teams should treat this as a multi-year volume opportunity rather than a short-lived spike.
- Fragmented competitive landscape: Market concentration is low — the top three and top five players together account for less than a third of market revenue — which creates both opportunities for consolidation and risks of margin pressure from regional low-cost producers.
- Market entry and scale economics: Scale benefits accrue in pultrusion capacity, quality control, and IP-protected assembly techniques; however, regional logistics and certification demands mean local or nearshore production continues to be a relevant strategic lever.
Market dynamics that will shape supplier selection and capex in 2026
- Raw-material sensitivity: Pultrusion economics are tightly coupled to glass-fiber and resin pricing. As a practical benchmark, pultruded fiberglass profiles trade in broad ranges (dependent on resin grade and customization) and manufacturers’ margins can compress rapidly when resin or fiber prices spike. Procurement teams should test supplier cost models against ±20–30% raw-material shocks and seek indexed contracts or dual-sourcing strategies to preserve margin and availability.
- Standards and certification: The 2025 refresh of IEC 61109 (Edition 3.0) and the release of EN IEC 62217:2025 raise minimum sheath and interface quality requirements — effectively shortening certification lead times for incumbents who have already invested in controlled manufacturing and test protocols. For buyers, certification status will increasingly be a differentiator that shortens qualification cycles; for suppliers, the standards create an entry barrier that rewards capital investment in testing infrastructure.
- Technology and materials evolution: Improvements in silicone formulations and HTV injection techniques are enabling longer service life and simplified assembly. Suppliers announcing higher-consistency silicone grades and improved core-to-sheath bonding are not only improving product reliability but also reducing lifecycle O&M costs — a compelling value proposition for asset owners seeking TCO reductions.
Competitive landscape: positioning, playbooks, and likely moves
The market combines specialty European OEMs with vertically integrated production, high-volume Asian manufacturers, and a number of regional producers focused on distribution networks. Several archetypes are visible:
Composite Insulators Market
- Specialist European innovators: Firms with full-process integration and advanced material know-how present premium, high-reliability offers to HV OEMs and utilities. Their competitive advantage lies in validated production technologies, proprietary material handling, and proximity to stringent certification regimes.
- High-volume Chinese manufacturers: A dense supplier base offers modular product ranges and competitive pricing for wide deployment in emerging and domestic markets. These players excel in scale manufacturing and rapid order fulfilment but sometimes face longer qualification cycles in regulated Western markets.
- Indian exporters and regional specialists: Producers that can manufacture up to high-voltage classes and export at competitive rates are a durable force in markets where price and availability dominate purchasing decisions.
Illustrative company insights (select):
Composite Insulators Market
- SAVER S.p.A. (Italy): Vertical integration and a focus on hollow composite insulators position them well for HV OEM partnerships where process control and certification matter. Their model reduces supplier coordination risk for buyers needing turnkey, certified components.
- Power Composites / Reinhausen technology (Germany): Known for advanced epoxy-resin glass-fiber cylinders and HTV-injection techniques; technology transfers and asset sales in late 2025 signal potential consolidation and capacity relocation — a trend to watch for implications on European supply and IP ownership.
- SH POWER, Hebei manufacturers, and other Asian players: Broad product portfolios, export orientation, and participation at major trade shows underscore sustained competitiveness on price and speed-to-market. Buyers should weigh qualification timelines against cost benefits.
- Shemar USA and regional specialists: Regional presence combined with focused product lines enable faster certification cycles and stronger aftermarket service agreements — valuable for utilities prioritizing reliability over lowest-cost bids.
Recent moves that matter for 2026 strategy
- Mid-2025 and year-end activity saw strategic IP and asset reallocation: an advisory-led acquisition and production-asset transfer announced in late 2025 marks active consolidation and creates potential capacity shifts in Europe beginning in 2026. Companies evaluating sourcing strategies should simulate availability and lead-time changes from such capacity moves.
- Materials suppliers are upgrading product portfolios — a leading silicone producer unveiled new high-consistency formulations in mid-2025 — strengthening suppliers who can integrate these materials into certified processes.
- Trade show participation in early 2026 continued to reflect market vitality: manufacturers showcased higher-voltage designs and service propositions, accelerating buyer engagement and shortening proof-of-concept cycles for qualified suppliers.
Actionable implications for 2026 planning
- Procurement and inventory: Lock in strategic raw-material indexation clauses or multi-year supply contracts for resin/fiber to stabilize unit economics. Where possible, create a two-tier sourcing strategy (certified premium suppliers + qualified regional second-source) to balance reliability and cost.
- Certification and supplier qualification: Prioritize suppliers with current conformity to the 2025 standard updates; the time and cost to qualify new vendors into IEC 61109/EN IEC 62217-compliant supply chains can materially delay projects.
- CapEx and footprint decisions: If you are evaluating own-manufacturing or nearshoring, model expected demand growth versus breakeven pultrusion capacity utilization — high fixed costs mean outsized benefits only at scale or when combined with adjacent product lines.
- M&A and partnership playbook: Given low market concentration, 2026–2028 is a window for bolt-on acquisitions that deliver immediate scale, certification assets, or IP. Prioritize targets with validated testing records, pultrusion capability, and clean compliance histories.
- Product strategy: Emphasize lifecycle cost and service (e.g., long warranties, on-site diagnostics, standardized replacement kits) rather than competing solely on unit price. Utilities are increasingly receptive to TCO-based procurement frameworks.
- Risk and scenario planning: Stress-test supplier networks against raw-material spikes, regional tariff disruptions, and certification bottlenecks. Build contingency agreements with qualified alternative producers before project start dates.
What the full PW Consulting report contains (practical deliverables)
Our complete market study—designed as an operational playbook for 2026—includes the following deliverables:
- Validated market-sizing and seven-year forecasting models with scenario toggles for raw-material price stress and regional demand shifts;
- Supplier scorecards and qualification checklists that map technical capability, certification status, lead time, and geopolitical exposure;
- Cost-to-serve and pultrusion breakeven analyses that support make-vs-buy decisions and footprint planning;
- Regulatory readiness roadmap tied to IEC/EN updates and recommended investment sequencing to shorten qualification timelines;
- M&A diligence templates focused on IP assessment, test-lab capability, and capacity integration; and
- Procurement negotiation playbooks (indexing clauses, KPI-backed SLAs, and inventory buffers) tailored for the composite insulator supply chain.
How to use this briefing in boardroom planning
For CEOs, the key decision is whether to treat composite insulators as a strategic component (necessitating investment in supply security and certification) or as a tactical commoditized buy. For procurement and plant managers, the near-term emphasis should be on securing raw-material exposure mitigation and accelerating supplier qualification under the 2025 standards. For corporate development teams, the fragmented market and recent asset transfers reveal acquisition targets that can be rapidly integrated to obtain scale and testing capability.
Next steps
This executive briefing is a gateway: it highlights the essential directional signals and operational levers for 2026 decision-making. The full PW Consulting Composite Insulators Market report contains the granular segmentation, supplier-level benchmarking, and excel-based models you need to convert insight into executable strategy. Reach out to our team to request the complete dataset, model access, and a tailored workshop to convert the findings into your 2026 procurement and investment roadmap.
For detailed analysis of this topic, please visit the official page: Composite Insulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Astronomical Telescope Market to Reach USD 730.94M by 2032 at 7.15% CAGR
By pmarketresearch, 2026-07-22
Astronomical Telescope Market — Strategic Outlook for 2026 Decision-Makers
Introduction: Why 2026 Is a Pivotal Year
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, actionable briefing on the Astronomical Telescope market that frames the strategic choices companies must make in 2026. Our new market study synthesizes five years of historical performance (2020–2025) with a multi-scenario forecast through 2032. The market has expanded materially from the early-2020s and is projected to continue growing at a compound annual growth rate (CAGR) of approximately 7.15% across the 2026–2032 forecast window. Such momentum—paired with rapid product innovation, shifts in consumer behavior, and evolving standards—creates a narrow window for decisive action. This briefing highlights the strategic value of our full study for executives preparing budgets, R&D roadmaps, partnerships, and M&A agendas in 2026.
Astronomical Telescope Market
Market Snapshot (what the numbers are telling us)
By the close of our base year, 2025, the global astronomical telescope market reached a notable scale, and our baseline projection places 2026 above that base—continuing toward a materially larger market by 2032. This trajectory reflects durable end-market demand from hobbyists, educational institutions, and research entities, and importantly it is being reshaped by two converging forces: product intelligence (smart telescopes and app ecosystems) and sustained demand for optical performance across a spectrum of price points.
Astronomical Telescope Market
Competitive concentration remains low-to-moderate, indicating a fragmented supply base with multiple specialist brands retaining distinct niches. That structure supports both continued innovation and opportunistic consolidation—each representing different strategic pathways for incumbents and new entrants.
Astronomical Telescope Market
How this study informs 2026 corporate decisions
- Portfolio prioritization: Decide whether to accelerate investments in smart, app-integrated telescopes, double down on premium optical lines, or expand value-tier offerings for mass-market adoption.
- R&D and product roadmaps: Align optics, mount systems, and software roadmaps with adjacent trends in imaging sensors and user experience to maximize product relevance in three-year horizons.
- Supply-chain and cost strategies: Rebalance sourcing and vertical integration decisions to mitigate volatility in specialized optical components and precision labor costs.
- Channel and go-to-market: Reconfigure distribution and after-sales models for a world where app platforms, direct-to-consumer sales, and education partnerships coexist.
- M&A and partnership screening: Identify targets that add immediate capability (e.g., smart telescope platforms, sensor partnerships, or regional manufacturing footprints) and estimate accretive thresholds under multiple scenarios.
- Regulatory & standards preparedness: Anticipate ISO and other standardization shifts that affect product claims, test methods, and export documentation—and incorporate these into product certification timelines.
What the full report delivers (practical, actionable content)
- Proprietary market-sizing and forecasting model with transparent assumptions and scenario toggles for demand shocks, technology adoption rates, and price deflation.
- Segment-level demand drivers and margin archetypes (by product architecture and customer cohort), with risk-adjusted uptake curves that support budget planning.
- Go-to-market playbooks: channel economics, bundling strategies (hardware + subscription software), and education & outreach blueprints tailored to institutional buyers.
- Supplier and cost-risk matrix: mapping of specialized optical component suppliers, critical labor nodes, and mitigation levers for procurement teams.
- Competitor dossiers and comparative capability maps that benchmark product families, technology bets, and route-to-customer strengths.
- M&A screening and valuation templates calibrated to this market’s growth profile and competitive dynamics.
- Executive dashboards and downloadable financial models for scenario testing during board-level strategy sessions.
Note: The full report contains granular regional, type and application splits, detailed financials, and company scorecards. In keeping with this briefing’s role as a strategic trailer, those granular tables are reserved for the full report and subscriber portal.
Competitive Landscape — who is shaping the market and how
The market structure is characterized by specialists pursuing differentiated technology and user experiences. Several players are particularly influential in shaping 2026 competitive choices:
- Celestron (Torrance, CA): Continues to couple computerized mounts (NexStar line) and high-performance Schmidt-Cassegrain optics (EdgeHD) with integrated solutions such as the Origin intelligent home observatory. Celestron’s breadth—augmented by product updates—favours market-leading reach into both hobbyist imaging and entry-level smart observatory segments.
- Synta Technology / Celestron OEM relationship (Taiwan): Remains an important industrial engine behind production scalability for advanced mounts and mainstream optics. Its role underscores how OEM partnerships influence time-to-market and cost position.
- Sky-Watcher (Taichung City): Balances performance optics (Esprit ED refractors, Skymax Maksutov lines) and respected mounts, targeting committed amateur astrophotographers who trade up as their interest deepens.
- Takahashi & Astro-Physics (Japan / USA): Represent the high-end optical tier, investing in fluorite apochromats and premium astrographs. These companies anchor the premium segment where optical excellence and brand reputation support higher margins.
- Explore Scientific & Vixen: Offer diversified portfolios—Dobsonians, refractors, eyepieces and mounts—appealing across visual and imaging use cases. Explore Scientific’s recent Sidara mount series highlights the ongoing investment in usability for serious amateurs.
- Bosma & Apertura: Drive affordability and volume in value tiers, keeping overall market growth accessible while pressuring margins at entry-level price points.
- Vaonis & ZWO Seestar: Signal the shift to “smart telescopes” with app-first imaging experiences and integrated sensor systems—an area of rapid consumer adoption that redefines the value chain.
Recent product launches across vendors during 2025–2026 are accelerating the shift toward hybrid propositions—optics + intelligence + service—that lower the technical barrier to deep-sky imaging while creating recurring revenue opportunities through software and cloud services.
Key dynamics and risk factors
- Standards & regulation: ISO/TC 172/SC 4 standardization work continues to refine terminology, test methods and requirements for direct-view optical systems; manufacturers should anticipate stricter conformance checks and plan certification timelines (next sessions scheduled in late 2026).
- Cost-pressure from specialized inputs: Precision optical components and skilled manufacturing labor keep unit costs elevated for premium segments; firms with better engineering-to-cost control will protect margins.
- Infrastructure constraints for ground-based installations: Dark-sky site availability and stable mounting systems increase total installation costs for higher-end ground installations—an important consideration for institutional buyers and specialized OEMs.
- Consumer behavior shift: Rapid adoption of smart, app-integrated telescopes reduces friction for newcomers and creates new monetization models—subscription services, image-processing toolchains, and educational content bundles.
- Public interest & macro tailwinds: Renewed public enthusiasm for space and astronomy campaigns (media, missions, education initiatives) sustains interest across hobbyist and institutional cohorts.
Strategic playbook for 2026 — prioritized moves
- For premium optics firms: Protect IP in optical formulation, expand limited-series high-margin SKUs, and monetize service and calibration packages for serious astrophotographers.
- For scale OEMs & mid-tier manufacturers: Invest in software partnerships and modular mounts that enable multiple customer journeys—visual observing, imaging, and automated remote operation.
- For value-oriented brands: Focus on improving perceived quality (bundled accessories, learning content) to reduce churn and capture first-time buyers who can migrate upmarket.
- For distributors and retailers: Reconfigure SKUs and training offerings to support demo-heavy selling and remote onboarding—key to converting interest into higher-ticket sales.
- For investors and M&A teams: Target capabilities that accelerate software and smart-hardware convergence, aftermarket service providers, and regional manufacturing capacity that de-risks lead times.
Why PW Consulting’s study is the go-to tool for 2026 planning
Our report combines rigorous top-down and bottom-up sizing, vendor-level intelligence, and a scenario-ready forecasting engine calibrated to observable adoption curves. It delivers tactical playbooks alongside strategic scenarios, enabling commercial, R&D, and corporate development teams to stress-test investment choices under realistic market evolutions. Critically, we package the work with downloadable financial models and an executive dashboard designed for board-level decision-making.
To preserve the utility of this briefing as a strategic film-trailer, we have intentionally withheld the full regional, type and application-level breakdowns, and the detailed company scorecards that drive our valuation and M&A guidance. Those tables, along with the workbook you can use to test your own assumptions, are available in the full report and subscriber portal.
Next step
If you are making budgetary, product, channel or M&A decisions in 2026, access to the full report and the accompanying financial models will materially reduce execution risk and increase your odds of capturing the growth exposed by the 7.15% forecast CAGR. Contact PW Consulting to obtain the full Astronomical Telescope Market study and the downloadable scenario model—so your 2026 strategy is built on both empirical rigor and practical playbooks.
For detailed analysis of this topic, please visit the official page: Astronomical Telescope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Karl Fischer Titrators Market to hit USD 336M by 2032, 5.5% CAGR (2026-2032)
By pmarketresearch, 2026-07-22
Karl Fischer Titrators Market: Strategic Intelligence for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but incisive outlook on the Karl Fischer titrators market designed to support high-stakes corporate decisions in 2026. This executive introduction synthesizes our full-market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) to surface the strategic implications that matter most to executives, BD teams, product leaders, and investors. The intent here is to demonstrate the analytic depth of our work while reserving detailed segmentation tables and proprietary model outputs for the full report.
Karl Fischer Titrators Market
Market trajectory: what the numbers tell you
The market for Karl Fischer titrators has exhibited steady expansion through the historical period, rising from approximately USD 170 Million in 2020 to about USD 230 Million in 2025. Our baseline forecast, driven by demand dynamics across regulated laboratories, industrial process monitoring and consumables growth, projects a compound annual growth rate (CAGR) of 5.5% across 2026–2032, bringing the market to roughly USD 336 Million by 2032. This is a mid-single-digit growth market — mature in core laboratory applications yet still offering pockets of premium expansion where technology, software and aftermarket services converge.
Karl Fischer Titrators Market
Why this research matters for 2026 strategies
- Timing for product investments: With predictable mid-single-digit growth, 2026 is a window to prioritize feature differentiation (connectivity, automation, AI-assisted calibration) over broad capacity expansion.
- Consumables and aftermarket economics: Reagents, electrodes and service contracts continue to yield higher margins than hardware. Companies that lock reagent ecosystems and offer remote diagnostics will monetize recurring revenue more effectively.
- Regulatory-driven premium demand: Compliance features (data integrity, audit trails, cybersecurity) are now purchase drivers in regulated industries; product roadmaps that embed these will capture higher price points.
- Operational resilience: Supply-chain fragilities for critical solvents and reagent inputs suggest value in vertical integration or multilateral supplier agreements to protect throughput and pricing.
What the full report contains — practical, transaction-ready deliverables
Our market study is constructed to be operational from day one. Highlights include:
Karl Fischer Titrators Market
- Interactive demand model (2020–2032) with scenario toggles for adoption of automation, reagent-supply disruptions, and regulations.
- Segmented revenue and volume drivers by product type (volumetric vs coulometric), application verticals, and go-to-market channels — analytical logic and elasticities included (note: detailed segment tables are available in the paid report).
- Vendor benchmarking matrix covering product breadth, R&D posture, service network, software stack, and aftermarket monetization potential.
- Go-to-market playbooks tailored for incumbents, challengers, OEM-partners, and reagent suppliers, including recommended commercial KPIs and 12–24 month roadmaps.
- M&A and partnership screening toolkit that flags likely targets by capability gap, revenue yield, and integration risk.
- Regulatory compliance checklist and cyber-resilience plan aligned to major jurisdictions relevant to regulated customers.
Competitive landscape: concentrated, but dynamic
The market displays clear concentration dynamics: the top three suppliers account for a majority share, and the top five capture roughly 85% of industry revenue. This concentration creates durable advantages for established vendors while leaving defined windows for specialized entrants and regional challengers.
- Metrohm AG (Herisau, Switzerland) — Long-established product breadth across volumetric and coulometric titration, increasingly focused on instrument connectivity and compliance. Recent product releases incorporate AI-assisted calibration and remote diagnostics, strengthening after-sales lock-in and service differentiation.
- Mettler Toledo International Inc. (Columbus, Ohio, USA) — Deep laboratory automation and high-throughput solutions. Their EVA line and advanced autosamplers target customers seeking scale and reproducibility. Their emphasis on algorithms that accelerate throughput is a competitive lever for the pharmaceutical and chemical industries.
- Xylem Analytics (Weissenhorn, Germany) — Integrates titration into broader analytical platforms, competing on robustness and compatibility with laboratory information systems; well-positioned for industrial accounts seeking full-suite vendors.
- Established niche and regional players (Hiranuma, Koehler, Hach, Hanna, KEM, Infitek, Hanon) — These firms compete on price-performance, firmware/upgradability, and localized service. Recent firmware and electrode upgrades from several suppliers illustrate an arms race in measurement stability rather than pure hardware innovation.
Recent industry activity underscores the dual thrust of innovation and consolidation: new product launches emphasize automation, AI-enabled calibration, portability and field-capable designs, while strategic partnerships are targeting reagent sustainability. For example, product launches in 2024–2025 introduced faster forecasting algorithms, remote autosampling capabilities, AI-based calibration, and portable analyzers with wireless features — all clear signals that vendors are competing on software, data and service more than raw instrument specs.
Regulatory and operational dynamics shaping buyer behaviour
- Data integrity and cybersecurity: Compliance to FDA 21 CFR Part 11 — and now evolving EU cyber rules — is a non-negotiable for suppliers selling into regulated pharma, biotech and food labs. Instruments without robust audit trails, role-based access, and secure telemetry are increasingly disqualified during vendor selection.
- Consumables and reagent realities: Standard solvents used in volumetric titration require regular titer checks; practical field experience and our sources point to a measurable annual drift that increases operational touchpoints and service demand. This creates recurring revenue opportunities for reagent suppliers and service partners.
- Supply-chain sensitivity: Firms reliant on single-source reagents or proprietary consumables face pricing and availability risk. Buyers will favor vendors that disclose supply-chain resilience and offer multiple reagent options.
Strategic playbook for 2026 — prioritized actions by role
- For incumbents and market leaders: Accelerate platformization — integrate firmware, cloud analytics, remote diagnostics and subscription-based reagent services. Prioritize compliance-ready features to defend the high-value regulated accounts.
- For challengers and new entrants: Focus on specialization—portable analyzers, field-hardened devices, or ultra-stable electrodes—and build partnerships for reagent supply and localized service distribution to overcome scale disadvantages.
- For reagent and consumable suppliers: Lock-in through certifiable reagent ecosystems, publish stability and shelf-life data, and offer titer-check services; this converts low-margin consumables into sticky, revenue-generating relationships.
- For investors and M&A teams: Target firms with strong service attach rates, software modules capable of SaaS transitions, or unique reagent chemistries. Valuations should reflect not only instrument sales but recurring revenue potential and regulatory-compliance assets.
Operational priorities for 2026 include firm-level investments in cybersecurity, audit-ready data capture, and remote service capabilities. KPIs to track: service attach rate, reagent recurring revenue, average resolution time for field issues, software subscription penetration, and margin evolution in aftermarket vs hardware.
Limitations and next-step intelligence
This introduction highlights the high-level conclusions and practical levers derived from our full study. To preserve strategic value for subscribers, we deliberately withhold granular regional and segment-by-application figures in this public summary. The full report provides:
- Comprehensive segment-level revenue and volume splits (by type, application and region) with year-by-year estimates;
- Proprietary vendor scoring sheets and deal-by-deal M&A models;
- Full methodology, primary-source interview transcripts, and the interactive forecast workbook that supports scenario analysis (supply shocks, accelerated automation adoption, regulatory tightening).
How to use our findings in 2026 planning
Decision-makers should treat the market as a steady-growth, high-service-opportunity sector. Tactical moves for 2026 include: re-prioritizing R&D budgets toward connectivity and compliance features; launching reagent-subscription pilots in core accounts; negotiating multi-year reagent supply agreements to stabilize input cost exposure; and evaluating bolt-on acquisitions that close service or software gaps.
PW Consulting’s full Karl Fischer Titrators Market report is designed as an actionable toolkit for these moves. If your 2026 strategy depends on selecting partners, structuring M&A, or reshaping go-to-market models in this segment, the complete dataset and scenario modules will materially shorten decision cycles and reduce execution risk.
Contact PW Consulting for access to the full report, vendor matrices and the interactive forecast model — we provide tailored briefings to translate this market intelligence directly into executable 12–24 month plans.
For detailed analysis of this topic, please visit the official page: Karl Fischer Titrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gunshot Detection Market Poised for USD 2,254M by 2032 at 11.8% CAGR
By pmarketresearch, 2026-07-22
Gunshot Detection Systems Market: Strategic Intelligence for 2026 Decision-Makers
Executive snapshot
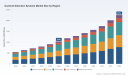
As security architectures evolve under pressure from urban violence, critical-infrastructure hardening, and enterprise risk management, the gunshot detection systems market has moved from niche defence programs toward broader public-safety and commercial deployments. Using 2025 as the report base year, PW Consulting’s analysis shows the market accelerating into a sustained growth trajectory through our 2026–2032 forecast horizon, at a compound annual growth rate (CAGR) of 11.8%. The commercial market opportunity more than doubles over the forecast period, reflecting accelerating product maturity, modular integration with video/AI stacks, and widening access to public funding and procurement channels.
Gunshot Detection Systems Market
Why this study matters for 2026 strategy
- Investment timing: 2026 is a pivotal year for procurement cycles. Early movers who align procurement specifications with emerging multi-sensor architectures (acoustic + infrared + infrasound + energy-based sensing) capture disproportionate advantage in interoperability and lifecycle costs.
- Vendor consolidation and partner selection: The market demonstrates meaningful concentration among a small set of global suppliers. Strategic buyers must weigh long-term roadmaps and integration commitments as much as initial purchase price.
- Funding and compliance optimization: Federal grant windows and certification regimes materially affect feasible deployment models. Organizations that synchronize technical specifications with funding eligibility and regulatory requirements reduce implementation risk and improve ROI.
- Operational outcomes over feature chasing: Procurement decisions should be driven by measurable operational KPIs (detection-to-dispatch latency, false-alarm profile in the target environment, maintainability, and vendor SLAs), not marketing claims alone.
What PW Consulting’s full report delivers (practical, decision-ready content)
Our research is structured to inform board-level investment decisions, procurement teams, and systems integrators. Key deliverables include:
Gunshot Detection Systems Market
- Market sizing and transparent methodology—historical baseline, 2025 market calibration, and scenario-based forecasts through 2032.
- Vendor scorecards and maturity maps—differentiating acoustic-only incumbents from multi-mode and energy/infrasound specialists, including commercial traction, product roadmaps, and certification status.
- Procurement playbooks and RFP templates—tailored to municipal, education, corporate campus, and critical-infrastructure buyers.
- Integration blueprints—recommended architectures for combining gunshot sensors with video analytics, access control, dispatch systems, and cloud services.
- ROI models and total-cost-of-ownership (TCO) calculators—sensitivity-tested to reflect grant funding, staffing, and lifecycle maintenance scenarios.
- Operational KPIs and acceptance testing protocols—benchmarks for field trials, false-alarm reduction, and detection accuracy under representative environmental noise.
- Regulatory and funding matrix—mapping DHS SAFETY Act requirements, grant eligibility (e.g., Bureau of Justice Assistance), and national guidance frameworks to procurement routes.
- Deployment case studies and lessons learned—from campus pilots to large-scale city and vehicle-mounted/force-protection programs.
Note: This introduction highlights the scope and utility of our analysis. Detailed segment tables, vendor financials, and hyper-granular regional/application splits are intentionally withheld here to preserve the full report’s value—access to the complete dataset and downloadable operational assets is available through the PW Consulting portal.
Gunshot Detection Systems Market
Competitive landscape: how to read vendor intent and capability
The competitive map blends legacy defence suppliers, specialized acoustic firms, and newer entrants innovating on sensor fusion and AI. A handful of vendors command material market share—reflecting product maturity, installed base, and channel relationships—while smaller, R&D-focused firms push sensor innovation.
- ACOEM Group (France): ACOEM’s Acoustic Threat Detector family emphasizes single-sensor acoustic intelligence with a large attribute engine, positioning it for critical infrastructure and first-responder environments where situational awareness and localisation are priorities.
- EAGL Technology, Inc. (US): EAGL’s energy-based approach and focus on adaptive response and systems integration (video, access control, AI workflows) make it a strong contender for integrated security programs and for buyers seeking broad automation in emergency protocols. DHS SAFETY Act approval adds procurement defensibility for government buyers.
- Hyperion Technology Group (US): With infrasound-specialised sensors, Hyperion targets military and industrial applications where detection through barriers or over distance matters—useful for certain perimeter and force-protection scenarios.
- QinetiQ (EARS family): QinetiQ’s soldier/portable localization systems are combat-proven and appeal to defence and security services procuring portable soldier-worn or vehicle solutions.
- Raytheon Company (US): Raytheon’s vehicle-mounted Boomerang and upgrades are tailored to defence and tactical domains; their strengths lie in integration with broader threat-detection suites.
- Shooter Detection Systems (SDS, US): SDS has broadened from indoor Guardian systems to a new Perimeter outdoor product line, combining acoustic and infrared modalities with ML; SDS has also earned market recognition and awards validating commercial traction.
- SoundThinking / ShotSpotter (US): A pioneer in municipal acoustic gunshot detection, the company has focused on expanding its AI engine and city-scale deployment playbook—strong in law-enforcement integrations.
- Safety Dynamics, Inc. (US): A focused player addressing public-safety procurement channels and law-enforcement use cases, emphasizing practical deployments and local-market go-to-market strategies.
Recent product and market movements to watch
- Product refresh and multi-mode trend: Several vendors announced or commercialised multi-sensor outdoor solutions and upgraded acoustic intelligence engines in 2025–2026—signalling a shift from single-mode acoustic reliance to fused sensing for better false-alarm control and localization.
- Certification-driven procurement: DHS SAFETY Act approvals continue to be a gating factor for U.S. government and critical-infrastructure contracts; buyers should prioritise vendors with formal certification or a clear pathway to certification.
- Grant-enabled scale: Federal and state grant programs (for example, BJA-administered awards) materially lower the barrier to entry for municipal pilots; however, these funding sources are time-boxed and require alignment of technical specs with grant requirements.
Practical 2026 decision playbook (six steps)
- Clarify mission and use-case hierarchy: Rank primary outcomes (rapid detection for law enforcement response, deterrence, forensic evidence capture, or military force protection) to guide sensor modality choice.
- Define measurable acceptance criteria: Set testable KPIs for detection latency, localization accuracy, false-alarm ceilings in the target acoustic environment, and system availability/SLA expectations.
- Run phased pilots with phased scope: Start with small, instrumented pilots coupled to local dispatch and a defined evaluation window; extend only when KPIs and integration metrics are met.
- Prioritise integrator capabilities: Choose vendors or partners that can demonstrate secure API integration with VMS, CAD/dispatch, and identity/access systems, reducing downstream system integration cost.
- Lock procurement to upgrade and maintenance economics: Evaluate TCO across 5–7 year horizons, including software/AI subscription models, remote calibration, and field-service availability.
- Prepare privacy, governance, and community communications: Early engagement with stakeholders—privacy officers, legal counsel, and community leaders—reduces adoption friction and mitigates reputational risk.
Key risks and mitigations
- False positives and nuisance alarms: Mitigate with sensor fusion, environment-specific ML training, and staged acceptance testing to collect representative acoustic datasets.
- Regulatory and procurement friction: Align technical specs to certification regimes (e.g., DHS SAFETY Act) and grant application timelines to secure funding and contractual access.
- Vendor lock and roadmap risk: Structure contracts with modular interoperability clauses and data export provisions; insist on documented APIs and third-party integration references.
- Operational sustainment: Budget for ongoing calibration, seasonal re-tuning, and software updates—these are common causes of degraded long-term performance if unbudgeted.
How PW Consulting helps you act in 2026
Our report is designed as an operational toolkit for 2026 procurement cycles. Beyond market numbers and vendor profiles, we provide executable artifacts: RFP templates, field-test protocols, TCO calculators, and a regulatory/funding playbook aligned to current grant windows and certification pathways. For executives, we translate market dynamics into board-level investment scenarios and risk-adjusted timelines. For procurement and security teams, we deliver the step-by-step playbook to pilot, procure, and scale with predictable outcomes.
Next steps
This introduction surfaces the strategic implications, vendor dynamics, and practical decision frameworks you need to prioritise investments this year. The full PW Consulting Gunshot Detection Systems Market report contains the complete quantitative annex—detailed segmentation by region, application, and installation; vendor financials and market share tables; and downloadable operational templates. To access the complete dataset and the implementation toolkit, visit the PW Consulting report page or contact your PW Consulting advisor for a tailored briefing and procurement-ready deliverables.
For detailed analysis of this topic, please visit the official page: Gunshot Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Airbag Market to Reach USD 29.79B by 2032 at 7.25% CAGR
By pmarketresearch, 2026-07-22
Airbag Market 2026 Strategic Preview: Navigating Growth, Complexity and Compliance
As corporate leaders prepare capital allocation, sourcing, and product roadmaps for 2026, PW Consulting’s Airbag Market study delivers the kind of targeted intelligence that separates defensive reactions from proactive strategies. The global airbag market, having expanded steadily through 2020–2025 and projected to continue rising into the next decade, presents a clear growth runway — our forecast models show the market moving from an estimated USD 18.28 billion in 2025 to roughly USD 29.79 billion by 2032 at a compounded annual growth rate of 7.25% across the 2026–2032 forecast window. That pace reflects both traditional automotive replacement cycles and a redefinition of “airbag” use cases across new vehicle architectures and non-automotive applications.
Airbag Market
Why this research matters for 2026 decisions
-
Timing capital and R&D: With a mid-single-digit-plus CAGR and accelerating product innovation, companies must decide whether to prioritize organic R&D, targeted acquisitions, or co-development partnerships now — each option has materially different return and risk profiles in a market expanding both by volume and by application.
Airbag Market -
Supply chain resilience: Material cost volatility and regulatory constraints are intersecting to increase operational risk. Strategic sourcing, hedging, and second-source strategies will materially influence margins and delivery reliability in 2026.
Airbag Market -
Regulatory and environmental compliance: New rules governing connected-vehicle technologies and hazardous waste management create compliance obligations that shape product design, export strategy, and aftermarket service models.
-
New use-cases and adjacencies: Innovations such as wearable airbags and vehicle-integrated external protection are expanding the addressable market and prompting OEMs and suppliers to rethink product roadmaps and go-to-market models.
What the PW Consulting report gives you (practical deliverables)
-
Actionable market-sizing and scenario models: Granular demand models and Monte Carlo scenario outputs that isolate the impact of EV penetration, vehicle parc growth, ADAS adoption, and new product categories on TAM and revenue trajectories.
-
Playbooks for 2026 strategic choices: Clear decision frameworks for make vs. buy, regional manufacturing footprint choices, and modular product roadmaps linked to ROI thresholds.
-
Supplier and technology heatmaps: Comparative analysis of inflator and module technologies, manufacturing capabilities, and assembly economics to prioritize partners and acquisition targets.
-
Regulatory impact assessments: Practical checklists and compliance roadmaps covering export controls for connected vehicle ICTS, hazardous waste management for recalled airbags, and region-specific testing protocols.
-
Aftermarket & reverse logistics templates: Cost models and operational flows for handling recalls, safe disposal, and recycling that preserve OEM brand and minimize regulatory exposure.
-
M&A playbook and diligence checklist: Financial and technical red flags we use to qualify targets, from intellectual property scope to inflator manufacturing capacity and legacy liability exposure.
Market dynamics shaping the 2026 strategic agenda
Three concurrent dynamics will disproportionately influence decisions in 2026: product diversification, regulatory pressure, and supply-chain cost volatility. First, product diversification is no longer incremental. Suppliers and OEMs are commercializing airbags beyond occupant frontal protection — from pedestrian and cyclist protection systems to wearable solutions designed for fall mitigation. Second, regulatory action is reshaping supplier risk: the U.S. Department of Commerce’s early-2025 final rule on ICTS in connected vehicles alters allowable supplier pools for certain critical systems, forcing procurement teams to redesign supplier qualification matrices. Third, raw-material cost swings — notably in high-performance polymers used for airbag fabrics and housings — are compressing margins and raising the economic case for localized polymer supply or strategic long-term contracts.
Recent industry rollouts signal where product innovation is concentrated. Suppliers and OEMs are bringing forward second-generation external protection systems and wearable airbags that leverage automotive-grade sensing and ignition systems, and truck manufacturers are integrating curtain-type protection as standard equipment in heavy-duty platforms. These developments expand use-cases and create cross-industry competitive tension between incumbent airbag suppliers and adjacent-material or electronics specialists.
Supply-chain & regulatory implications (what to act on in 2026)
-
Export controls and supplier qualification: The Bureau of Industry and Security’s rule (January 2025) demands immediate mapping of ICTS dependencies in connected airbag-adjacent systems. OEMs and Tier-1s should build compliance inventories, re-certify non-permissible sources, and pre-stage alternate suppliers for critical sensor and connectivity modules.
-
Hazardous-waste and recall logistics: Changes to RCRA interpretation and interim rules on recalled airbags require firms to operationalize hazardous-waste handling within aftermarket returns and recycling programs. This has cost and reputational implications — invest in certified reverse-logistics partners or build in-house capability sooner than later.
-
Raw-material price management: Polymer input price swings (e.g., Nylon 6,6) materially affect per-unit economics. Hedging strategies, long-term offtake agreements, and selective vertical integration into textile or compound production should be evaluated against capital availability and desired control over quality and lead times.
Competitive landscape — who matters and how they’re repositioning
The airbag supplier market remains concentrated: the top three global suppliers account for a substantial portion of industry revenues, and the top five control roughly three quarters of the market by revenue. That concentration favors incumbents in OEM negotiations, but it also raises the strategic value of niche innovators and specialized inflator manufacturers that can displace legacy architectures through differentiated technology or cost positions.
Key players — such as Autoliv, Joyson Safety Systems, ARC Automotive, Daicel Corporation, Toyota Boshoku, Nihon Plast, Toyoda Gosei, Hyundai Mobis, ZF Friedrichshafen, and Continental — are pursuing a blend of product innovation and market consolidation. Recent product news underscores this trend: wearable airbag solutions leveraging cross-industry partnerships have emerged from traditional inflator suppliers; second-generation external cyclist- and pedestrian-protection systems are being commercialized by major safety suppliers; and OEMs are integrating curtain protection for commercial truck fleets as standard equipment. Collectively, these moves signal a market where incumbents extend scope outward while smaller specialists push inward on technology differentiation.
Strategic imperatives for 2026
-
Prioritize regulatory-first sourcing: Reassess supplier qualification to eliminate single points of failure from prohibited ICTS sources and design contracts that include compliance warranties and audit rights.
-
Invest selectively in new form factors: Allocate a portion of R&D budget to occupant-adjacent protection (wearables, exterior systems, heavy-duty vehicle curtains) where first-mover advantage is achievable via OEM partnerships.
-
Design for circularity and safe disposal: Build reverse-logistics pilots now to mitigate recall costs and align with hazardous-waste obligations — this will be a competitive differentiator in tender processes.
-
Lock in polymer supply economics: Use blended approaches (spot + hedged contracts + localized partners) to stabilize margins while retaining flexibility to scale production with demand.
-
Target M&A to fill capability gaps: Use acquisitions to accelerate access to inflator technologies, sensor fusion IP, or textile manufacturing that are otherwise time-consuming to develop internally.
-
Stress-test portfolios against scenarios: Apply downside scenarios (supply shock, accelerated regulation, rapid EV adoption) to prioritize the parts of your product portfolio you will double down on vs. monetize.
How PW Consulting’s study helps execution in 2026
The study is designed as a decision-support tool for executives and corporate development teams. Beyond headline market-sizing — which captures the growth path from 2025 into 2032 at a 7.25% CAGR — the research anchors each recommendation in operational levers: unit-cost sensitivities, supplier risk heatmaps, regulatory compliance checklists, and prioritized action plans for R&D and M&A. We deliberately hold back granular proprietary splits in this preview to preserve the competitive value of the full intelligence pack — clients receive the full segmentation, supplier scorecards, and dynamic scenario files that translate strategy into executable roadmaps.
Next steps
For leadership teams making capital and procurement decisions in 2026, timing is critical. The market is large and expanding, but winners will be defined not by participation alone, but by the ability to manage complex regulatory constraints, secure raw-material economics, and rapidly commercialize adjacent protection solutions. PW Consulting’s full Airbag Market report provides the empirical models, tactical playbooks, and competitive diagnostics needed to prioritize actions with confidence. Contact our industry desk to access the complete dataset, customizable scenario tools, and our executive workshop to translate insights into a 90‑day action plan.
For detailed analysis of this topic, please visit the official page: Airbag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com