

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Composite Insulators Market to Hit USD 344.8M by 2032 (6.98% CAGR)

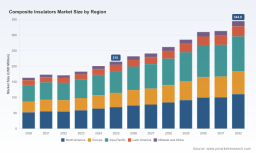
Composite Insulators Market — Strategic Briefing for 2026 Decision-Makers
Why this briefing matters for 2026
As utilities and electrical-equipment OEMs navigate replacement cycles, grid electrification, and regulatory updates, composite insulators have moved from niche to mainstream in high-voltage asset strategies. Our latest market model shows the global composite insulators market emerging from early-decade volatility to a clear expansion phase: the market reached roughly USD 215 million in 2025 and, under our baseline, is expected to expand at a compound annual growth rate of approximately 6.98% through the 2026–2032 forecast horizon. For boards, procurement leads, and strategy teams planning 2026 capital and MRO budgets, the implications are immediate — choices made this year about supplier footprints, certification roadmaps, and raw-material contracting will materially condition cost, lead time, and risk through the next multi-year upgrade cycle.
Composite Insulators Market
Snapshot: what the macro picture tells us
- Resilient growth trajectory: After modest year-to-year fluctuations in the early 2020s, demand momentum reasserted itself by 2024–2025, setting a platform for steady expansion into 2032. Management teams should treat this as a multi-year volume opportunity rather than a short-lived spike.
- Fragmented competitive landscape: Market concentration is low — the top three and top five players together account for less than a third of market revenue — which creates both opportunities for consolidation and risks of margin pressure from regional low-cost producers.
- Market entry and scale economics: Scale benefits accrue in pultrusion capacity, quality control, and IP-protected assembly techniques; however, regional logistics and certification demands mean local or nearshore production continues to be a relevant strategic lever.
Market dynamics that will shape supplier selection and capex in 2026
- Raw-material sensitivity: Pultrusion economics are tightly coupled to glass-fiber and resin pricing. As a practical benchmark, pultruded fiberglass profiles trade in broad ranges (dependent on resin grade and customization) and manufacturers’ margins can compress rapidly when resin or fiber prices spike. Procurement teams should test supplier cost models against ±20–30% raw-material shocks and seek indexed contracts or dual-sourcing strategies to preserve margin and availability.
- Standards and certification: The 2025 refresh of IEC 61109 (Edition 3.0) and the release of EN IEC 62217:2025 raise minimum sheath and interface quality requirements — effectively shortening certification lead times for incumbents who have already invested in controlled manufacturing and test protocols. For buyers, certification status will increasingly be a differentiator that shortens qualification cycles; for suppliers, the standards create an entry barrier that rewards capital investment in testing infrastructure.
- Technology and materials evolution: Improvements in silicone formulations and HTV injection techniques are enabling longer service life and simplified assembly. Suppliers announcing higher-consistency silicone grades and improved core-to-sheath bonding are not only improving product reliability but also reducing lifecycle O&M costs — a compelling value proposition for asset owners seeking TCO reductions.
Competitive landscape: positioning, playbooks, and likely moves
The market combines specialty European OEMs with vertically integrated production, high-volume Asian manufacturers, and a number of regional producers focused on distribution networks. Several archetypes are visible:
Composite Insulators Market
- Specialist European innovators: Firms with full-process integration and advanced material know-how present premium, high-reliability offers to HV OEMs and utilities. Their competitive advantage lies in validated production technologies, proprietary material handling, and proximity to stringent certification regimes.
- High-volume Chinese manufacturers: A dense supplier base offers modular product ranges and competitive pricing for wide deployment in emerging and domestic markets. These players excel in scale manufacturing and rapid order fulfilment but sometimes face longer qualification cycles in regulated Western markets.
- Indian exporters and regional specialists: Producers that can manufacture up to high-voltage classes and export at competitive rates are a durable force in markets where price and availability dominate purchasing decisions.
Illustrative company insights (select):
Composite Insulators Market
- SAVER S.p.A. (Italy): Vertical integration and a focus on hollow composite insulators position them well for HV OEM partnerships where process control and certification matter. Their model reduces supplier coordination risk for buyers needing turnkey, certified components.
- Power Composites / Reinhausen technology (Germany): Known for advanced epoxy-resin glass-fiber cylinders and HTV-injection techniques; technology transfers and asset sales in late 2025 signal potential consolidation and capacity relocation — a trend to watch for implications on European supply and IP ownership.
- SH POWER, Hebei manufacturers, and other Asian players: Broad product portfolios, export orientation, and participation at major trade shows underscore sustained competitiveness on price and speed-to-market. Buyers should weigh qualification timelines against cost benefits.
- Shemar USA and regional specialists: Regional presence combined with focused product lines enable faster certification cycles and stronger aftermarket service agreements — valuable for utilities prioritizing reliability over lowest-cost bids.
Recent moves that matter for 2026 strategy
- Mid-2025 and year-end activity saw strategic IP and asset reallocation: an advisory-led acquisition and production-asset transfer announced in late 2025 marks active consolidation and creates potential capacity shifts in Europe beginning in 2026. Companies evaluating sourcing strategies should simulate availability and lead-time changes from such capacity moves.
- Materials suppliers are upgrading product portfolios — a leading silicone producer unveiled new high-consistency formulations in mid-2025 — strengthening suppliers who can integrate these materials into certified processes.
- Trade show participation in early 2026 continued to reflect market vitality: manufacturers showcased higher-voltage designs and service propositions, accelerating buyer engagement and shortening proof-of-concept cycles for qualified suppliers.
Actionable implications for 2026 planning
- Procurement and inventory: Lock in strategic raw-material indexation clauses or multi-year supply contracts for resin/fiber to stabilize unit economics. Where possible, create a two-tier sourcing strategy (certified premium suppliers + qualified regional second-source) to balance reliability and cost.
- Certification and supplier qualification: Prioritize suppliers with current conformity to the 2025 standard updates; the time and cost to qualify new vendors into IEC 61109/EN IEC 62217-compliant supply chains can materially delay projects.
- CapEx and footprint decisions: If you are evaluating own-manufacturing or nearshoring, model expected demand growth versus breakeven pultrusion capacity utilization — high fixed costs mean outsized benefits only at scale or when combined with adjacent product lines.
- M&A and partnership playbook: Given low market concentration, 2026–2028 is a window for bolt-on acquisitions that deliver immediate scale, certification assets, or IP. Prioritize targets with validated testing records, pultrusion capability, and clean compliance histories.
- Product strategy: Emphasize lifecycle cost and service (e.g., long warranties, on-site diagnostics, standardized replacement kits) rather than competing solely on unit price. Utilities are increasingly receptive to TCO-based procurement frameworks.
- Risk and scenario planning: Stress-test supplier networks against raw-material spikes, regional tariff disruptions, and certification bottlenecks. Build contingency agreements with qualified alternative producers before project start dates.
What the full PW Consulting report contains (practical deliverables)
Our complete market study—designed as an operational playbook for 2026—includes the following deliverables:
- Validated market-sizing and seven-year forecasting models with scenario toggles for raw-material price stress and regional demand shifts;
- Supplier scorecards and qualification checklists that map technical capability, certification status, lead time, and geopolitical exposure;
- Cost-to-serve and pultrusion breakeven analyses that support make-vs-buy decisions and footprint planning;
- Regulatory readiness roadmap tied to IEC/EN updates and recommended investment sequencing to shorten qualification timelines;
- M&A diligence templates focused on IP assessment, test-lab capability, and capacity integration; and
- Procurement negotiation playbooks (indexing clauses, KPI-backed SLAs, and inventory buffers) tailored for the composite insulator supply chain.
How to use this briefing in boardroom planning
For CEOs, the key decision is whether to treat composite insulators as a strategic component (necessitating investment in supply security and certification) or as a tactical commoditized buy. For procurement and plant managers, the near-term emphasis should be on securing raw-material exposure mitigation and accelerating supplier qualification under the 2025 standards. For corporate development teams, the fragmented market and recent asset transfers reveal acquisition targets that can be rapidly integrated to obtain scale and testing capability.
Next steps
This executive briefing is a gateway: it highlights the essential directional signals and operational levers for 2026 decision-making. The full PW Consulting Composite Insulators Market report contains the granular segmentation, supplier-level benchmarking, and excel-based models you need to convert insight into executable strategy. Reach out to our team to request the complete dataset, model access, and a tailored workshop to convert the findings into your 2026 procurement and investment roadmap.
For detailed analysis of this topic, please visit the official page: Composite Insulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com