

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Airbag Market to Reach USD 29.79B by 2032 at 7.25% CAGR

Airbag Market 2026 Strategic Preview: Navigating Growth, Complexity and Compliance
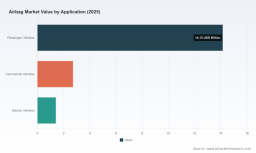
As corporate leaders prepare capital allocation, sourcing, and product roadmaps for 2026, PW Consulting’s Airbag Market study delivers the kind of targeted intelligence that separates defensive reactions from proactive strategies. The global airbag market, having expanded steadily through 2020–2025 and projected to continue rising into the next decade, presents a clear growth runway — our forecast models show the market moving from an estimated USD 18.28 billion in 2025 to roughly USD 29.79 billion by 2032 at a compounded annual growth rate of 7.25% across the 2026–2032 forecast window. That pace reflects both traditional automotive replacement cycles and a redefinition of “airbag” use cases across new vehicle architectures and non-automotive applications.
Airbag Market
Why this research matters for 2026 decisions
-
Timing capital and R&D: With a mid-single-digit-plus CAGR and accelerating product innovation, companies must decide whether to prioritize organic R&D, targeted acquisitions, or co-development partnerships now — each option has materially different return and risk profiles in a market expanding both by volume and by application.
Airbag Market -
Supply chain resilience: Material cost volatility and regulatory constraints are intersecting to increase operational risk. Strategic sourcing, hedging, and second-source strategies will materially influence margins and delivery reliability in 2026.
Airbag Market -
Regulatory and environmental compliance: New rules governing connected-vehicle technologies and hazardous waste management create compliance obligations that shape product design, export strategy, and aftermarket service models.
-
New use-cases and adjacencies: Innovations such as wearable airbags and vehicle-integrated external protection are expanding the addressable market and prompting OEMs and suppliers to rethink product roadmaps and go-to-market models.
What the PW Consulting report gives you (practical deliverables)
-
Actionable market-sizing and scenario models: Granular demand models and Monte Carlo scenario outputs that isolate the impact of EV penetration, vehicle parc growth, ADAS adoption, and new product categories on TAM and revenue trajectories.
-
Playbooks for 2026 strategic choices: Clear decision frameworks for make vs. buy, regional manufacturing footprint choices, and modular product roadmaps linked to ROI thresholds.
-
Supplier and technology heatmaps: Comparative analysis of inflator and module technologies, manufacturing capabilities, and assembly economics to prioritize partners and acquisition targets.
-
Regulatory impact assessments: Practical checklists and compliance roadmaps covering export controls for connected vehicle ICTS, hazardous waste management for recalled airbags, and region-specific testing protocols.
-
Aftermarket & reverse logistics templates: Cost models and operational flows for handling recalls, safe disposal, and recycling that preserve OEM brand and minimize regulatory exposure.
-
M&A playbook and diligence checklist: Financial and technical red flags we use to qualify targets, from intellectual property scope to inflator manufacturing capacity and legacy liability exposure.
Market dynamics shaping the 2026 strategic agenda
Three concurrent dynamics will disproportionately influence decisions in 2026: product diversification, regulatory pressure, and supply-chain cost volatility. First, product diversification is no longer incremental. Suppliers and OEMs are commercializing airbags beyond occupant frontal protection — from pedestrian and cyclist protection systems to wearable solutions designed for fall mitigation. Second, regulatory action is reshaping supplier risk: the U.S. Department of Commerce’s early-2025 final rule on ICTS in connected vehicles alters allowable supplier pools for certain critical systems, forcing procurement teams to redesign supplier qualification matrices. Third, raw-material cost swings — notably in high-performance polymers used for airbag fabrics and housings — are compressing margins and raising the economic case for localized polymer supply or strategic long-term contracts.
Recent industry rollouts signal where product innovation is concentrated. Suppliers and OEMs are bringing forward second-generation external protection systems and wearable airbags that leverage automotive-grade sensing and ignition systems, and truck manufacturers are integrating curtain-type protection as standard equipment in heavy-duty platforms. These developments expand use-cases and create cross-industry competitive tension between incumbent airbag suppliers and adjacent-material or electronics specialists.
Supply-chain & regulatory implications (what to act on in 2026)
-
Export controls and supplier qualification: The Bureau of Industry and Security’s rule (January 2025) demands immediate mapping of ICTS dependencies in connected airbag-adjacent systems. OEMs and Tier-1s should build compliance inventories, re-certify non-permissible sources, and pre-stage alternate suppliers for critical sensor and connectivity modules.
-
Hazardous-waste and recall logistics: Changes to RCRA interpretation and interim rules on recalled airbags require firms to operationalize hazardous-waste handling within aftermarket returns and recycling programs. This has cost and reputational implications — invest in certified reverse-logistics partners or build in-house capability sooner than later.
-
Raw-material price management: Polymer input price swings (e.g., Nylon 6,6) materially affect per-unit economics. Hedging strategies, long-term offtake agreements, and selective vertical integration into textile or compound production should be evaluated against capital availability and desired control over quality and lead times.
Competitive landscape — who matters and how they’re repositioning
The airbag supplier market remains concentrated: the top three global suppliers account for a substantial portion of industry revenues, and the top five control roughly three quarters of the market by revenue. That concentration favors incumbents in OEM negotiations, but it also raises the strategic value of niche innovators and specialized inflator manufacturers that can displace legacy architectures through differentiated technology or cost positions.
Key players — such as Autoliv, Joyson Safety Systems, ARC Automotive, Daicel Corporation, Toyota Boshoku, Nihon Plast, Toyoda Gosei, Hyundai Mobis, ZF Friedrichshafen, and Continental — are pursuing a blend of product innovation and market consolidation. Recent product news underscores this trend: wearable airbag solutions leveraging cross-industry partnerships have emerged from traditional inflator suppliers; second-generation external cyclist- and pedestrian-protection systems are being commercialized by major safety suppliers; and OEMs are integrating curtain protection for commercial truck fleets as standard equipment. Collectively, these moves signal a market where incumbents extend scope outward while smaller specialists push inward on technology differentiation.
Strategic imperatives for 2026
-
Prioritize regulatory-first sourcing: Reassess supplier qualification to eliminate single points of failure from prohibited ICTS sources and design contracts that include compliance warranties and audit rights.
-
Invest selectively in new form factors: Allocate a portion of R&D budget to occupant-adjacent protection (wearables, exterior systems, heavy-duty vehicle curtains) where first-mover advantage is achievable via OEM partnerships.
-
Design for circularity and safe disposal: Build reverse-logistics pilots now to mitigate recall costs and align with hazardous-waste obligations — this will be a competitive differentiator in tender processes.
-
Lock in polymer supply economics: Use blended approaches (spot + hedged contracts + localized partners) to stabilize margins while retaining flexibility to scale production with demand.
-
Target M&A to fill capability gaps: Use acquisitions to accelerate access to inflator technologies, sensor fusion IP, or textile manufacturing that are otherwise time-consuming to develop internally.
-
Stress-test portfolios against scenarios: Apply downside scenarios (supply shock, accelerated regulation, rapid EV adoption) to prioritize the parts of your product portfolio you will double down on vs. monetize.
How PW Consulting’s study helps execution in 2026
The study is designed as a decision-support tool for executives and corporate development teams. Beyond headline market-sizing — which captures the growth path from 2025 into 2032 at a 7.25% CAGR — the research anchors each recommendation in operational levers: unit-cost sensitivities, supplier risk heatmaps, regulatory compliance checklists, and prioritized action plans for R&D and M&A. We deliberately hold back granular proprietary splits in this preview to preserve the competitive value of the full intelligence pack — clients receive the full segmentation, supplier scorecards, and dynamic scenario files that translate strategy into executable roadmaps.
Next steps
For leadership teams making capital and procurement decisions in 2026, timing is critical. The market is large and expanding, but winners will be defined not by participation alone, but by the ability to manage complex regulatory constraints, secure raw-material economics, and rapidly commercialize adjacent protection solutions. PW Consulting’s full Airbag Market report provides the empirical models, tactical playbooks, and competitive diagnostics needed to prioritize actions with confidence. Contact our industry desk to access the complete dataset, customizable scenario tools, and our executive workshop to translate insights into a 90‑day action plan.
For detailed analysis of this topic, please visit the official page: Airbag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com