

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Astronomical Telescope Market to Reach USD 730.94M by 2032 at 7.15% CAGR

Astronomical Telescope Market — Strategic Outlook for 2026 Decision-Makers
Introduction: Why 2026 Is a Pivotal Year
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, actionable briefing on the Astronomical Telescope market that frames the strategic choices companies must make in 2026. Our new market study synthesizes five years of historical performance (2020–2025) with a multi-scenario forecast through 2032. The market has expanded materially from the early-2020s and is projected to continue growing at a compound annual growth rate (CAGR) of approximately 7.15% across the 2026–2032 forecast window. Such momentum—paired with rapid product innovation, shifts in consumer behavior, and evolving standards—creates a narrow window for decisive action. This briefing highlights the strategic value of our full study for executives preparing budgets, R&D roadmaps, partnerships, and M&A agendas in 2026.
Astronomical Telescope Market
Market Snapshot (what the numbers are telling us)
By the close of our base year, 2025, the global astronomical telescope market reached a notable scale, and our baseline projection places 2026 above that base—continuing toward a materially larger market by 2032. This trajectory reflects durable end-market demand from hobbyists, educational institutions, and research entities, and importantly it is being reshaped by two converging forces: product intelligence (smart telescopes and app ecosystems) and sustained demand for optical performance across a spectrum of price points.
Astronomical Telescope Market
Competitive concentration remains low-to-moderate, indicating a fragmented supply base with multiple specialist brands retaining distinct niches. That structure supports both continued innovation and opportunistic consolidation—each representing different strategic pathways for incumbents and new entrants.
Astronomical Telescope Market
How this study informs 2026 corporate decisions
- Portfolio prioritization: Decide whether to accelerate investments in smart, app-integrated telescopes, double down on premium optical lines, or expand value-tier offerings for mass-market adoption.
- R&D and product roadmaps: Align optics, mount systems, and software roadmaps with adjacent trends in imaging sensors and user experience to maximize product relevance in three-year horizons.
- Supply-chain and cost strategies: Rebalance sourcing and vertical integration decisions to mitigate volatility in specialized optical components and precision labor costs.
- Channel and go-to-market: Reconfigure distribution and after-sales models for a world where app platforms, direct-to-consumer sales, and education partnerships coexist.
- M&A and partnership screening: Identify targets that add immediate capability (e.g., smart telescope platforms, sensor partnerships, or regional manufacturing footprints) and estimate accretive thresholds under multiple scenarios.
- Regulatory & standards preparedness: Anticipate ISO and other standardization shifts that affect product claims, test methods, and export documentation—and incorporate these into product certification timelines.
What the full report delivers (practical, actionable content)
- Proprietary market-sizing and forecasting model with transparent assumptions and scenario toggles for demand shocks, technology adoption rates, and price deflation.
- Segment-level demand drivers and margin archetypes (by product architecture and customer cohort), with risk-adjusted uptake curves that support budget planning.
- Go-to-market playbooks: channel economics, bundling strategies (hardware + subscription software), and education & outreach blueprints tailored to institutional buyers.
- Supplier and cost-risk matrix: mapping of specialized optical component suppliers, critical labor nodes, and mitigation levers for procurement teams.
- Competitor dossiers and comparative capability maps that benchmark product families, technology bets, and route-to-customer strengths.
- M&A screening and valuation templates calibrated to this market’s growth profile and competitive dynamics.
- Executive dashboards and downloadable financial models for scenario testing during board-level strategy sessions.
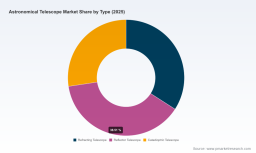
Note: The full report contains granular regional, type and application splits, detailed financials, and company scorecards. In keeping with this briefing’s role as a strategic trailer, those granular tables are reserved for the full report and subscriber portal.
Competitive Landscape — who is shaping the market and how
The market structure is characterized by specialists pursuing differentiated technology and user experiences. Several players are particularly influential in shaping 2026 competitive choices:
- Celestron (Torrance, CA): Continues to couple computerized mounts (NexStar line) and high-performance Schmidt-Cassegrain optics (EdgeHD) with integrated solutions such as the Origin intelligent home observatory. Celestron’s breadth—augmented by product updates—favours market-leading reach into both hobbyist imaging and entry-level smart observatory segments.
- Synta Technology / Celestron OEM relationship (Taiwan): Remains an important industrial engine behind production scalability for advanced mounts and mainstream optics. Its role underscores how OEM partnerships influence time-to-market and cost position.
- Sky-Watcher (Taichung City): Balances performance optics (Esprit ED refractors, Skymax Maksutov lines) and respected mounts, targeting committed amateur astrophotographers who trade up as their interest deepens.
- Takahashi & Astro-Physics (Japan / USA): Represent the high-end optical tier, investing in fluorite apochromats and premium astrographs. These companies anchor the premium segment where optical excellence and brand reputation support higher margins.
- Explore Scientific & Vixen: Offer diversified portfolios—Dobsonians, refractors, eyepieces and mounts—appealing across visual and imaging use cases. Explore Scientific’s recent Sidara mount series highlights the ongoing investment in usability for serious amateurs.
- Bosma & Apertura: Drive affordability and volume in value tiers, keeping overall market growth accessible while pressuring margins at entry-level price points.
- Vaonis & ZWO Seestar: Signal the shift to “smart telescopes” with app-first imaging experiences and integrated sensor systems—an area of rapid consumer adoption that redefines the value chain.
Recent product launches across vendors during 2025–2026 are accelerating the shift toward hybrid propositions—optics + intelligence + service—that lower the technical barrier to deep-sky imaging while creating recurring revenue opportunities through software and cloud services.
Key dynamics and risk factors
- Standards & regulation: ISO/TC 172/SC 4 standardization work continues to refine terminology, test methods and requirements for direct-view optical systems; manufacturers should anticipate stricter conformance checks and plan certification timelines (next sessions scheduled in late 2026).
- Cost-pressure from specialized inputs: Precision optical components and skilled manufacturing labor keep unit costs elevated for premium segments; firms with better engineering-to-cost control will protect margins.
- Infrastructure constraints for ground-based installations: Dark-sky site availability and stable mounting systems increase total installation costs for higher-end ground installations—an important consideration for institutional buyers and specialized OEMs.
- Consumer behavior shift: Rapid adoption of smart, app-integrated telescopes reduces friction for newcomers and creates new monetization models—subscription services, image-processing toolchains, and educational content bundles.
- Public interest & macro tailwinds: Renewed public enthusiasm for space and astronomy campaigns (media, missions, education initiatives) sustains interest across hobbyist and institutional cohorts.
Strategic playbook for 2026 — prioritized moves
- For premium optics firms: Protect IP in optical formulation, expand limited-series high-margin SKUs, and monetize service and calibration packages for serious astrophotographers.
- For scale OEMs & mid-tier manufacturers: Invest in software partnerships and modular mounts that enable multiple customer journeys—visual observing, imaging, and automated remote operation.
- For value-oriented brands: Focus on improving perceived quality (bundled accessories, learning content) to reduce churn and capture first-time buyers who can migrate upmarket.
- For distributors and retailers: Reconfigure SKUs and training offerings to support demo-heavy selling and remote onboarding—key to converting interest into higher-ticket sales.
- For investors and M&A teams: Target capabilities that accelerate software and smart-hardware convergence, aftermarket service providers, and regional manufacturing capacity that de-risks lead times.
Why PW Consulting’s study is the go-to tool for 2026 planning
Our report combines rigorous top-down and bottom-up sizing, vendor-level intelligence, and a scenario-ready forecasting engine calibrated to observable adoption curves. It delivers tactical playbooks alongside strategic scenarios, enabling commercial, R&D, and corporate development teams to stress-test investment choices under realistic market evolutions. Critically, we package the work with downloadable financial models and an executive dashboard designed for board-level decision-making.
To preserve the utility of this briefing as a strategic film-trailer, we have intentionally withheld the full regional, type and application-level breakdowns, and the detailed company scorecards that drive our valuation and M&A guidance. Those tables, along with the workbook you can use to test your own assumptions, are available in the full report and subscriber portal.
Next step
If you are making budgetary, product, channel or M&A decisions in 2026, access to the full report and the accompanying financial models will materially reduce execution risk and increase your odds of capturing the growth exposed by the 7.15% forecast CAGR. Contact PW Consulting to obtain the full Astronomical Telescope Market study and the downloadable scenario model—so your 2026 strategy is built on both empirical rigor and practical playbooks.
For detailed analysis of this topic, please visit the official page: Astronomical Telescope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com