

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Laminate Flooring Market to Grow at 6.98% CAGR Through 2032
By pmarketresearch, 2026-07-22
Laminate Flooring Market — PW Consulting Strategic Preview (2026)
As businesses prepare strategy for 2026, the laminate flooring market presents a clear but nuanced growth story: resilient end-market demand, product innovation focused on water resistance and sustainability, and supply-chain dynamics that favor nimble manufacturers and well-capitalized integrators. PW Consulting’s new Laminate Flooring Market study (base year 2025, historical window 2020–2025, forecast period 2026–2032) synthesizes quantitative forecasting with actionable playbooks to help executives convert insight into competitive advantage.
Laminate Flooring Market
Why this study matters for 2026 decisions
- Macro trajectory: The global laminate flooring market expanded from approximately USD 1,300 million in 2020 to USD 1,700 million in 2025, and our forecast conservatively models continued expansion through 2032. At a compound annual growth rate of 6.98% across the forecast window, the market will materially increase addressable revenue for product innovation, channel investment, and M&A-enabled scale.
- Strategic inflection: Growth is accompanied by structural change — water-resistant formats, sustainability claims, and stricter emissions regulations are shifting specification criteria. These shifts convert modest market growth into opportunities for margin improvement and premium positioning.
- Decision immediacy: 2026 is a pivotal planning year. Playbooks developed now for product roadmaps, certification programs, and sourcing strategies will determine which players capture the higher-margin segments emerging over the next five years.
Market trajectory and what the headline numbers conceal
Headline figures tell part of the story: after recovering from pandemic-era volatility, the market reached a substantive scale by 2025 and is projected to continue a mid-single-digit expansion through 2032. But beneath that CAGR lies heterogeneity in product-by-application performance, differing channel economics between new-build and renovation demand, and cost exposure to key resin and fibreboard inputs.
Laminate Flooring Market
Two structural characteristics are essential for 2026 planning: first, the market remains moderately unconsolidated — the three largest firms control under a quarter of global shipments and the five largest under approximately one-third — creating space for both regional champions and specialist innovators. Second, product differentiation is increasingly driven by technology (waterproofing, core formulations) and non-product credentials (supply-chain traceability, low emissions), not solely price.
Laminate Flooring Market
Competitive landscape — what leaders are doing
Leading manufacturers are converging on several repeatable strategies: diversify waterproof collections, integrate child- and pet-friendly performance claims, and build climate-forward supply chains. The following synthesis highlights strategic positioning without revealing proprietary share splits:
- Mohawk Industries (Calhoun, GA): Investing in waterproof laminate lines with advanced locking systems and high-fidelity wood visuals. Strategy centers on scale-enabled distribution and cross-category bundling with other hard-surface products.
- Shaw Industries Group (Dalton, GA): Leveraging premium waterproof brands such as COREtec to defend higher-margin channel segments; emphasis on integrated technology for durability and ease of installation.
- Armstrong Flooring (Lancaster, PA): Positioning around low-emission, high-performance residential laminate options to capture environmentally conscious purchasers and specifiers.
- Mannington Mills (Salem, NJ): Focusing on family- and pet-friendly features (spill defense) and premium residential finishes to maintain category premiumization.
- Kronospan (Münster, Germany) and Swiss Krono Group (Menznau, Switzerland): European producers emphasizing high-quality substrate engineering, sustainable sourcing, and modern click systems to protect domestic markets from low-cost imports.
- Pergo (Stockholm) and Beaulieu (Waregem): Driving product durability narratives and design-forward collections for both residential and commercial projects.
- Tarkett (Paris): Articulating circular-economy strategies across flooring categories to appeal to large procurement contracts and public-sector tender requirements.
These players illustrate two enduring routes to advantage: scale-enabled cost leadership in core formats, and differentiated propositions built on performance characteristics plus sustainability certification.
Recent developments shaping 2026 strategies
- Late 2025 relaunches by European producers repositioned PVC-free and sustainable laminate ranges as tariff-avoiding, high-quality alternatives, signaling a re-acceleration in product innovation in Europe.
- Early-2026 trade shows and expos (including major U.S. and European events) highlighted mineral-core and hybrid core technologies alongside new installation techniques — an indicator that channel and installer acceptance is increasing.
- Industry associations published trend reports in early 2026 underscoring consumer preference for natural textures and sustainably produced panels; manufacturers who can credibly demonstrate low embodied impacts will gain specification advantages.
- Product updates from market incumbents expanded water-resistance performance claims (multi-hour resistance), reducing the functional gap between laminate and higher-priced alternative categories.
Supply-chain, materials and regulatory dynamics
Material and regulatory signals are among the highest-impact variables for 2026 strategies.
- Raw materials: Melamine-formaldehyde resins remain the primary high-pressure decorative top-layer material, delivering scratch and stain resistance. However, melamine pricing exhibited notable volatility in 2024 due to upstream inputs such as ammonia and carbon dioxide — an exposure that persisted in 2025 and requires active risk management through fixed contracts and alternative supplier qualification.
- Substrates: Wood fibreboards from sustainably managed forests remain the dominant substrate choice. Securing certified fibreboard capacity and forward commitments is a low-friction way to lock in both cost and sustainability narratives.
- Regulation and compliance: Emissions standards (TSCA Title VI, CARB Phase 2) and European standards (EN 13329 plus E05 formaldehyde limits) are non-negotiable for market access in major geographies. Compliance investment is not optional — it is a commercial prerequisite that affects product formulation, testing cadence, and time-to-market.
What PW Consulting’s report delivers — practical content for execution
Our full report is deliberately structured to move teams from insight to execution. Highlights include:
- Proprietary forecasting engine (2026–2032) with scenario analyses that stress-test demand under alternative macro and raw-material-cost paths.
- Competitive heatmaps and capability matrices that reveal where scale, technology, and certification create defendable positions (note: the public preview omits detailed regional split data to preserve subscriber value).
- Channel economics playbooks for retail, wholesale, and specification channels — including installation cost sensitivity, margin waterfalls, and SKU rationalization frameworks.
- Supplier risk-assessment toolkit covering resin and fibreboard supply; recommended contract structures and inventory strategies to mitigate price volatility.
- Regulatory compliance checklist and certification roadmap aligned to TSCA, CARB, and EN requirements, with implementation timelines and audit protocols.
- Sustainability KPIs and LCA templates to support green claims and procurement RFPs; guidance on communicating circular-economy initiatives to buyers and investors.
- M&A screening model and integration-playbook for roll-up strategies in fragmented regional markets, including indicative valuation corridors and synergies by target archetype.
- Product-innovation scorecards that quantify the commercial value of waterproof cores, click systems, and texture fidelity for specific channels.
How executives should use the preview to prioritize 2026 actions
For boards and executive teams, the immediate question is not whether the market grows — the numbers show it does — but how to capture disproportionate share of profit pools created by premiumization and sustainability demand. We recommend a three-track approach for 2026:
- Protect supply and margins: Secure medium-term contracts for melamine and fibreboard, diversify supplier base, and establish hedging or pricing pass-through mechanisms. Model margin sensitivity to ±20% swings in key resin costs as part of 2026 budgeting.
- Differentiate productively: Fast-track waterproof and low-emission SKUs for channels where consumers and specifiers will pay for verified performance. Invest in rapid certification and installer training programs to reduce time-to-revenue.
- Deploy capital selectively: Use M&A only where clear route-to-synergy exists (distribution, local production capacity, or proprietary technologies). Alternatively, consider JV or licensing deals in markets where regulatory entry costs are high.
Actionable questions our full report answers (excerpt)
- Which product R&D investments generate payback within 18 months under conservative adoption curves?
- How should channel mix evolve in 2026 to maximize margin while protecting volume growth?
- What is the quantified impact of stricter formaldehyde limits on legacy product lines and retrofit costs?
- Which acquisition targets or alliances unlock immediate access to certified substrates or waterproof-core technologies?
- How sensitive is overall profitability to raw-material price shocks and what operating levers reduce that sensitivity?
Conclusion — the strategic trade-offs for 2026
The laminate flooring market offers an attractive growth runway with the potential for targeted premiumization and improved profitability. But realizing that potential requires disciplined choices: prioritize supplier resilience, accelerate certification and installer-readiness for upgraded products, and align investment toward channels and geographies where differentiated claims are monetizable. PW Consulting’s complete Laminate Flooring Market study provides the quantitative rigor, competitor benchmarking, and execution tools to make those choices defensible. This preview demonstrates the nature of the opportunity while reserving the granular segmentation intelligence and regional/application-level breakouts for subscribers and clients — information that will materially affect tactical decisions and is best consumed with the full model in hand.
To access the full dataset, granular segment analyses, and actionable playbooks that underpin these conclusions, consult the complete PW Consulting Laminate Flooring Market report and accompanying decision-support toolkit.
For detailed analysis of this topic, please visit the official page: Laminate Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nail Clippers Market to Reach USD 2,117M by 2032 at 5.53% CAGR
By pmarketresearch, 2026-07-22
Nail Clippers Market — 2026 Strategic Briefing for Corporate Decision‑Makers
Executive summary
As companies prepare strategic plans for 2026, the Nail Clippers Market presents a quietly resilient opportunity shaped by steady consumer demand, product premiumization, and enduring brand equity tied to craftsmanship. Our base-year assessment (2025) places the global market at approximately USD 1,448 Million, following a consistent recovery from the 2020–2025 period. Looking forward to 2032, our forecast shows the market expanding toward the low‑billions at a compound annual growth rate (CAGR) of about 5.53% over the forecast window. These dynamics create a pragmatic environment for commercial initiatives — from SKU rationalization and brand repositioning to supply‑chain optimization and selective M&A — provided executives align short‑term tactics with medium‑term structural trends.
Nail Clippers Market
Why this research matters for 2026 planning
Two realities make the Nail Clippers Market strategically relevant in 2026: predictability and fragmentation. Predictability derives from resilient, repeat purchase behavior and product longevity; consumers continue to value corrosion‑resistant stainless steel, ergonomic designs, and mess‑mitigating features. Fragmentation is a double‑edged sword: while brand loyalty and regional craft reputations (e.g., heritage makers from Japan, Germany, Switzerland) sustain pricing power for premium players, overall market share is dispersed — the top three players account for roughly a quarter of value and the top five about thirty percent — leaving white space for focused challengers.
Nail Clippers Market
Market trajectory and modelling approach
Our modelling synthesizes historical performance (2020–2025) with forward scenario paths (2026–2032). The market grew from the low‑thousands in 2020 to approximately USD 1,448 Million in 2025, and our conservative base scenario projects continued expansion to around USD 2,117 Million by 2032. The modelling integrates unit consumption trends, ASP movements driven by premiumization and cost inflation, and channel shifts toward e‑commerce and specialty retail.
Nail Clippers Market
Practical implication: with a mid‑single‑digit CAGR, executives should prioritize initiatives that improve margin per unit and extend lifetime value rather than relying on volume growth alone. Examples include targeted premium SKUs, subscription or replacement blade programs, and value‑add services for professional channels.
Key strategic themes for 2026
- Premiumization and provenance sell: Demand for Japanese and German‑made tools remains strong among consumers who equate origin with durability and rust resistance. Positioning that emphasizes material quality, heritage manufacturing (e.g., Seki craftsmanship), and serviceability captures a pricing premium.
- Safety and accessibility features: Rising consumer interest in designs that reduce mess and improve safety for people with mobility issues is creating product innovation opportunities (e.g., enclosed clipping chambers, ergonomic levers, textured grips).
- Channel bifurcation: Mass retailers and general e‑commerce continue to move commoditized SKUs, while specialty retailers, professional salons, and gifting channels absorb higher‑margin, design‑led products. A two‑track go‑to‑market model (volume vs. curated premium) is increasingly necessary.
- Regulatory and travel considerations: Travel‑safety regulations (e.g., TSA allowances and checked‑baggage rules) and IP classification (trademark filings for hand‑operated clippers) are modest but real factors affecting packaging, point‑of‑sale messaging, and cross‑border distribution.
- Product lifecycle and replacement economics: Nail clippers have long replacement cycles, so monetizing aftermarket services (sharpening, replacement catchers, subscription packs) and bundling accessories helps extend revenue streams.
Competitive landscape — who matters and why
The market is a mix of heritage toolmakers, regionally strong manufacturers, and nimble specialists. Our review highlights several archetypal competitors that exemplify different winning strategies:
- KAI Corporation (Japan) — Known for Seki Magoroku lines that leverage traditional steelworking and premium finishing. Their playbook centers on provenance and craft credentials ( https://www.kai-group.com/).
- Green Bell Co., Ltd. (Japan) — Exports premium stainless designs with modelized SKUs positioned for global specialty channels ( https://greenbell.ne.jp/en/).
- Zwilling J.A. Henckels (Germany) — Converts its broader cutlery and tools reputation into differentiated clippers featuring ergonomic blades and nail‑catch functions ( https://www.zwilling.com/).
- Victor Inox AG (Switzerland) — Uses the Swiss Army Knife heritage to bundle compact, multi‑function clippers attractive to travel and gift buyers ( https://www.victorinox.com/).
- Industrial Tool & Die Co., Inc. (USA) — Differentiates with lifetime guarantees and patented mechanical features ( https://nomesnailclipper.com/).
- Regional specialists — Keiba Tool, Nghia Nippers, Wablade, Muji and several China‑based manufacturers each target niches from professional salon tools to minimal, travel‑friendly designs. Recent activity includes Keiba’s trade show participation at the Cologne International Hardware Fair (Feb 2026), indicating continued B2B market engagement.
Competitive takeaway: differentiation is achieved through craftsmanship narratives, patented convenience features, and channel‑specific SKUs rather than broad scale alone.
Report deliverables — what this study provides (operational, not just descriptive)
The full research package is intentionally operational. It includes:
- Integrated market model (history and forecast) with scenario sensitivity to ASP, raw‑material costs, and channel shifts.
- Buyer personas and use‑case maps for retail consumers, professional manicure/pedicure buyers, pet owners, and travel/gift segments.
- SKU and pricing ladders with margin impact analysis to inform assortment rationalization and private‑label opportunities.
- Go‑to‑market playbooks for premium vs. mass channels, including promotional calendars, retailer negotiation checklists, and digital merchandising tactics.
- Supplier and manufacturing heatmaps highlighting sourcing risk, lead times, and quality differentials by region and plant type.
- M&A screening framework and shortlist methodology for bolt‑on acquisitions, capability buys (e.g., patented catchers), and strategic partnerships.
- Regulatory and packaging checklist with travel‑safety considerations and IP filing implications for cross‑market expansion.
Note: segment‑level revenue tables and detailed region/application splits are purposefully excluded from this briefing to protect the research’s commercial value; the full datasets and interactive models are available in the complete report.
How leading teams should use this study in 2026
- Product portfolio strategy: Rebalance SKUs toward higher margin, proven premium propositions that leverage provenance, while pruning low‑turn SKUs in mass channels. Use our SKU ladder to simulate margin uplift and inventory turns.
- Channel optimization: Implement a dual distribution strategy: maximize reach in volume channels with a lean assortment, and deploy experiential, branded assortments in specialty or gifting channels to capture higher ASPs.
- Sourcing and resilience: Stress‑test supplier contracts against raw‑material cost swings and logistics disruption. Prioritize suppliers that can certify stainless grades and deliver consistent tolerances.
- Innovation pipeline: Invest in small, high‑value mechanical improvements (nail catcher systems, ergonomic levers) and service extensions (sharpening, replacement parts) where willingness‑to‑pay is demonstrable.
- M&A and partnerships: Use our screening criteria to evaluate targets that provide missing capabilities (patents, premium distribution, regional manufacturing) rather than merely top‑line scale.
- Regulatory compliance & packaging: Ensure product packaging clearly communicates travel rules and TSA guidance, and use trademark strategies for pet‑specific or hand‑operated categories where brand protection supports channel expansion.
Final notes and next steps
The Nail Clippers Market is not a high‑growth, headline sector; yet its predictability, combined with pockets of premium demand and low structural churn, makes it an attractive arena for margin accretion and capability plays. Our 2026‑focused analysis delivers practical decision tools — from SKU rationalization templates to M&A screeners — that help leaders convert a modest CAGR environment into meaningful commercial gains.
To unlock the full datasets, regional and application breakdowns, and the interactive forecasting model that support these recommendations, please consult the full report. We intentionally withheld the granular segment tables in this briefing to preserve their advisory value; the complete intelligence package contains those details and the underlying assumptions necessary for board‑level decision making.
Contact
PW Consulting’s Nail Clippers Market research is available for enterprise license and advisory engagement. Our team can provide scenario workshops, CSV extracts of the forecasting model, and tailored go‑to‑market playbooks to accelerate your 2026 initiatives.
For detailed analysis of this topic, please visit the official page: Nail Clippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Refrigeration Market to Reach USD 31.73 Billion by 2032
By pmarketresearch, 2026-07-22
Industrial Refrigeration Equipment Market: Strategic Preview for 2026 Decision-Making
Executive summary
PW Consulting’s latest market study on Industrial Refrigeration Equipment frames the competitive and regulatory inflection points that will shape capital allocation, procurement, and product strategy across 2026. The market has shown a steady recovery and structural growth from the pandemic trough: total industry revenues moved from USD 17.87 Billion in 2020 to USD 22.7 Billion in our 2025 base year, and our forecast projects a continuation of this expansion across 2026–2032 at a compound annual growth rate (CAGR) of 4.9%, culminating in an estimated USD 31.73 Billion by 2032. These headline numbers mask important pockets of opportunity and risk driven by refrigerant policy, equipment efficiency mandates, raw‑material inflation, and a rapid adoption curve for natural refrigerants and transcritical CO2 architectures.
Industrial Refrigeration Equipment Market
Why this preview matters for 2026 decisions
- Compliance is immediate and strategic: Regulatory changes effective in 2026 create mandatory technical transitions (not optional best practices). Companies must convert compliance timelines into procurement, retrofit, and training roadmaps to avoid disruption to production schedules and capex overruns.
- Technology choice is a multi‑year bet: Selection between ammonia, CO2 (including transcritical systems), and hybrid architectures will determine lifecycle cost, footprint, service model, and long‑term vendor dependence. The next 12–18 months are a critical window for pilot projects and staged rollouts to validate operational impacts.
- Supply‑chain stress elevates vendor risk: Tariffs and component bottlenecks have increased the cost and lead times for compressors, condensers, and structural materials. Sourcing strategies must move from transactional procurement to integrated supplier partnerships that embed inventory risk sharing, dual‑sourcing, and design for manufacturability.
- Energy efficiency policy changes drive ROI recalibrations: Department of Energy prioritization of compressor efficiency and retro‑commissioning incentives mean that energy savings assumptions used in financial models must be revisited. Projects justified on legacy payback windows may require re‑scoping to meet newer minimum performance baselines.
- Market structure favors scale and specialization: The market concentration metrics indicate room for consolidation alongside fragmented regional and niche specialists. Strategic M&A, JV and distribution alliances will accelerate capability acquisition—particularly for companies lacking CO2 or ammonia systems expertise.
Operational intelligence you can act on (what the full report contains)
- Proprietary market forecast model (2026–2032) with sensitivity scenarios tied to fuel prices, steel/aluminum tariffs, and refrigerant substitution curves.
- Buy‑side decision frameworks: staged retrofit versus full replacement matrices, CapEx/OpEx comparisons, and supplier scorecards keyed to uptime, service network density, and refrigerant lifecycle costs.
- Technology playbooks: practical guidance for selecting transcritical CO2, ammonia, or hybrid systems depending on ambient conditions, duty cycles, and site safety classifications.
- Regulatory impact models: compliance cost estimates, phased mitigation roadmaps, and documentation templates to accelerate permit approvals and insurance negotiation.
- Supply‑chain stress tests that map component lead times, tariff scenarios, and inventory hedging strategies to minimize schedule slippage.
- Competitive benchmarking and vendor selection tools—scorecards, negotiation playbooks, and partner ecosystem maps to support procurement and M&A diligence.
- Case studies and retrofit blueprints from industry pilots that illustrate real-world energy and cost outcomes across food, pharmaceutical, and industrial applications.
Competitive landscape — who matters and why
The industrial refrigeration supplier landscape combines global OEMs with engineering specialists and regional turnkey integrators. Market concentration is meaningful but not prohibitive: the top three players account for roughly 38% of the market and the top five about 46%, underscoring both the importance of scale and continued space for focused competitors.
Industrial Refrigeration Equipment Market
- Heatcraft Refrigeration Products (Nashville, TN) — A mature supplier of unit coolers, condensers and evaporators with deep channels into commercial and industrial fleets. Strengths include an extensive aftermarket and retrofit footprint that is attractive to food and cold‑storage operators seeking low‑disruption upgrades.
- Magna Industrial Refrigeration — Operating within the Heatcraft family, Magna emphasizes integrated industrial solutions and component breadth. Their presence at specialist industry forums signals a push toward consolidated solutions for larger cold‑chain projects.
- NDL Industries — Focused on natural refrigerant components, NDL’s stainless steel CO2 fittings and valves are a critical enabler for system integrity in transcritical CO2 deployments. Component specialists like NDL are becoming strategic partners in systems where material compatibility and reliability are non‑negotiable.
- Danfoss (Nordborg, Denmark) — A leader in transcritical CO2 system modules and condensing units. Their product range and control platforms make them a preferred OEM for customers seeking packaged CO2 solutions and a shorter path to regulatory compliance.
- Copeland (Bentonville, Arkansas) — Known for scroll compressor technologies and dynamic vapor injection designs that improve transcritical CO2 performance, Copeland’s strengths are product innovation and scale manufacturing that support large cold‑storage networks.
- Bock GmbH (Bochum, Germany) — A specialist in semi‑hermetic compressor platforms used across industrial refrigeration and process cooling. The firm’s engineering pedigree supports high‑duty, long‑service applications in pharmaceuticals and chemicals.
- Frigo Mekanik (Turkey) — A regional turnkey integrator delivering design, manufacturing, and installation services for project‑based customers. These types of firms often win retrofit and greenfield projects where local compliance and fast project delivery matter most.
Recent trade shows and conferences (AHR Expo 2026, IIAR Natural Refrigeration Conference, and regional HVACR events) reinforced this picture: suppliers showcased CO2 condensing units, advanced compressors with dynamic vapor injection, and stainless steel valve technology—indicating that natural refrigerant ecosystems are shifting from pilots to mainstream project pipelines.
Industrial Refrigeration Equipment Market
Regulatory and supply dynamics — reshaping the technical baseline
- Refrigerant policy acceleration: New regulatory thresholds that took effect in early 2026 require rapid phase‑out of high‑GWP HFCs in new industrial process chillers and tighten allowable GWP values for certain cold‑storage applications. This elevates conversion timelines and creates near‑term demand for compliant systems.
- Energy performance mandates: With industrial compressors prioritized under energy efficiency programs, performance thresholds are tightening. Design teams must account for both regulatory minimums and anticipated next‑round efficiency targets when specifying compressors and controls.
- Raw material pressure: Sustained tariffs on steel and aluminum have raised fabrication costs for structural frameworks and heat‑exchange components—pressures that feed directly into lead times and total installed cost.
- Standards update: Industry standards and safety codes have been refreshed; systems must now be validated against updated RETA and ISO guidance, increasing the documentation and testing burden for new installations.
Risk scenarios and prioritized responses for 2026
- Scenario A — Accelerated substitution: Rapid migration to CO2/ammonia driven by immediate enforcement. Recommended response: prioritize modular, factory‑assembled units that reduce onsite commissioning complexity and shorten time to revenue.
- Scenario B — Component scarcity and inflation: Longer lead times for compressors and structural elements. Recommended response: adopt long‑lead procurement, dual‑sourcing strategies, and standardized modular designs to simplify spares management.
- Scenario C — Energy regulation tightening: Stricter energy standards make retrofit the lower‑cost path to compliance for many operators. Recommended response: invest in retro‑commissioning and variable‑speed drives, and negotiate shared savings contracts with energy service providers.
How to use this preview and next steps
This article presents the strategic frame and the headline market trajectory you need to align board‑level decisions and 2026 capital plans. PW Consulting’s full market study delivers the granular segmentation, regional and application split analysis, and interactive financial models you need to translate strategic intent into procurement specs, pilot programs, and M&A screening lists. In keeping with our "trailer" approach, detailed splits by region, application and technology—plus vendor‑level share tables and project‑level case economics—are reserved for the full report and the subscriber portal where accompanying model files and scenario dashboards are available.
If your 2026 agenda includes compliance roadmaps, CapEx prioritization, vendor selection, or pursuit of acquisitions in the refrigeration value chain, this market study is designed to be the decision support backbone for those initiatives. PW Consulting’s industry team stands ready to convert the market-level insights in this preview into bespoke models, workshop facilitation, and transaction due diligence tailored to your portfolio or operations.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lawn Mower Market to Hit USD 325.35 Million by 2032 at 6.1% CAGR
By pmarketresearch, 2026-07-22
Lawn Mower Market — 2026 Strategic Preview
As companies prepare capital allocation, product roadmaps, and go-to-market plans for 2026, PW Consulting’s Lawn Mower Market study provides the macro context and the executable intelligence required to convert uncertainty into advantage. Built on a 2025 base year and a seven‑year forecast horizon (2026–2032), the market trajectory we model is driven by a 6.1% compound annual growth rate (CAGR). Our topline sizing shows the market expanding from roughly USD 215 million in 2025 toward an expected market materially larger by 2032—an environment that rewards disciplined portfolio prioritization and decisive operational moves.
Lawn Mower Market
Why 2026 Is an Inflection Year for Lawn Mower Manufacturers and Investors
-
Regulatory acceleration: 2025–2026 produced several regulatory touchpoints that change product compliance calculus. The U.S. Consumer Product Safety Commission (CPSC) continues to enforce and refine the Safety Standard for Walk‑Behind Power Lawn Mowers (16 CFR part 1205), increasing the importance of certified testing and documentation. Parallel standards—such as ANSI/OPEI B71.8—were reaffirmed, underscoring that safety and test-method conformity will be business‑critical rather than optional.
Lawn Mower Market -
Localized fossil‑fuel restrictions: Emerging subnational measures—exemplified by Colorado’s seasonal prohibition on certain small gasoline-powered equipment—create asymmetric demand windows and force manufacturers and rental fleets to balance internal combustion, hybrid, and battery strategies at a geographic level.
Lawn Mower Market -
Input‑cost and supply‑chain pressure: Steel and electronic component price volatility, as tracked by Producer Price Indexes, is compressing margins and lengthening supplier lead times. Manufacturers with proactive hedging, multi‑sourcing, and design‑for‑cost programs will retain advantaged margin profiles.
-
Technology inflection: Consumers and landscapers are accelerating adoption of battery power and robotics. Trade events such as the Equip Exposition scheduled for October 2026 will consolidate momentum behind new commercial-grade battery platforms and automation tools, creating channel windows for first‑mover advantage.
What the Full Report Delivers — Practical, Executable Intelligence
Our research translates market sizing and qualitative insight into decision-ready outputs. The report includes:
-
A validated market-sizing model (historical 2020–2025 and forward 2026–2032) and sensitivity scenarios that isolate demand drivers, input-cost variables, and regulation shocks.
-
Competitive benchmarking and value‑chain maps that position OEMs across product, channel, and service vectors—identifying where share gains are realistic and where consolidation risk is highest.
-
Commercial playbooks for product portfolio prioritization, dealer incentives, and aftermarket monetization—designed to be implementable within 6–18 months.
-
Supply‑chain stress‑tests and mitigation plans: components at risk, recommended alternative suppliers, and cost pass‑through strategies aligned to different pricing elasticities.
-
Regulatory compliance checklist and test‑lab partner network to accelerate certification for walk‑behind and battery platforms.
-
M&A and partnership screening matrices tailored to acquirers seeking market share, capability, or channel access.
To preserve strategic advantage, this preview intentionally omits the granular regional, type, and application splits that are included in the full report. Those segmented data tables, model workbooks, and downloadable dashboards are available on the source page.
Competitive Landscape — Who Matters and Why
The lawn mower market exhibits moderate concentration at the top: our concentration metrics indicate that the three largest players capture a substantial share of the industry, with the top five representing an even larger portion of demand. Within that structure, different companies occupy distinct strategic positions:
-
The Toro Company (Bloomington, Minnesota) — A leader in both commercial and residential zero‑turn and riding platforms. Toro’s depth in product breadth and dealer network makes it a natural contender for premium commercial accounts; its challenge is preserving margin as battery and automation components compress traditional value pools.
-
Deere & Company (Moline, Illinois) — Reputation for durable riding tractors and zero‑turns gives Deere strength in large‑acreage and municipal segments. Deere’s scale supports elevated R&D and warranty capabilities, positioning it to defend share as product complexity increases.
-
Husqvarna Group (Stockholm, Sweden) — A key player in robotic mowers and battery platforms, Husqvarna’s innovation pipeline in automation is an important bellwether for how quickly robotics will penetrate mainstream residential and light‑commercial use cases.
-
Stanley Black & Decker (New Britain, Connecticut) — Through brands such as Cub Cadet, the company leverages its industrial tool heritage to push battery and consumer product integration, focusing on homeowner ease‑of‑use and retail channel shelf presence.
-
Metalcraft of Mayville / Scag (Mayville, Wisconsin) — Niche commercial‑grade manufacturer known for heavy‑duty zero‑turns. Scag’s customer base values durability and serviceability—attributes that remain defensible even as electrification advances.
-
EGO Power+ (Naperville, Illinois) — Representative of high‑growth battery‑first entrants. EGO’s strategies around modular battery platforms and retail partnerships illustrate how disruptors can capture share without heavy legacy dealer networks.
Key Market Dynamics to Monitor in 2026
-
Electrification cadence: Track battery‑system total cost of ownership (TCO) parity and charging‑infrastructure developments that change replacement cycles.
-
Automation adoption curve: Robotic mowers move from early adopters to selected mainstream use cases tied to maintenance-cost savings and labor shortages in commercial landscaping.
-
Regulatory compliance costs: Ongoing CPSC activities and reaffirmed standards (ANSI/OPEI) mean manufacturers should budget for incremental testing and labeling expenditures.
-
Seasonal and localized fuel‑use bans: Jurisdictions restricting gasoline equipment during ozone seasons create micro‑markets that favor battery engineers and rental fleets with flexible fleets.
-
Supply‑chain resilience: Identify single‑source electronic subassemblies and steel exposures; implement alternate supplier qualification and lean inventory strategies to avoid margin erosion during raw material swings.
-
Channel economics: Dealers and national retailers will rethink stocking and financing terms to accommodate higher unit prices for battery/robotic platforms and new service revenue streams.
Scenario Playbooks for 2026 Executives
-
Base Case (Manage for Growth): Continue balanced investment in walk‑behind, ride‑on, and battery lines, focusing on margin retention through selective price increases and cost reductions. Prioritize compliance certification and dealer training to accelerate sell‑through of new platforms.
-
Electrification Sprint (Accelerated Battery Adoption): Shift R&D and capex toward modular battery ecosystems and rapid charger programs. Execute trade‑in promotions and subscription models to lower upfront barriers for commercial accounts. Consider partnerships with battery OEMs and energy service providers.
-
Regulatory Shock (Localized ICE Restrictions): Deploy temporary rental fleets and battery retrofit solutions in impacted jurisdictions. Use regulatory events to pilot robotic maintenance contracts that demonstrate lower emissions and simplified compliance for municipal buyers.
How PW Consulting Partners with Leadership Teams
Our engagements are structured to move from insight to impact within defined implementation cycles. Typical deliverables include:
-
Customizable market models and dashboards you can run internally to test pricing, regional demand, and regulation-scenario impacts.
-
Competitive heatmaps and capability assessments to identify white spaces for product introductions or bolt‑on acquisitions.
-
Supply‑chain roadmaps that reduce single‑supplier risk and improve margin resilience under commodity stress.
-
Dealer and service‑network optimization plans to monetize aftersales and subscription revenue streams.
-
M&A target shortlists and diligence playbooks calibrated to your strategic priorities: scale, technology, channel, or manufacturing footprint.
Next Steps — Using the Preview to Shape 2026 Decisions
Between now and the Equip Exposition in October 2026 and the regulatory cycles that will unfold, 2026 offers a compressed window to secure advantage. Market growth is real and measurable: with a mid‑single digit CAGR across the forecast window, winners will be those who pair portfolio clarity with operational discipline. If your organization is evaluating where to deploy R&D dollars, which channels to double down on, or whether to pursue inorganic growth to accelerate electrification or automation capabilities, the full PW Consulting Lawn Mower Market report provides the segmented models, competitive depth, and executable playbooks you need.
Access the complete study for the full segmented worksheets, downloadable data tables, and client‑ready slide decks that support board‑level decision making and 2026 implementation planning.
For detailed analysis of this topic, please visit the official page: Lawn Mower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Capecitabine Market to Reach USD 743.71M by 2032 with 6.01% CAGR
By pmarketresearch, 2026-07-22
Capecitabine Market — 2026 Strategic Outlook and Action Playbook
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our deep-dive Capecitabine Market study — designed specifically to inform boardroom decisions and commercial playbooks for 2026. This preview demonstrates the analytical depth and practical orientation of the full report while intentionally holding back granular segment-level tables and proprietary model outputs to encourage direct engagement with the source research.
Capecitabine Market
Market snapshot: where we stand and where we’re headed
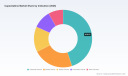
Our modelling, anchored on a 2025 base year with a historical window covering 2020–2025 and a forecast horizon extending through 2026–2032, identifies a resilient and growing oral fluoropyrimidine market. The global capecitabine market grew steadily through the early 2020s and reached approximately USD 494.3 Million in 2025. Under our central-case assumptions the market progresses to roughly USD 743.7 Million by 2032, reflecting a compound annual growth rate (CAGR) near 6.0% across the forecast period.
Capecitabine Market
That pace—solid for an established oncology oral cytotoxic—reflects a mix of enduring demand from core indications, incremental label and pathway changes, ongoing generic competition, and pockets of clinical innovation that can re-shape usage patterns. For 2026 decision-makers, the headline metrics mean two things: the market is big enough to matter for portfolio strategy and M&A, and dynamic enough that timing and execution will determine winners and laggards.
Capecitabine Market
Forces shaping the market through 2026
-
Regulatory and label dynamics. A pivotal development arrived in late 2025 with updated prescribing information for capecitabine under a regulatory renewal initiative. Changes to indications, dosing guidance and enhanced safety language—together with mandated genetic screening requirements for DPYD variants prior to initiation—are changing clinical workflows and payer expectations. These shifts raise the bar for both risk management and real-world evidence capture.
-
Clinical innovation and differentiation. Next-generation formulations and combination strategies are advancing in early development. Notably, early-phase data presented for a reformulated capecitabine candidate indicate higher active exposure and a potentially improved safety profile versus conventional monotherapy—an evidence pathway that, if confirmed, could tilt prescribing preferences and create premium pricing opportunities for differentiated products.
-
Supply chain and access fragility. The sector experienced tangible supply interruptions in several markets in 2025 due to sudden demand spikes and distribution incidents. These events exposed inventory and transportation risk vectors that can impact market share quickly. Market players that invest in multi-source procurement, serialization and cold-chain resilience will gain a competitive edge.
-
Competition and manufacturing footprint. The product ecosystem combines originator-branded incumbents with a broad field of generic manufacturers from emerging markets. This structure keeps price pressure and access variability high, even as branded and authorized generics try to sustain differentiated positioning through service, supply reliability and patent/family exclusivities elsewhere in the regimen portfolio.
Competitive landscape — strategic profiles and implications
-
Originator and stewardship: The originator brand remains the clinical reference in many oncology protocols and is central to managed care conversations. Its stewardship of label updates and pharmacovigilance sets the standard that generics and new entrants must address in their risk narratives.
-
Branded rights and strategic acquisitions: Transfers of commercialization rights in recent years have rebalanced regional marketing responsibilities. Companies that acquired marketing franchises have the immediate task of reconciling legacy supply contracts, local regulatory filings and physician engagement programs to sustain volumes post-transfer.
-
Large-volume generics and contract suppliers: Several established generic manufacturers supply capecitabine into major markets, often via partnerships with regional distributors. Their scale supports aggressive pricing strategies, but margins are vulnerable to procurement consolidation and SKU rationalization.
-
Specialist and regional players: A cohort of regional manufacturers and distributors target national tender channels and institutional procurement. These players can be agile in contract negotiations but are exposed to reputational risk if supply or quality issues arise.
Collectively, the competitive picture is best described as a market with multiple credible sources of supply and differentiated go-to-market propositions. Market concentration is not extreme; leadership depends on execution across regulatory compliance, evidence generation and supply continuity rather than on sheer scale alone.
Strategic imperatives for 2026
Executives must convert market dynamics into a short list of prioritized actions. Below are high-impact strategic moves that we recommend for organizations active or considering entry in the capecitabine ecosystem in 2026.
-
Embed DPYD testing into market access plans. Regulatory moves that mandate genetic screening change prescribing workflows and payer negotiations. Manufacturers should fund or subsidize testing programs in key launch geographies, craft lab partnerships, and build value dossiers that quantify avoided toxicity costs.
-
Differentiate via safety and adherence services. With oral chemotherapy, adherence programs, toxicity monitoring, and digital companion tools can sustain premium positioning. Investments here reduce clinical churn and create stickiness with oncology centers and payers.
-
Secure supply and diversify contracting. Short-term shortages underlined the need for redundant manufacturing and flexible logistics. Multisite manufacturing, safety stock strategies, and contractual SLAs with penalties are table stakes for risk-averse buyers.
-
Accelerate evidence generation for new formulations. If next-generation candidates show differentiated pharmacokinetics and safety, sponsors must design pragmatic trials and real-world studies that demonstrate meaningful clinical and economic benefit within two years to influence formulary decisions.
-
Targeted M&A and licensing posture. Given steady growth and pockets of differentiation, selective acquisitions—particularly of regional marketing franchises, formulation technology, or companion diagnostics—can be value-accretive. Use disciplined valuation frameworks that stress operational integration risks.
What PW Consulting’s full report delivers — operational tools for 2026
The full PW Consulting Capecitabine Market report is structured to be immediately usable by commercial, BD&L, regulatory and supply chain teams. Key deliverables include:
- Proprietary market model with annualized demand and revenue projections (2020–2032) and scenario toggles for regulatory and clinical outcomes.
- Regulatory impact matrix that quantifies the commercial effect of label revisions, genetic testing mandates and post-market safety measures.
- Competitive intelligence dossiers for key originators, franchise acquirers and major generic manufacturers, including go-to-market playbooks and supplier risk assessments.
- Launch and lifecycle playbooks: pricing, contracting templates, payer negotiation strategies, and sample commercial roll-out timelines by market archetype.
- Supply chain resilience map: multi-node sourcing options, lead-time optimization strategies, and contingency planning for shortage scenarios.
- M&A and licensing screening tool: scoring methodology to prioritize targets by strategic fit, access synergies, and integration complexity.
- Clinical evidence acceleration plan: recommended trial designs and real-world evidence endpoints to demonstrate safety, adherence and health-economic value for differentiated formulations.
How to use this research for decisive 2026 planning
-
For CEOs and Boards: Use the scenario outputs to stress-test near-term capital allocation decisions—especially for licensing, acquisition, or divestiture related to oncology oral therapies.
-
For Heads of Commercial and Market Access: Translate the regulatory impact matrix into a prioritized payer engagement plan and build a budget for DPYD testing enablement tied to launch milestones.
-
For R&D and Medical Affairs: Align clinical programs with payer evidence needs, accelerate pragmatic studies for any differentiated candidate, and pre-plan post-marketing safety surveillance aligned with updated prescribing guidelines.
-
For Supply Chain and Procurement: Implement the resilience checklist to reconfigure sourcing, raise visibility of inventory risks, and negotiate multi-year supply commitments with penalty clauses for non-delivery.
Closing: the strategic choice
In a market characterized by steady baseline demand, meaningful regulatory shifts, and selective pockets of clinical innovation, the differentiator for 2026 will be execution. Organizations that pair defensible clinical value propositions with robust access strategies, reliable supply, and evidence that addresses new safety and genetic-testing requirements will capture disproportionate value. Conversely, players that rely solely on low-cost supply without addressing these systemic shifts will face accelerated margin compression and contract volatility.
PW Consulting’s full Capecitabine Market study provides the models, playbooks and evidence prioritization frameworks required to navigate these inflection points. The analysis is built for action: from immediate payer negotiation toolkits to 36-month clinical and supply investments. To access the complete dataset, segment-level intelligence, and our proprietary scenario models—required to operationalize the recommendations summarized here—please consult the full report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Capecitabine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mobile Patient Lifts Market — Strategic Primer for 2026 Decision-Makers
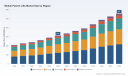
As health systems, medical device manufacturers, and investors prepare strategies for 2026, pragmatic clarity about the mobile patient lifts market becomes essential. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—reveals a market that has more than doubled in scale over a recent multi‑year window and is set to continue expanding at a steady mid‑single‑digit to high‑single‑digit pace (CAGR: 8.55%). Our forecast shows clear momentum into 2032, reflecting durable demand drivers and evolving care delivery models. This article summarizes the report’s strategic value and highlights the critical dynamics every executive should consider before committing capital, entering partnerships, or refining product roadmaps in 2026.
Mobile Patient Lifts Market
Why this market matters for 2026 strategy
Three structural shifts are converging to create a strategic inflection point. First, demographic pressure and the shift from acute‑only care to a mix of hospital, long‑term care, and in‑home services are increasing the absolute need for safe transfer solutions. Second, workforce constraints and caregiver safety imperatives are accelerating adoption of lifts and automation features that reduce manual handling. Third, reimbursement and regulatory frameworks—especially Durable Medical Equipment pathways and device safety requirements—are creating both barriers and predictable revenue channels for compliant products.
Mobile Patient Lifts Market
For boards and strategy teams, these trends translate into tangible questions: Should we prioritize product innovation or service expansion? Are there acquisition targets that accelerate access to high‑growth channels? What channel and pricing playbooks will secure durable margins as competition intensifies? Our study frames these decisions within quantified scenarios and executable options that are directly applicable to 2026 planning cycles.
Mobile Patient Lifts Market
Market scale and trajectory (strategic highlights)
- The market has shown a sustained upward trajectory into the 2025 base year and the forecast points to continued expansion through 2032, driven by both replacement cycles and incremental demand from emerging care settings.
- Projected compound annual growth of 8.55% over the forecast horizon signals an environment where disciplined investment in product development and commercial capability can deliver outsized returns—provided firms manage regulatory risk and service economics effectively.
- Our scenario work demonstrates that small shifts in reimbursement policy, or an accelerated migration to home and long‑term care settings, materially change revenue mix and margin profiles—making 2026 an important year to lock in strategic options.
What the PW Consulting report delivers (practical, actionable content)
- Market sizing and validated growth scenarios: a base case calibrated to recent demand signals plus downside and upside scenarios tied to reimbursement and care‑setting migration.
- Commercial playbooks: channel segmentation, distributor economics, rental vs. sale decision frameworks, and contracting approaches for hospitals and payers.
- Product and technology maps: feature‑level competitive benchmarking (portability, single‑caregiver ergonomics, sling ecosystems, antimicrobial finishes, and ceiling vs. floor lift tradeoffs) and a prioritized R&D roadmap.
- Regulatory and reimbursement intelligence: mapping of key codes and coverage pathways, regulatory compliance checklists, and a risk register related to field safety corrective actions and adverse event reporting.
- Supply chain and cost levers: analysis of raw material exposure (aluminum, steel), subassembly sourcing options, and operational design choices to improve margins and resilience.
- M&A and partnership targets: criteria‑based shortlists and valuation sensitivities for tuck‑ins that accelerate access to service capabilities, regional channels, or complementary product lines.
- Financial toolkit: an interactive model that allows executives to test pricing, channel mix, and service intensity scenarios and their impact on cash flow and ROI through 2032.
Competitive landscape — who matters and why
The mobile patient lifts market blends global OEMs with regional specialists. Market concentration is moderate, leaving room for focused competition and consolidation. Strategic positioning falls into several archetypes: scale incumbents with full systems and global service networks, product specialists with strong clinical credibility, and cost‑oriented manufacturers serving price‑sensitive channels.
- Hillrom and Baxter (through distribution relationships) bring global reach, integrated clinical workflows, and deep hospital relationships—advantages for selling higher‑specification systems into acute settings and bundled care solutions.
- Arjo is notable for sustained product innovation and a clinical safety emphasis; its recent next‑generation mobile floor lift demonstrates how maneuverability and ergonomics can be engineered into a visible commercial differentiator.
- Handicare, etac, Vancare, Winncare, and Invacare represent a cluster of product specialists that compete on portability, niche ergonomics (including bariatric solutions), and home‑care suitability—critical in a market where in‑home adoption is accelerating.
- Drive Medical and other value segment manufacturers focus on cost competitiveness and breadth of product line—important for distribution partners and rental fleets.
- Smaller innovators and service‑led players are increasingly focused on slings, digital enablement, and preventive maintenance services as means to create recurring revenue and higher switching costs.
For incumbents and new entrants alike, three competitive levers matter most: clinical evidence and safety, service and uptime economics, and integrated sling ecosystems. Winning combinations pair robust clinical outcomes with contracts that lower total cost of care for payers and providers.
Regulatory, reimbursement and operational dynamics to watch
- Reimbursement: Durable Medical Equipment pathways and established HCPCS codes create an explicit route to reimbursement in major markets, but coding nuances and local payor rules can yield significant variations in unit economics. Strategic teams must model country‑level coverage sensitivity in 2026 planning cycles.
- Regulation and safety: Compliance with device safety guidance and vigilance around adverse event reporting remain non‑negotiable. Field safety corrective actions can impose material operational and reputational costs; proactive post‑market surveillance and robust training programs reduce this exposure.
- Materials and manufacturing: Aluminum and steel frames dominate, while antimicrobial coatings and durable finishes are increasingly table stakes for institutional buyers. Supply‑chain continuity for these inputs and the ability to scale subassembly are core operational considerations.
- Labor and ergonomics: Features that enable single‑caregiver operation (dynamic positioning aids, quick‑connect spreaders) not only improve safety but also reduce long‑term labor costs for buyers—an important persuasive sales argument to resource‑constrained providers.
Strategic implications and recommended plays for 2026
Based on our synthesis, executives should prioritize three categories of moves in 2026: defend core channels, build recurring revenue, and selectively invest in innovation that shortens the time to clinical value.
- Defend and deepen acute care relationships: use integrated bundles (lift systems plus training and service) to protect margins and create switching costs. Invest in clinical studies that quantify reductions in caregiver injury and patient falls—these are high‑value proof points for procurement committees.
- Scale home and long‑term care offerings: create lighter, modular product tiers and develop rental/recurring service models to capture the accelerating shift to non‑acute settings without sacrificing unit economics.
- Operational resilience: diversify subassembly suppliers for key aluminum and steel components, and adopt lean manufacturing tactics to preserve margin in the face of raw‑material volatility.
- Explore bolt‑on M&A for service capabilities: targets that add field engineering, spare‑parts logistics, or digital predictive maintenance capabilities accelerate the transition to higher-margin recurring revenue.
- Regulatory and reimbursement hedges: invest in coding expertise and payer engagement to accelerate coverage in high‑growth channels; maintain rigorous post‑market surveillance programs to mitigate recall and corrective action risk.
Near‑term monitoring and decision checkpoints
- Monitor payer policy updates and coding reinterpretations that could alter reimbursement flows.
- Track MAUDE and other adverse‑event signals closely; early detection of trending issues allows preemptive field actions rather than reactive recalls.
- Evaluate product launches and supplier moves from key competitors—new mobility features or sling innovations often indicate shifting buyer expectations that should inform 2026 R&D prioritization.
Closing — the value of this study for your 2026 planning
PW Consulting’s Mobile Patient Lifts market study packages market scale, scenario analysis, competitive intelligence, regulatory mapping, and a transaction‑grade financial model into a single decision‑ready deliverable. It is crafted to move beyond descriptive insight toward prescriptive actions—ideal for executive teams preparing 2026 budgets, M&A pipelines, or new product investment approvals.
This article provides a strategic preview of the report’s themes and implications. For the detailed segment breakdowns, full company scorecards, pricing benchmarks, and the interactive financial model—intended to support board‑level and investor decisions—we invite you to consult the source report page where the complete intelligence is available.
For detailed analysis of this topic, please visit the official page: Mobile Patient Lifts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pomegranate Market Poised to Reach USD 341.8M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-22
Pomegranate Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to introduce our latest Pomegranate Market research — a focused, action-oriented dossier designed for executives making consequential decisions in 2026. This introduction highlights the strategic value of the full report, illustrates how the market is evolving, and identifies the practical levers executives should consider. In line with our “trailer” approach, I will show the depth and rigor of our analysis while intentionally withholding the granular segment tables and proprietary datapoints that are available in the full study.
Pomegranate Market
Why this study matters in 2026
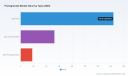
The pomegranate sector is no longer a niche botanical curiosity. Between 2020 and 2025 the global pomegranate market expanded from a modest base and reached a materially larger size by our 2025 base year, demonstrating resilience through a period of supply shocks and shifting consumer demand. PW Consulting’s modeled baseline shows a clear recovery and an accelerated growth trajectory into the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 6.8%. By 2032 the market is projected to be markedly larger than the 2025 base, signaling commercial opportunities across upstream production, ingredient supply, branded products, and value-added processing.
Pomegranate Market
For corporate strategists, this numeric story validates two concurrent strategic conclusions: (1) the market has moved beyond ‘early growth’ into structural expansion, and (2) growth is heterogeneous — concentrated where companies adopt productivity, sustainability, and premiumization strategies. The consequence is simple: 2026 is a decision year. Firms that adjust sourcing, capital allocation, and product strategy now will capture outsized share as the category scales.
Pomegranate Market
Market trajectory and what it reveals
-
Historical context: our analysis maps the 2020–2025 period showing an initial expansion, a short-term dip as supply and logistics adjusted, and a recovery into 2024–2025. The trajectory into 2026 and beyond is upward and predictable under multiple demand scenarios.
-
Forecast signal: using a transparent scenario framework, we project continued expansion through 2032 at a 6.8% CAGR. This is driven by rising consumer interest in functional ingredients, growth in processed forms for beverages and nutraceuticals, and investments in higher-density cultivation systems.
-
Market structure: concentration metrics point to a fragmented market. The three- and five-firm concentration ratios are moderate, indicating ample room for scale players, roll-ups, and premium-brand strategies without immediate monopolistic barriers.
Practical strategic implications for 2026 decision-making
-
Sourcing and supply resilience: India remains the dominant global production base for raw pomegranates and raw materials. For buyers and processors, a dual-track procurement playbook is essential: secure long-term contracts with large, reliable suppliers in established production geographies while developing secondary sources to hedge climate and regulatory risk.
-
Product and channel segmentation: consumer-facing firms should accelerate premium and functional formulations (e.g., cold-pressed juices, arils for fresh-pack, extracts for nutraceuticals). Processors and ingredient suppliers should prioritize product specifications that enable entry into high-margin channels: ingredient traceability, organic certification, and clear functional claims.
-
Capital investment and orchard productivity: recent agronomy research and field trials highlighted in our study show that irrigation intensity and scheduling materially affect yield, quality, and unit costs. Investors in cultivation should model orchard returns under updated evapotranspiration-based irrigation regimes and high-density planting systems before committing capital.
-
Labor and mechanization trade-offs: labor-intensive practices (pruning, multi-stage harvesting) comprise a major share of operating expenses in developed-culture orchards. Companies must balance mechanization investments against higher labor inputs and consider contract models that shift certain labor risks to co-ops or service providers.
-
Sustainability as commercial advantage: water-use efficiency improvements and demonstrable reductions in production footprint are rapidly becoming purchase criteria for B2B customers and retail buyers. Firms that can credibly demonstrate improved water productivity and reduced post-harvest loss will unlock preferred supplier status.
-
M&A and consolidation opportunities: given the market’s fragmentation, there is a clear runway for strategic acquisitions to secure raw material, expand processing capacity, or add branded products. M&A strategies should prioritize complementary capabilities (e.g., vertical integration, processing technology, certified organic supply).
Competitive landscape: what the full report reveals
PW Consulting’s competitive analysis synthesizes company-level strategy, capability maps, and a risk/reward assessment for market incumbents and challengers. Among the firms we profile, a few strategic archetypes stand out:
-
Vertically integrated brand-grower-processors: Firms that control the value chain — from orchard to shelf — occupy a defensible position for quality control, provenance storytelling, and margin capture. These players leverage proprietary orchards, branded marketing, and value-added processing to command premium pricing in key retail and foodservice channels.
-
Specialist processors and premium juicers: Companies focused on organic, cold-pressed, or craft juice products target health-conscious consumers and foodservice operators. Their competitive edge lies in niche positioning and premium margin capture, but they remain sensitive to raw-material price swings.
-
Bulk ingredient suppliers and exporters: These firms supply paste, concentrate, and bulk pulp to downstream processors and food ingredient buyers. Their value proposition centers on scale, logistical reliability, and export capabilities, particularly from major producing countries.
Our profiles assess each major player’s strengths and vulnerabilities — from orchard control and product portfolio to geographic exposure and branding sophistication — and provide playbooks for potential partners, acquirers, and competitors. The report includes company-level strategy maps and scenario-based valuations that practitioners can apply immediately to M&A screening or vendor selection.
Recent developments that materially affect strategy
-
Water and yield research: field-level studies in key producing regions demonstrated that optimized irrigation scheduling can improve fruit quality and water productivity while lowering costs. This has direct implications for production economics and for sustainability reporting — both central to commercial negotiations and capital allocation.
-
Operational cost structure: in established orchard systems, pruning and harvesting labor constitute a dominant piece of annual operational cost. Firms should run sensitivity analyses on labor inflation and mechanization capex when modeling long-term unit economics.
-
Production footprint expansion: evidence of cultivated-area expansion in certain European markets shows that high-density systems and targeted cultivar selection can mature quickly into meaningful regional supply. Buyers and processors should re-evaluate near-market sourcing strategies to capture freshness and reduce logistics costs.
What the PW Consulting report delivers (practical contents)
The full PW Consulting study is built as a decision-support toolkit for 2026. It contains:
-
Top-down and bottom-up market sizing and validated forecasting (2026–2032) with scenario toggles and sensitivity runs.
-
Supply-chain risk maps with supplier scorecards and contingency pathways for sourcing continuity.
-
Operational playbooks for orchard productivity (irrigation, high-density planting, mechanization thresholds) that translate agronomic insights into financial scenarios.
-
Commercial playbooks for branded and ingredient businesses, including go-to-market roadmaps, margin models, and channel segmentation tactics.
-
M&A screening templates, valuation benchmarks, and integration checklists tailored to the pomegranate value chain.
-
Regulatory and sustainability risk assessments, with metrics and KPIs for water productivity, certification pathways, and supply-traceability programs.
-
An interactive data appendix (available to subscribers) with downloadable models, forecasting inputs, and a competitive database for direct scenario-building.
How to use this study in your 2026 planning cycle
-
For strategy teams: use the report to stress-test portfolio choices — which SKUs to scale, which geographies to prioritize, and when to pursue vertical integration vs. distributor partnerships.
-
For operations and procurement: apply the orchard productivity modules and supplier-risk maps to renegotiate contracts and to optimize inventory buffers.
-
For M&A and corporate development: screen targets against our consolidation playbook and run the included valuation templates to size accretive acquisitions.
-
For sustainability officers: adopt the water-use and traceability KPIs to align procurement with customer ESG requirements and to advance cost-saving initiatives in water-constrained regions.
Why PW Consulting’s approach is uniquely actionable
We combine agronomy-informed operational modeling with consumer and trade-channel economics. That fusion matters: pomegranate value is created at the orchard and realized at retail and ingredient markets. Our research links field-level productivity (irrigation regimes, planting density, labor inputs) to unit-cost curves and to pricing scenarios at the ingredient and finished-product level. This end-to-end alignment makes the report immediately usable in board-level capital allocation, procurement renegotiations, and commercial planning.
Next steps and access
This brief is intended to demonstrate the practical, decision-ready insights contained in the full Pomegranate Market report while preserving the proprietary datasets and segment-level forecasts that provide competitive advantage. To access the complete dataset, interactive dashboards, and the full suite of company profiles and modeling tools, please visit our report page — where you can obtain subscription access, sample extracts, or a tailored briefing with our team.
In 2026, the pomegranate market is a clear example where agronomy, sustainability, and smart commercialization intersect. Companies that translate the evidence — not just the anecdotes — into decisive action will lead. PW Consulting’s full report is designed to make that translation straightforward and defensible.
— PW Consulting, Senior Strategy Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Pomegranate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fasteners Market to Reach USD 135.3 Billion by 2032 (4.3% CAGR)
By pmarketresearch, 2026-07-22
Fasteners Market — 2026 Strategic Preview
Executive summary
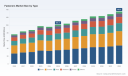
As capital planners, procurement leaders, and corporate strategists prepare for 2026, the global fasteners market presents a mix of steady expansion and sharply reshaped risk vectors. Our PW Consulting baseline positions the industry at USD 101.1 Billion in the 2025 base year, rising from a pandemic-era trough and tracking to an anticipated USD 135.3 Billion by 2032 under a 4.3% compound annual growth rate for the 2026–2032 forecast window. The historical arc (from roughly USD 76.5 Billion in 2020 to the 2025 base) reflects a rebound driven by resumed industrial activity, reconstruction projects and selective electrification and aerospace restocking—yet it is a market increasingly governed by raw-material policy, regulation and targeted technology adoption.
Fasteners Market
Why this research matters for 2026 decision-making
Fasteners are small parts with outsized strategic impact. For manufacturers and OEMs, performance and cost of joints determine product safety, warranty exposure, and downstream service economics. For distributors and aftermarket specialists, inventory turns and service differentiation define margin pools. For private equity and corporate development teams, fastener platforms offer attractive cash conversion and industrial adjacency but require granular exposure management to metal pricing, tariff regimes and certification pathways.
Fasteners Market
- Procurement and sourcing: Understand total-cost-of-ownership drivers beyond spot price—surface treatments, pretensioning requirements, and logistics lead times are often the dominant cost elements for structural and aerospace programs.
- Manufacturing footprint: Tariff and regulatory shifts now make nearshoring and controlled domestic capacity more than a cost exercise; they are risk-mitigation levers against trade disruptions and quota shocks.
- Product strategy: Differentiated fasteners (high-strength, specialty alloys, engineered plastics, pre-tensioned systems) command premium economics and are where OEMs concentrate performance and compliance requirements.
Market dynamics shaping 2026 strategy
Several concurrent drivers are reframing competitive advantage.
Fasteners Market
- Material dominance and cost sensitivity: Metal-based fasteners remain the backbone of the industry. Steel in particular is still the primary backbone material across most structural and industrial applications—which means movements in steel and aluminum markets rapidly transmit to manufacturer margins and pricing strategies.
- Trade and tariff shocks: Regulatory retrenchment has materially altered trade calculus. Notably, the restoration of Section 232 tariffs (25% on steel and aluminum imports effective March 2025) has increased import-sensitive input costs and elevated the value of domestic capacity. In addition, targeted tariffs applied in 2025 to fasteners from specific origins have created sourcing dislocations that persist into 2026.
- Regulatory engineering requirements: Code changes and standards updates are creating new product specifications. Recent amendments in major markets have mandated friction-grip and pretensioned solutions for high-rise and seismic applications, pushing demand toward higher-grade, certified products and associated inspection services.
- Technology and material substitution: Advances in polymeric engineered fasteners, high-strength aluminum alloys and manufacturing methods (including cold forming, precision machining and additive techniques) are enabling lighter, corrosion-resistant solutions—especially in automotive and aerospace where weight savings or electromagnetic compatibility matter.
- Channel evolution: Distribution is bifurcating into high-volume commodities and value-added service offerings. Companies that pair inventory with engineering support, vendor-managed inventory and digital replenishment capture outsized share of wallet.
Competitive landscape — who matters and how
The fasteners market sits in a state of moderate concentration: the top three companies account for roughly one-third of global industry revenue, while the top five control about half. That structure creates a competitive dynamic where specialized engineering firms, large distributors and verticalized OEM suppliers each pursue differentiated value propositions.
- Würth Group (Germany) — Broad portfolio strength across industrial and construction channels; excels in combined product-service offerings and field sales coverage.
- LISI Group (France) — Focus on high-value aerospace and automotive fasteners with deep engineering and certification capabilities.
- Nifco Inc (Japan) — Leader in engineered plastics and injection-molded fastening systems, a profile that aligns with automotive lightweighting trends.
- MW Industries (United States) — Precision springs and specialty machined fasteners for aerospace and high-reliability industrial customers.
- Hilti Corporation (Liechtenstein) — Professional fastening systems and tools; converts product sales into recurring service and consumables revenue.
- Illinois Tool Works, Stanley Black & Decker, Fastenal — Large-scale manufacturers and distributors with strong channel networks, aftermarket reach and manufacturing diversity.
- Arconic, Howmet, Bulten, Bossard, SFS Group and others — Each occupies strategic niches: aluminum fasteners; aerospace engineered components; high-strength automotive fasteners; and logistics/assembly services respectively.
These firms are not only competing on unit price but also on certification pathways, engineering services, logistics models and aftersales. Recent strategic activity—product launches, M&A and consolidation of European distribution capabilities—underscores a market that rewards scale in logistics and niche expertise in product development.
Recent developments and what they signal
- Product innovation remains first-order. Examples from 2025–2026 show suppliers launching faster-installation systems and next-generation geometries that materially reduce labor or enable new assembly tolerances—signals that time-to-install and ease-of-use are becoming purchase criteria alongside mechanical performance.
- M&A activity is targeted and capability-driven. Acquisitions announced in late 2025 expanded aerospace portfolios and strengthened direct-market access in Europe—moves that accelerate market penetration and create cross-selling opportunities for higher-margin, certified products.
- Distribution consolidation is continuing. European trading and specialist tool acquisitions suggest the winning distributors will bundle inventory with engineering and onsite services to defend margins.
What the full PW Consulting report delivers (practical, actionable content)
Our full Fasteners Market study is structured as a decision-support toolkit for 2026. Highlights include:
- Proprietary, bottom-up market sizing and a calibrated forecast model (2026–2032) that links demand to end-market activity and regulatory adoption curves.
- Price and input-cost sensitivity models that quantify the pass-through impact of steel and aluminum price moves, and the effects of tariffs and quotas on landed cost.
- Supplier and channel scorecards, including capability matrices, certification footprints, and service offerings—designed for targeted supplier rationalization and negotiations.
- Regulatory scenario planning with practical compliance pathways for structural, seismic and aerospace specifications—critical for long-lead OEM contracts and public-sector tenders.
- M&A screening dossiers and synergy-estimation templates for acquirers seeking bolt-on or platform plays.
- Go-to-market playbooks for distributors and manufacturers: SKU rationalization, VMI pilots, digital replenishment architecture and aftermarket monetization.
- Customizable dashboards (by request) to stress-test client-specific exposure to tariff regimes, material inflation, and demand slippage.
Note: this preview deliberately omits the detailed segmentation tables (type, application and regional shares) and the granular numerical splits that drive our models. Those proprietary tables and the underlying assumptions are available in the full report and accompanying datasets.
Tactical playbook — recommended 90-day moves for executives
- Map your true exposure: Commission a spend-and-specification audit that links every fastener SKU to supplier, country of origin and price index. Use it to quantify tariff and steel-price exposure over a 12–24 month horizon.
- Fast-track certification pipelines: For structural and aerospace programs, prioritize capacity and supplier relationships that can deliver certified pre-tensioned and friction-grip solutions; certification delays are a material program risk.
- Pursue dual-sourcing and nearshoring selectively: For high-volume commodity lines, volume economics may favor scale; for critical or regulated items, localized capacity mitigates geopolitical risk.
- Invest in distribution services: If you are a distributor, pilot VMI and engineering-as-a-service bundles that lock in OEM program access and reduce price elasticity.
- Evaluate tuck-ins for capability, not inventory: Bolt-on acquisitions that add engineering certification, surface-treatment capability or direct OEM access are higher-value than pure SKU roll-ups.
How PW Consulting can support your 2026 agenda
Our research is designed to be a working instrument — not just a static report. Clients can request scenario workshops, integrate our model into their ERP/strategic-planning tools, or commission bespoke supplier diligence and M&A screening. If your team needs a rapid-risk dashboard or a tailored sourcing playbook informed by tariff and standards scenarios, we provide accelerated engagements with deliverables aligned to procurement and corporate development timelines.
Closing — the strategic imperative
In 2026 the fasteners market will reward strategic clarity: companies that translate engineering requirements and regulatory changes into procurement discipline and product differentiation will capture the best margins. The global market’s move from a crisis-recovery phase into a policy- and standards-driven growth path means decisions made this year—about sourcing, certification and capability investments—will determine competitive position for the remainder of the decade.
For the complete dataset, proprietary segmentation breakdowns, and interactive forecasting tools referenced in this preview, access the full PW Consulting Fasteners Market report. Our clients gain not only numbers but a playbook for converting market intelligence into defensible, measurable strategy.
For detailed analysis of this topic, please visit the official page: Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com