

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Refrigeration Market to Reach USD 31.73 Billion by 2032

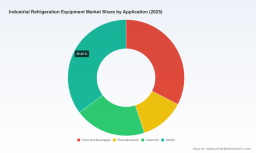
Industrial Refrigeration Equipment Market: Strategic Preview for 2026 Decision-Making
Executive summary
PW Consulting’s latest market study on Industrial Refrigeration Equipment frames the competitive and regulatory inflection points that will shape capital allocation, procurement, and product strategy across 2026. The market has shown a steady recovery and structural growth from the pandemic trough: total industry revenues moved from USD 17.87 Billion in 2020 to USD 22.7 Billion in our 2025 base year, and our forecast projects a continuation of this expansion across 2026–2032 at a compound annual growth rate (CAGR) of 4.9%, culminating in an estimated USD 31.73 Billion by 2032. These headline numbers mask important pockets of opportunity and risk driven by refrigerant policy, equipment efficiency mandates, raw‑material inflation, and a rapid adoption curve for natural refrigerants and transcritical CO2 architectures.
Industrial Refrigeration Equipment Market
Why this preview matters for 2026 decisions
- Compliance is immediate and strategic: Regulatory changes effective in 2026 create mandatory technical transitions (not optional best practices). Companies must convert compliance timelines into procurement, retrofit, and training roadmaps to avoid disruption to production schedules and capex overruns.
- Technology choice is a multi‑year bet: Selection between ammonia, CO2 (including transcritical systems), and hybrid architectures will determine lifecycle cost, footprint, service model, and long‑term vendor dependence. The next 12–18 months are a critical window for pilot projects and staged rollouts to validate operational impacts.
- Supply‑chain stress elevates vendor risk: Tariffs and component bottlenecks have increased the cost and lead times for compressors, condensers, and structural materials. Sourcing strategies must move from transactional procurement to integrated supplier partnerships that embed inventory risk sharing, dual‑sourcing, and design for manufacturability.
- Energy efficiency policy changes drive ROI recalibrations: Department of Energy prioritization of compressor efficiency and retro‑commissioning incentives mean that energy savings assumptions used in financial models must be revisited. Projects justified on legacy payback windows may require re‑scoping to meet newer minimum performance baselines.
- Market structure favors scale and specialization: The market concentration metrics indicate room for consolidation alongside fragmented regional and niche specialists. Strategic M&A, JV and distribution alliances will accelerate capability acquisition—particularly for companies lacking CO2 or ammonia systems expertise.
Operational intelligence you can act on (what the full report contains)
- Proprietary market forecast model (2026–2032) with sensitivity scenarios tied to fuel prices, steel/aluminum tariffs, and refrigerant substitution curves.
- Buy‑side decision frameworks: staged retrofit versus full replacement matrices, CapEx/OpEx comparisons, and supplier scorecards keyed to uptime, service network density, and refrigerant lifecycle costs.
- Technology playbooks: practical guidance for selecting transcritical CO2, ammonia, or hybrid systems depending on ambient conditions, duty cycles, and site safety classifications.
- Regulatory impact models: compliance cost estimates, phased mitigation roadmaps, and documentation templates to accelerate permit approvals and insurance negotiation.
- Supply‑chain stress tests that map component lead times, tariff scenarios, and inventory hedging strategies to minimize schedule slippage.
- Competitive benchmarking and vendor selection tools—scorecards, negotiation playbooks, and partner ecosystem maps to support procurement and M&A diligence.
- Case studies and retrofit blueprints from industry pilots that illustrate real-world energy and cost outcomes across food, pharmaceutical, and industrial applications.
Competitive landscape — who matters and why
The industrial refrigeration supplier landscape combines global OEMs with engineering specialists and regional turnkey integrators. Market concentration is meaningful but not prohibitive: the top three players account for roughly 38% of the market and the top five about 46%, underscoring both the importance of scale and continued space for focused competitors.
Industrial Refrigeration Equipment Market
- Heatcraft Refrigeration Products (Nashville, TN) — A mature supplier of unit coolers, condensers and evaporators with deep channels into commercial and industrial fleets. Strengths include an extensive aftermarket and retrofit footprint that is attractive to food and cold‑storage operators seeking low‑disruption upgrades.
- Magna Industrial Refrigeration — Operating within the Heatcraft family, Magna emphasizes integrated industrial solutions and component breadth. Their presence at specialist industry forums signals a push toward consolidated solutions for larger cold‑chain projects.
- NDL Industries — Focused on natural refrigerant components, NDL’s stainless steel CO2 fittings and valves are a critical enabler for system integrity in transcritical CO2 deployments. Component specialists like NDL are becoming strategic partners in systems where material compatibility and reliability are non‑negotiable.
- Danfoss (Nordborg, Denmark) — A leader in transcritical CO2 system modules and condensing units. Their product range and control platforms make them a preferred OEM for customers seeking packaged CO2 solutions and a shorter path to regulatory compliance.
- Copeland (Bentonville, Arkansas) — Known for scroll compressor technologies and dynamic vapor injection designs that improve transcritical CO2 performance, Copeland’s strengths are product innovation and scale manufacturing that support large cold‑storage networks.
- Bock GmbH (Bochum, Germany) — A specialist in semi‑hermetic compressor platforms used across industrial refrigeration and process cooling. The firm’s engineering pedigree supports high‑duty, long‑service applications in pharmaceuticals and chemicals.
- Frigo Mekanik (Turkey) — A regional turnkey integrator delivering design, manufacturing, and installation services for project‑based customers. These types of firms often win retrofit and greenfield projects where local compliance and fast project delivery matter most.
Recent trade shows and conferences (AHR Expo 2026, IIAR Natural Refrigeration Conference, and regional HVACR events) reinforced this picture: suppliers showcased CO2 condensing units, advanced compressors with dynamic vapor injection, and stainless steel valve technology—indicating that natural refrigerant ecosystems are shifting from pilots to mainstream project pipelines.
Industrial Refrigeration Equipment Market
Regulatory and supply dynamics — reshaping the technical baseline
- Refrigerant policy acceleration: New regulatory thresholds that took effect in early 2026 require rapid phase‑out of high‑GWP HFCs in new industrial process chillers and tighten allowable GWP values for certain cold‑storage applications. This elevates conversion timelines and creates near‑term demand for compliant systems.
- Energy performance mandates: With industrial compressors prioritized under energy efficiency programs, performance thresholds are tightening. Design teams must account for both regulatory minimums and anticipated next‑round efficiency targets when specifying compressors and controls.
- Raw material pressure: Sustained tariffs on steel and aluminum have raised fabrication costs for structural frameworks and heat‑exchange components—pressures that feed directly into lead times and total installed cost.
- Standards update: Industry standards and safety codes have been refreshed; systems must now be validated against updated RETA and ISO guidance, increasing the documentation and testing burden for new installations.
Risk scenarios and prioritized responses for 2026
- Scenario A — Accelerated substitution: Rapid migration to CO2/ammonia driven by immediate enforcement. Recommended response: prioritize modular, factory‑assembled units that reduce onsite commissioning complexity and shorten time to revenue.
- Scenario B — Component scarcity and inflation: Longer lead times for compressors and structural elements. Recommended response: adopt long‑lead procurement, dual‑sourcing strategies, and standardized modular designs to simplify spares management.
- Scenario C — Energy regulation tightening: Stricter energy standards make retrofit the lower‑cost path to compliance for many operators. Recommended response: invest in retro‑commissioning and variable‑speed drives, and negotiate shared savings contracts with energy service providers.
How to use this preview and next steps
This article presents the strategic frame and the headline market trajectory you need to align board‑level decisions and 2026 capital plans. PW Consulting’s full market study delivers the granular segmentation, regional and application split analysis, and interactive financial models you need to translate strategic intent into procurement specs, pilot programs, and M&A screening lists. In keeping with our "trailer" approach, detailed splits by region, application and technology—plus vendor‑level share tables and project‑level case economics—are reserved for the full report and the subscriber portal where accompanying model files and scenario dashboards are available.
If your 2026 agenda includes compliance roadmaps, CapEx prioritization, vendor selection, or pursuit of acquisitions in the refrigeration value chain, this market study is designed to be the decision support backbone for those initiatives. PW Consulting’s industry team stands ready to convert the market-level insights in this preview into bespoke models, workshop facilitation, and transaction due diligence tailored to your portfolio or operations.
For detailed analysis of this topic, please visit the official page: Industrial Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com