

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laminate Flooring Market to Grow at 6.98% CAGR Through 2032

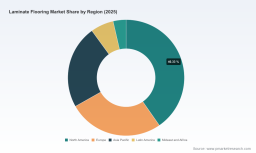
Laminate Flooring Market — PW Consulting Strategic Preview (2026)
As businesses prepare strategy for 2026, the laminate flooring market presents a clear but nuanced growth story: resilient end-market demand, product innovation focused on water resistance and sustainability, and supply-chain dynamics that favor nimble manufacturers and well-capitalized integrators. PW Consulting’s new Laminate Flooring Market study (base year 2025, historical window 2020–2025, forecast period 2026–2032) synthesizes quantitative forecasting with actionable playbooks to help executives convert insight into competitive advantage.
Laminate Flooring Market
Why this study matters for 2026 decisions
- Macro trajectory: The global laminate flooring market expanded from approximately USD 1,300 million in 2020 to USD 1,700 million in 2025, and our forecast conservatively models continued expansion through 2032. At a compound annual growth rate of 6.98% across the forecast window, the market will materially increase addressable revenue for product innovation, channel investment, and M&A-enabled scale.
- Strategic inflection: Growth is accompanied by structural change — water-resistant formats, sustainability claims, and stricter emissions regulations are shifting specification criteria. These shifts convert modest market growth into opportunities for margin improvement and premium positioning.
- Decision immediacy: 2026 is a pivotal planning year. Playbooks developed now for product roadmaps, certification programs, and sourcing strategies will determine which players capture the higher-margin segments emerging over the next five years.
Market trajectory and what the headline numbers conceal
Headline figures tell part of the story: after recovering from pandemic-era volatility, the market reached a substantive scale by 2025 and is projected to continue a mid-single-digit expansion through 2032. But beneath that CAGR lies heterogeneity in product-by-application performance, differing channel economics between new-build and renovation demand, and cost exposure to key resin and fibreboard inputs.
Laminate Flooring Market
Two structural characteristics are essential for 2026 planning: first, the market remains moderately unconsolidated — the three largest firms control under a quarter of global shipments and the five largest under approximately one-third — creating space for both regional champions and specialist innovators. Second, product differentiation is increasingly driven by technology (waterproofing, core formulations) and non-product credentials (supply-chain traceability, low emissions), not solely price.
Laminate Flooring Market
Competitive landscape — what leaders are doing
Leading manufacturers are converging on several repeatable strategies: diversify waterproof collections, integrate child- and pet-friendly performance claims, and build climate-forward supply chains. The following synthesis highlights strategic positioning without revealing proprietary share splits:
- Mohawk Industries (Calhoun, GA): Investing in waterproof laminate lines with advanced locking systems and high-fidelity wood visuals. Strategy centers on scale-enabled distribution and cross-category bundling with other hard-surface products.
- Shaw Industries Group (Dalton, GA): Leveraging premium waterproof brands such as COREtec to defend higher-margin channel segments; emphasis on integrated technology for durability and ease of installation.
- Armstrong Flooring (Lancaster, PA): Positioning around low-emission, high-performance residential laminate options to capture environmentally conscious purchasers and specifiers.
- Mannington Mills (Salem, NJ): Focusing on family- and pet-friendly features (spill defense) and premium residential finishes to maintain category premiumization.
- Kronospan (Münster, Germany) and Swiss Krono Group (Menznau, Switzerland): European producers emphasizing high-quality substrate engineering, sustainable sourcing, and modern click systems to protect domestic markets from low-cost imports.
- Pergo (Stockholm) and Beaulieu (Waregem): Driving product durability narratives and design-forward collections for both residential and commercial projects.
- Tarkett (Paris): Articulating circular-economy strategies across flooring categories to appeal to large procurement contracts and public-sector tender requirements.
These players illustrate two enduring routes to advantage: scale-enabled cost leadership in core formats, and differentiated propositions built on performance characteristics plus sustainability certification.
Recent developments shaping 2026 strategies
- Late 2025 relaunches by European producers repositioned PVC-free and sustainable laminate ranges as tariff-avoiding, high-quality alternatives, signaling a re-acceleration in product innovation in Europe.
- Early-2026 trade shows and expos (including major U.S. and European events) highlighted mineral-core and hybrid core technologies alongside new installation techniques — an indicator that channel and installer acceptance is increasing.
- Industry associations published trend reports in early 2026 underscoring consumer preference for natural textures and sustainably produced panels; manufacturers who can credibly demonstrate low embodied impacts will gain specification advantages.
- Product updates from market incumbents expanded water-resistance performance claims (multi-hour resistance), reducing the functional gap between laminate and higher-priced alternative categories.
Supply-chain, materials and regulatory dynamics
Material and regulatory signals are among the highest-impact variables for 2026 strategies.
- Raw materials: Melamine-formaldehyde resins remain the primary high-pressure decorative top-layer material, delivering scratch and stain resistance. However, melamine pricing exhibited notable volatility in 2024 due to upstream inputs such as ammonia and carbon dioxide — an exposure that persisted in 2025 and requires active risk management through fixed contracts and alternative supplier qualification.
- Substrates: Wood fibreboards from sustainably managed forests remain the dominant substrate choice. Securing certified fibreboard capacity and forward commitments is a low-friction way to lock in both cost and sustainability narratives.
- Regulation and compliance: Emissions standards (TSCA Title VI, CARB Phase 2) and European standards (EN 13329 plus E05 formaldehyde limits) are non-negotiable for market access in major geographies. Compliance investment is not optional — it is a commercial prerequisite that affects product formulation, testing cadence, and time-to-market.
What PW Consulting’s report delivers — practical content for execution
Our full report is deliberately structured to move teams from insight to execution. Highlights include:
- Proprietary forecasting engine (2026–2032) with scenario analyses that stress-test demand under alternative macro and raw-material-cost paths.
- Competitive heatmaps and capability matrices that reveal where scale, technology, and certification create defendable positions (note: the public preview omits detailed regional split data to preserve subscriber value).
- Channel economics playbooks for retail, wholesale, and specification channels — including installation cost sensitivity, margin waterfalls, and SKU rationalization frameworks.
- Supplier risk-assessment toolkit covering resin and fibreboard supply; recommended contract structures and inventory strategies to mitigate price volatility.
- Regulatory compliance checklist and certification roadmap aligned to TSCA, CARB, and EN requirements, with implementation timelines and audit protocols.
- Sustainability KPIs and LCA templates to support green claims and procurement RFPs; guidance on communicating circular-economy initiatives to buyers and investors.
- M&A screening model and integration-playbook for roll-up strategies in fragmented regional markets, including indicative valuation corridors and synergies by target archetype.
- Product-innovation scorecards that quantify the commercial value of waterproof cores, click systems, and texture fidelity for specific channels.
How executives should use the preview to prioritize 2026 actions
For boards and executive teams, the immediate question is not whether the market grows — the numbers show it does — but how to capture disproportionate share of profit pools created by premiumization and sustainability demand. We recommend a three-track approach for 2026:
- Protect supply and margins: Secure medium-term contracts for melamine and fibreboard, diversify supplier base, and establish hedging or pricing pass-through mechanisms. Model margin sensitivity to ±20% swings in key resin costs as part of 2026 budgeting.
- Differentiate productively: Fast-track waterproof and low-emission SKUs for channels where consumers and specifiers will pay for verified performance. Invest in rapid certification and installer training programs to reduce time-to-revenue.
- Deploy capital selectively: Use M&A only where clear route-to-synergy exists (distribution, local production capacity, or proprietary technologies). Alternatively, consider JV or licensing deals in markets where regulatory entry costs are high.
Actionable questions our full report answers (excerpt)
- Which product R&D investments generate payback within 18 months under conservative adoption curves?
- How should channel mix evolve in 2026 to maximize margin while protecting volume growth?
- What is the quantified impact of stricter formaldehyde limits on legacy product lines and retrofit costs?
- Which acquisition targets or alliances unlock immediate access to certified substrates or waterproof-core technologies?
- How sensitive is overall profitability to raw-material price shocks and what operating levers reduce that sensitivity?
Conclusion — the strategic trade-offs for 2026
The laminate flooring market offers an attractive growth runway with the potential for targeted premiumization and improved profitability. But realizing that potential requires disciplined choices: prioritize supplier resilience, accelerate certification and installer-readiness for upgraded products, and align investment toward channels and geographies where differentiated claims are monetizable. PW Consulting’s complete Laminate Flooring Market study provides the quantitative rigor, competitor benchmarking, and execution tools to make those choices defensible. This preview demonstrates the nature of the opportunity while reserving the granular segmentation intelligence and regional/application-level breakouts for subscribers and clients — information that will materially affect tactical decisions and is best consumed with the full model in hand.
To access the full dataset, granular segment analyses, and actionable playbooks that underpin these conclusions, consult the complete PW Consulting Laminate Flooring Market report and accompanying decision-support toolkit.
For detailed analysis of this topic, please visit the official page: Laminate Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com