

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fasteners Market to Reach USD 135.3 Billion by 2032 (4.3% CAGR)

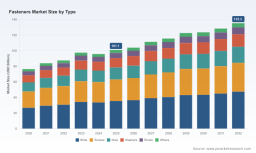
Fasteners Market — 2026 Strategic Preview
Executive summary
As capital planners, procurement leaders, and corporate strategists prepare for 2026, the global fasteners market presents a mix of steady expansion and sharply reshaped risk vectors. Our PW Consulting baseline positions the industry at USD 101.1 Billion in the 2025 base year, rising from a pandemic-era trough and tracking to an anticipated USD 135.3 Billion by 2032 under a 4.3% compound annual growth rate for the 2026–2032 forecast window. The historical arc (from roughly USD 76.5 Billion in 2020 to the 2025 base) reflects a rebound driven by resumed industrial activity, reconstruction projects and selective electrification and aerospace restocking—yet it is a market increasingly governed by raw-material policy, regulation and targeted technology adoption.
Fasteners Market
Why this research matters for 2026 decision-making
Fasteners are small parts with outsized strategic impact. For manufacturers and OEMs, performance and cost of joints determine product safety, warranty exposure, and downstream service economics. For distributors and aftermarket specialists, inventory turns and service differentiation define margin pools. For private equity and corporate development teams, fastener platforms offer attractive cash conversion and industrial adjacency but require granular exposure management to metal pricing, tariff regimes and certification pathways.
Fasteners Market
- Procurement and sourcing: Understand total-cost-of-ownership drivers beyond spot price—surface treatments, pretensioning requirements, and logistics lead times are often the dominant cost elements for structural and aerospace programs.
- Manufacturing footprint: Tariff and regulatory shifts now make nearshoring and controlled domestic capacity more than a cost exercise; they are risk-mitigation levers against trade disruptions and quota shocks.
- Product strategy: Differentiated fasteners (high-strength, specialty alloys, engineered plastics, pre-tensioned systems) command premium economics and are where OEMs concentrate performance and compliance requirements.
Market dynamics shaping 2026 strategy
Several concurrent drivers are reframing competitive advantage.
Fasteners Market
- Material dominance and cost sensitivity: Metal-based fasteners remain the backbone of the industry. Steel in particular is still the primary backbone material across most structural and industrial applications—which means movements in steel and aluminum markets rapidly transmit to manufacturer margins and pricing strategies.
- Trade and tariff shocks: Regulatory retrenchment has materially altered trade calculus. Notably, the restoration of Section 232 tariffs (25% on steel and aluminum imports effective March 2025) has increased import-sensitive input costs and elevated the value of domestic capacity. In addition, targeted tariffs applied in 2025 to fasteners from specific origins have created sourcing dislocations that persist into 2026.
- Regulatory engineering requirements: Code changes and standards updates are creating new product specifications. Recent amendments in major markets have mandated friction-grip and pretensioned solutions for high-rise and seismic applications, pushing demand toward higher-grade, certified products and associated inspection services.
- Technology and material substitution: Advances in polymeric engineered fasteners, high-strength aluminum alloys and manufacturing methods (including cold forming, precision machining and additive techniques) are enabling lighter, corrosion-resistant solutions—especially in automotive and aerospace where weight savings or electromagnetic compatibility matter.
- Channel evolution: Distribution is bifurcating into high-volume commodities and value-added service offerings. Companies that pair inventory with engineering support, vendor-managed inventory and digital replenishment capture outsized share of wallet.
Competitive landscape — who matters and how
The fasteners market sits in a state of moderate concentration: the top three companies account for roughly one-third of global industry revenue, while the top five control about half. That structure creates a competitive dynamic where specialized engineering firms, large distributors and verticalized OEM suppliers each pursue differentiated value propositions.
- Würth Group (Germany) — Broad portfolio strength across industrial and construction channels; excels in combined product-service offerings and field sales coverage.
- LISI Group (France) — Focus on high-value aerospace and automotive fasteners with deep engineering and certification capabilities.
- Nifco Inc (Japan) — Leader in engineered plastics and injection-molded fastening systems, a profile that aligns with automotive lightweighting trends.
- MW Industries (United States) — Precision springs and specialty machined fasteners for aerospace and high-reliability industrial customers.
- Hilti Corporation (Liechtenstein) — Professional fastening systems and tools; converts product sales into recurring service and consumables revenue.
- Illinois Tool Works, Stanley Black & Decker, Fastenal — Large-scale manufacturers and distributors with strong channel networks, aftermarket reach and manufacturing diversity.
- Arconic, Howmet, Bulten, Bossard, SFS Group and others — Each occupies strategic niches: aluminum fasteners; aerospace engineered components; high-strength automotive fasteners; and logistics/assembly services respectively.
These firms are not only competing on unit price but also on certification pathways, engineering services, logistics models and aftersales. Recent strategic activity—product launches, M&A and consolidation of European distribution capabilities—underscores a market that rewards scale in logistics and niche expertise in product development.
Recent developments and what they signal
- Product innovation remains first-order. Examples from 2025–2026 show suppliers launching faster-installation systems and next-generation geometries that materially reduce labor or enable new assembly tolerances—signals that time-to-install and ease-of-use are becoming purchase criteria alongside mechanical performance.
- M&A activity is targeted and capability-driven. Acquisitions announced in late 2025 expanded aerospace portfolios and strengthened direct-market access in Europe—moves that accelerate market penetration and create cross-selling opportunities for higher-margin, certified products.
- Distribution consolidation is continuing. European trading and specialist tool acquisitions suggest the winning distributors will bundle inventory with engineering and onsite services to defend margins.
What the full PW Consulting report delivers (practical, actionable content)
Our full Fasteners Market study is structured as a decision-support toolkit for 2026. Highlights include:
- Proprietary, bottom-up market sizing and a calibrated forecast model (2026–2032) that links demand to end-market activity and regulatory adoption curves.
- Price and input-cost sensitivity models that quantify the pass-through impact of steel and aluminum price moves, and the effects of tariffs and quotas on landed cost.
- Supplier and channel scorecards, including capability matrices, certification footprints, and service offerings—designed for targeted supplier rationalization and negotiations.
- Regulatory scenario planning with practical compliance pathways for structural, seismic and aerospace specifications—critical for long-lead OEM contracts and public-sector tenders.
- M&A screening dossiers and synergy-estimation templates for acquirers seeking bolt-on or platform plays.
- Go-to-market playbooks for distributors and manufacturers: SKU rationalization, VMI pilots, digital replenishment architecture and aftermarket monetization.
- Customizable dashboards (by request) to stress-test client-specific exposure to tariff regimes, material inflation, and demand slippage.
Note: this preview deliberately omits the detailed segmentation tables (type, application and regional shares) and the granular numerical splits that drive our models. Those proprietary tables and the underlying assumptions are available in the full report and accompanying datasets.
Tactical playbook — recommended 90-day moves for executives
- Map your true exposure: Commission a spend-and-specification audit that links every fastener SKU to supplier, country of origin and price index. Use it to quantify tariff and steel-price exposure over a 12–24 month horizon.
- Fast-track certification pipelines: For structural and aerospace programs, prioritize capacity and supplier relationships that can deliver certified pre-tensioned and friction-grip solutions; certification delays are a material program risk.
- Pursue dual-sourcing and nearshoring selectively: For high-volume commodity lines, volume economics may favor scale; for critical or regulated items, localized capacity mitigates geopolitical risk.
- Invest in distribution services: If you are a distributor, pilot VMI and engineering-as-a-service bundles that lock in OEM program access and reduce price elasticity.
- Evaluate tuck-ins for capability, not inventory: Bolt-on acquisitions that add engineering certification, surface-treatment capability or direct OEM access are higher-value than pure SKU roll-ups.
How PW Consulting can support your 2026 agenda
Our research is designed to be a working instrument — not just a static report. Clients can request scenario workshops, integrate our model into their ERP/strategic-planning tools, or commission bespoke supplier diligence and M&A screening. If your team needs a rapid-risk dashboard or a tailored sourcing playbook informed by tariff and standards scenarios, we provide accelerated engagements with deliverables aligned to procurement and corporate development timelines.
Closing — the strategic imperative
In 2026 the fasteners market will reward strategic clarity: companies that translate engineering requirements and regulatory changes into procurement discipline and product differentiation will capture the best margins. The global market’s move from a crisis-recovery phase into a policy- and standards-driven growth path means decisions made this year—about sourcing, certification and capability investments—will determine competitive position for the remainder of the decade.
For the complete dataset, proprietary segmentation breakdowns, and interactive forecasting tools referenced in this preview, access the full PW Consulting Fasteners Market report. Our clients gain not only numbers but a playbook for converting market intelligence into defensible, measurable strategy.
For detailed analysis of this topic, please visit the official page: Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com