

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lawn Mower Market to Hit USD 325.35 Million by 2032 at 6.1% CAGR

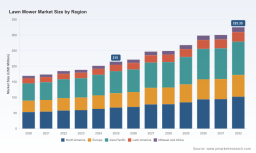
Lawn Mower Market — 2026 Strategic Preview
As companies prepare capital allocation, product roadmaps, and go-to-market plans for 2026, PW Consulting’s Lawn Mower Market study provides the macro context and the executable intelligence required to convert uncertainty into advantage. Built on a 2025 base year and a seven‑year forecast horizon (2026–2032), the market trajectory we model is driven by a 6.1% compound annual growth rate (CAGR). Our topline sizing shows the market expanding from roughly USD 215 million in 2025 toward an expected market materially larger by 2032—an environment that rewards disciplined portfolio prioritization and decisive operational moves.
Lawn Mower Market
Why 2026 Is an Inflection Year for Lawn Mower Manufacturers and Investors
-
Regulatory acceleration: 2025–2026 produced several regulatory touchpoints that change product compliance calculus. The U.S. Consumer Product Safety Commission (CPSC) continues to enforce and refine the Safety Standard for Walk‑Behind Power Lawn Mowers (16 CFR part 1205), increasing the importance of certified testing and documentation. Parallel standards—such as ANSI/OPEI B71.8—were reaffirmed, underscoring that safety and test-method conformity will be business‑critical rather than optional.
Lawn Mower Market -
Localized fossil‑fuel restrictions: Emerging subnational measures—exemplified by Colorado’s seasonal prohibition on certain small gasoline-powered equipment—create asymmetric demand windows and force manufacturers and rental fleets to balance internal combustion, hybrid, and battery strategies at a geographic level.
Lawn Mower Market -
Input‑cost and supply‑chain pressure: Steel and electronic component price volatility, as tracked by Producer Price Indexes, is compressing margins and lengthening supplier lead times. Manufacturers with proactive hedging, multi‑sourcing, and design‑for‑cost programs will retain advantaged margin profiles.
-
Technology inflection: Consumers and landscapers are accelerating adoption of battery power and robotics. Trade events such as the Equip Exposition scheduled for October 2026 will consolidate momentum behind new commercial-grade battery platforms and automation tools, creating channel windows for first‑mover advantage.
What the Full Report Delivers — Practical, Executable Intelligence
Our research translates market sizing and qualitative insight into decision-ready outputs. The report includes:
-
A validated market-sizing model (historical 2020–2025 and forward 2026–2032) and sensitivity scenarios that isolate demand drivers, input-cost variables, and regulation shocks.
-
Competitive benchmarking and value‑chain maps that position OEMs across product, channel, and service vectors—identifying where share gains are realistic and where consolidation risk is highest.
-
Commercial playbooks for product portfolio prioritization, dealer incentives, and aftermarket monetization—designed to be implementable within 6–18 months.
-
Supply‑chain stress‑tests and mitigation plans: components at risk, recommended alternative suppliers, and cost pass‑through strategies aligned to different pricing elasticities.
-
Regulatory compliance checklist and test‑lab partner network to accelerate certification for walk‑behind and battery platforms.
-
M&A and partnership screening matrices tailored to acquirers seeking market share, capability, or channel access.
To preserve strategic advantage, this preview intentionally omits the granular regional, type, and application splits that are included in the full report. Those segmented data tables, model workbooks, and downloadable dashboards are available on the source page.
Competitive Landscape — Who Matters and Why
The lawn mower market exhibits moderate concentration at the top: our concentration metrics indicate that the three largest players capture a substantial share of the industry, with the top five representing an even larger portion of demand. Within that structure, different companies occupy distinct strategic positions:
-
The Toro Company (Bloomington, Minnesota) — A leader in both commercial and residential zero‑turn and riding platforms. Toro’s depth in product breadth and dealer network makes it a natural contender for premium commercial accounts; its challenge is preserving margin as battery and automation components compress traditional value pools.
-
Deere & Company (Moline, Illinois) — Reputation for durable riding tractors and zero‑turns gives Deere strength in large‑acreage and municipal segments. Deere’s scale supports elevated R&D and warranty capabilities, positioning it to defend share as product complexity increases.
-
Husqvarna Group (Stockholm, Sweden) — A key player in robotic mowers and battery platforms, Husqvarna’s innovation pipeline in automation is an important bellwether for how quickly robotics will penetrate mainstream residential and light‑commercial use cases.
-
Stanley Black & Decker (New Britain, Connecticut) — Through brands such as Cub Cadet, the company leverages its industrial tool heritage to push battery and consumer product integration, focusing on homeowner ease‑of‑use and retail channel shelf presence.
-
Metalcraft of Mayville / Scag (Mayville, Wisconsin) — Niche commercial‑grade manufacturer known for heavy‑duty zero‑turns. Scag’s customer base values durability and serviceability—attributes that remain defensible even as electrification advances.
-
EGO Power+ (Naperville, Illinois) — Representative of high‑growth battery‑first entrants. EGO’s strategies around modular battery platforms and retail partnerships illustrate how disruptors can capture share without heavy legacy dealer networks.
Key Market Dynamics to Monitor in 2026
-
Electrification cadence: Track battery‑system total cost of ownership (TCO) parity and charging‑infrastructure developments that change replacement cycles.
-
Automation adoption curve: Robotic mowers move from early adopters to selected mainstream use cases tied to maintenance-cost savings and labor shortages in commercial landscaping.
-
Regulatory compliance costs: Ongoing CPSC activities and reaffirmed standards (ANSI/OPEI) mean manufacturers should budget for incremental testing and labeling expenditures.
-
Seasonal and localized fuel‑use bans: Jurisdictions restricting gasoline equipment during ozone seasons create micro‑markets that favor battery engineers and rental fleets with flexible fleets.
-
Supply‑chain resilience: Identify single‑source electronic subassemblies and steel exposures; implement alternate supplier qualification and lean inventory strategies to avoid margin erosion during raw material swings.
-
Channel economics: Dealers and national retailers will rethink stocking and financing terms to accommodate higher unit prices for battery/robotic platforms and new service revenue streams.
Scenario Playbooks for 2026 Executives
-
Base Case (Manage for Growth): Continue balanced investment in walk‑behind, ride‑on, and battery lines, focusing on margin retention through selective price increases and cost reductions. Prioritize compliance certification and dealer training to accelerate sell‑through of new platforms.
-
Electrification Sprint (Accelerated Battery Adoption): Shift R&D and capex toward modular battery ecosystems and rapid charger programs. Execute trade‑in promotions and subscription models to lower upfront barriers for commercial accounts. Consider partnerships with battery OEMs and energy service providers.
-
Regulatory Shock (Localized ICE Restrictions): Deploy temporary rental fleets and battery retrofit solutions in impacted jurisdictions. Use regulatory events to pilot robotic maintenance contracts that demonstrate lower emissions and simplified compliance for municipal buyers.
How PW Consulting Partners with Leadership Teams
Our engagements are structured to move from insight to impact within defined implementation cycles. Typical deliverables include:
-
Customizable market models and dashboards you can run internally to test pricing, regional demand, and regulation-scenario impacts.
-
Competitive heatmaps and capability assessments to identify white spaces for product introductions or bolt‑on acquisitions.
-
Supply‑chain roadmaps that reduce single‑supplier risk and improve margin resilience under commodity stress.
-
Dealer and service‑network optimization plans to monetize aftersales and subscription revenue streams.
-
M&A target shortlists and diligence playbooks calibrated to your strategic priorities: scale, technology, channel, or manufacturing footprint.
Next Steps — Using the Preview to Shape 2026 Decisions
Between now and the Equip Exposition in October 2026 and the regulatory cycles that will unfold, 2026 offers a compressed window to secure advantage. Market growth is real and measurable: with a mid‑single digit CAGR across the forecast window, winners will be those who pair portfolio clarity with operational discipline. If your organization is evaluating where to deploy R&D dollars, which channels to double down on, or whether to pursue inorganic growth to accelerate electrification or automation capabilities, the full PW Consulting Lawn Mower Market report provides the segmented models, competitive depth, and executable playbooks you need.
Access the complete study for the full segmented worksheets, downloadable data tables, and client‑ready slide decks that support board‑level decision making and 2026 implementation planning.
For detailed analysis of this topic, please visit the official page: Lawn Mower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com