

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Bollards Market 2026: Strategic Briefing for Executive Decision-Making
As PW Consulting’s senior industry analyst, I present a concise yet incisive orientation to our full Bollards Market research — a report calibrated to inform executive strategy through 2026 and beyond. The global bollards market, at a 2025 base-year valuation measured in USD Million, is demonstrating durable expansion with a compound annual growth rate (CAGR) of 7.95% across the 2026–2032 forecast window. This momentum reflects urban densification, rising perimeter-security spend, and renewed public-space design priorities. What follows is the high-level strategic framing you need to prioritize investments and actions this year; the full report contains the granular segmentation, figures, and modeling that will support execution decisions.
Bollards Market
Why this report matters for 2026 decisions
-
Timing for capex and procurement: With near-term demand growth and input-cost volatility, the report maps scenarios that let procurement teams choose between carrying higher inventory, negotiating longer supply contracts, or locking in tiered pricing — each mapped to different risk tolerances.
Bollards Market -
Product and portfolio planning: Designers and product managers will find structured guidance on where to prioritize development (e.g., modularity, crash-rated solutions, and aesthetic integration) without over-allocating resources to slower-moving subsegments.
Bollards Market -
M&A and partnership scouting: The market shows structural fragmentation with modest concentration at the top (CR3 and CR5 levels indicate a market where leading players are influential but not dominant). Our competitive heatmaps identify acquisition targets and partnership archetypes that accelerate scale or capability.
-
Regulatory and compliance roadmaps: Standards such as ASTM F3016 — and evolving city procurement specifications — are increasingly central to contract award and liability management. The report translates these into checklists and procurement clauses to reduce downstream litigation and retrofit costs.
What the full report delivers (practical, executable content)
-
Executive dashboards: Scenario-based financial models (base, upside, downside) calibrated to a 2025 base year and to the 2026–2032 forecast period, enabling quick stress-testing of price, volume, and material-cost shocks.
-
Go-to-market playbooks: Tactics for channel segmentation, tender response templates that reflect ASTM and local-spec requirements, and differentiated value propositions for security integrators, municipal buyers, and commercial developers.
-
Supplier risk matrices: Assessment of raw-material exposure (notably steel) and logistics chokepoints, plus mitigation levers such as alloy substitution, strategic hedging, and localized fabrication hubs.
-
Commercial benchmarks: Pricing bands, margin archetypes by product family, and stepwise recommendations for moving from commodity to value-differentiated offerings.
-
Implementation templates: Pilot design briefs, installation best-practices, maintenance schedules, and lifecycle cost calculators that operational teams can deploy within 90 days.
Competitive landscape: who to watch and why
The bollards market sits between safety equipment and urban-infrastructure markets; players range from specialized fabricators to global perimeter-security firms. Market concentration metrics show that a small cohort of companies exerts visible influence, yet the industry remains open to regional specialists and innovative entrants.
-
Vestil Manufacturing Corp. — Strength: purpose-built removable and steel-pipe safety products; strategic thesis: leverage distribution networks in industrial and municipal channels. Watch for bundled service offerings to expand attach rates.
-
Reliance Foundry Co. Ltd. — Strength: breadth across concrete, contemporary, and crash-rated portfolios; strategic thesis: market leadership in specification-driven projects. Their product mix positions them well for high-profile public-space contracts.
-
Justrite Manufacturing — Strength: safety-focused bollard posts and plastic options; strategic thesis: low-cost, safety-compliant products for industrial clients. Potential acquirers may prize their channel relationships.
-
The Bollard Company — Strength: customization and aesthetic breadth; strategic thesis: urban-design-focused clients and façade-integrated solutions. Differentiation through finishes and design partnerships is their core play.
-
Ameristar Security Products & Barrier1 Systems — Strength: heavy-duty, crash-rated systems and engineered security bollards; strategic thesis: focus on high-spec security projects (transport hubs, critical infrastructure). These firms are natural bids on defense and government tenders.
-
Beacon Industries, BollardsUSA, Bollards Plus, Post Guard, Dark Horse Metals — Strength: fabrication agility and US-made propositions; strategic thesis: short lead times and localized service models will be growth levers in markets where supply-chain resiliency matters.
-
Frontier Pitts — Strength: automated and anti-ram solutions in Europe and beyond; strategic thesis: specialization in high-security, high-visibility installations with long replacement cycles and high margins.
-
Selcom Manufacturing — Strength: stainless-steel security bollards; strategic thesis: material differentiation for coastal and high-corrosion environments.
Recent developments shaping near-term strategy
-
Trade-show visibility and validation: Crash-tested bollards showcased at major security expos have elevated buyer expectations for certified performance and third-party testing protocols.
-
Standards and guidance: Industry guidance and updates (e.g., explanatory material tied to ASTM F3016) are being cited in procurement documentation — effectively raising the bar for compliance and narrowing the supplier pool for complex projects.
-
High-profile projects: Municipal upgrades and retrofit programs underline a steady pipeline of specifications favoring removable stainless-steel and crash-rated solutions — a call for manufacturers to scale validation and installation services.
-
Input volatility: Rising steel prices and supply-chain interruptions continue to compress gross margins for commodity-type products and accelerate the shift toward value-added, serviceable offerings.
Market dynamics to prioritize in 2026
-
Standards-driven demand: Compliance with ASTM F3016 and comparable regional rules is transitioning from "nice-to-have" to a precondition for larger contracts. Firms that can certify and document performance will see shorter sales cycles in security-sensitive tenders.
-
Material and logistics pressure: Steel-price inflation and pipeline disruptions make supply-chain strategy a competitive weapon. Options include dual-sourcing, nearshoring, and converting to alternative alloys where permissible.
-
Product differentiation through services: Installation guarantees, maintenance contracts, and rapid-replace programs create recurring revenue and defend margins against commoditization.
-
Urban design and integrations: Demand for aesthetically integrated solutions in public space projects is growing. Manufacturers that partner with architects and landscape firms gain specification advantage.
Strategic playbook — recommended actions for 2026
-
For manufacturers: Prioritize third-party certification for crash-rated lines, lock in mill agreements where possible, and pilot bundled service contracts to convert installation into recurring revenue.
-
For distributors and integrators: Build ASTM-compliant proposal templates; invest in demonstrable install and maintenance capability; and create tiered offerings that balance price sensitivity with security requirements.
-
For municipal and enterprise buyers: Use performance-based RFPs tied to ASTM and lifecycle costs; require supplier-supplied maintenance schedules; and evaluate total-cost-of-ownership rather than headline price.
-
For investors and acquirers: Seek scale or capability tuck-ins — particularly in crash-rated engineering, rapid manufacture, and localized installation networks. Targets that reduce lead times or add certification capability are highest priority.
How PW Consulting’s research supports execution
Our full Bollards Market report translates the market’s macro growth path into executable initiatives: a data-backed shortlist of M&A targets, procurement templates keyed to ASTM-compliant specifications, and modelled P&L scenarios under different steel-price trajectories. The research synthesizes historical trends from 2020–2025 with forward-looking scenarios across 2026–2032 to ensure you can make defensible choices today that remain robust as the market grows at a near-8% CAGR.
Next steps — a tactical invitation
This briefing is a strategic preview designed to surface implications and actions. Our public summary has intentionally left out the granular segmentation tables, regional and application-level breakdowns, and the full set of financial projections so that decision-makers can request the full dossier with tailored scenario runs. If your 2026 plans depend on procurement timing, product roadmaps, or acquisition screening, the complete report is the operational tool you need to convert market movement into business outcomes.
Contact PW Consulting to unlock detailed segment data, supplier scorecards, and the interactive forecast models that will let you convert the market’s trajectory into measurable advantage.
For detailed analysis of this topic, please visit the official page: Bollards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Sports Market to reach USD 344.8 Million by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-23
Power Sports Market 2026: A Strategic Preview for Executive Decision-Making
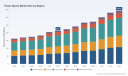
As PW Consulting’s Chief Industry Analyst, I present a high-impact preview of our full Power Sports Market study to help executives make sound strategic choices in 2026. The sector is in clear growth mode: the market expanded from approximately USD 163.2 Million in 2020 to USD 215.0 Million in 2025, and our baseline forecast projects continued expansion to roughly USD 344.8 Million by 2032 at a compound annual growth rate of 6.8% over the 2026–2032 forecast period. This preview synthesizes the implications of those top-line trends for product strategy, go-to-market design, capital allocation, and competitive positioning — while withholding certain proprietary segment breakouts to preserve the full report’s commercial value.
Power Sports Market
Why this research matters for 2026 decisions
- Prioritize investment with confidence: A 6.8% CAGR baseline means steady market expansion, but returns will vary significantly by product configuration, tech investment and route-to-market. Executives must translate macro growth into micro portfolio bets.
- Electrification and software are no longer peripheral experiments — they are strategic imperatives. EV powerpacks and connected features are altering product roadmaps, supplier relationships, and aftersales economics.
- Regulation and public capital are forcing short supply‑chain and dealer-model changes. New certification standards and government park investments reallocate opportunity across rental, fleet, and retail channels.
- Competitive dynamics are shaped by differentiated engineering features and software ecosystems. Product launches in 2025–2026 illustrate how incumbents are pushing on performance, user experience and electrified variants.
Practical contents of the full PW Consulting study (high level)
The full deliverable is designed for immediate operational use and board-level decisioning. It includes:
Power Sports Market
- Top-down market sizing and bottom-up revenue build for 2020–2032, including base, upside and downside scenarios aligned to macroeconomic and adoption assumptions.
- Demand-driver models that translate consumer preferences and policy shifts into quantifiable changes in unit demand and lifetime value by vehicle archetype and channel.
- Roadmaps and feature‑economics: margin and price elasticity analyses for ICE, hybrid and BEV powertrains, including Level 2 charging economics and TCO comparisons.
- Channel and dealer economics: revised dealer-margin models for new product mixes, rental/fleet partners and digital-direct experiments; inventory stress tests under shifting helmet/regulatory norms.
- Supplier and raw-material stress maps, including battery cell sensitivity, power electronics constraints, and mitigation pathways via strategic sourcing and vertical partnerships.
- Competitive positioning matrices, capability gap analyses, and a prioritized M&A target list (screened by technical fit, distribution access and margin uplift potential).
- Playbooks for marketing and OEM co-op redesign to capture digital-first consumer journeys, with sample creative-performance KPIs and ROI thresholds.
Key market dynamics shaping 2026 strategy
Several convergent forces will determine winners and losers in the coming 12–36 months:
Power Sports Market
- Product convergence around experience and software. Recent launches show a dual focus: mechanical performance (advanced suspension, geared reverse, towing capability) and enhanced digital ecosystems (large touch displays, ride-management software, smartphone integration). Expect software monetization opportunities but rising expectations for over-the-air support and UX quality.
- Electrification acceleration. Established OEMs are bringing electric variants to mainstream segments. This shifts cost structures (battery spend, charging enablement) and creates new partnerships with cell suppliers and charging networks.
- Regulatory and public-spend tailwinds. For example, targeted public investments into parks and trails in early 2026 unlock demand for rental fleets, trail-based experiences and public-private partnerships — but also change product specifications for safety and noise compliance.
- Standards and certification changes. Recent rule shifts on permissible helmet certifications and other safety standards force rapid inventory and spec adjustments across retail networks, with direct P&L and warranty impacts.
- Marketing program reallocation. OEM co-op programs are explicitly shifting toward digital advertising and original content; companies that optimize co-op spend for measurable digital outcomes will create outsized advantage.
- Fragmented supplier landscape and concentrated component risk. Battery and power-electronics supply remain the pivotal constraint; firms that secure capacity or vertically integrate selectively will mitigate margin erosion and time-to-market risk.
Competitive landscape — what matters to executives
The leading OEMs remain technologically capable and brand-rich, but each pursues distinct routes:
- Polaris Inc. — Strong in off‑road performance platforms and increasingly focused on connected experiences via vehicle software and integrated displays. Their recent product introductions emphasize suspension and user-control innovations that defend premium segment leadership.
- BRP Inc. — Creative with propulsion: their move into electric ATVs signals an aggressive play on electrified utility and performance offerings. Expect BRP to push on powerpack integration, charging speed and modular battery strategies.
- Yamaha Motor Corporation — Deep engineering pedigree in two- and four-wheel performance, with iterative improvements in traction control and ECU features that appeal to enthusiast segments. Yamaha blends mechanical refinement with incremental electronics integration.
- Honda Motor Co., Ltd. — Leveraging global scale across powertrains and distribution; their advantage lies in manufacturing discipline and cost control as the market bifurcates between premium tech-led models and value-conscious mainstream units.
- Harley-Davidson, Inc. — Premium motorcycle brand expanding its feature set and rider assistance systems. Their product launches show an emphasis on ride comfort, integrated infotainment and accessory ecosystems for higher-margin sales.
For challengers and mid-market players, the strategic choices are binary: invest materially in electrification, software and digital distribution — or consolidate around niche strengths such as rental fleet partnerships, regional manufacturing or aftermarket specialization.
2026 decision playbook — a concise roadmap
- 0–90 days (stabilize & prioritize): Run a scenario overlay using the study’s baseline CAGR (6.8%) and stress cases; reassign near-term capex to product lines with the shortest path to positive free cash flow. Audit dealer inventory for regulatory compliance and safety certification exposure.
- 3–6 months (test & iterate): Pilot an EV product in a controlled geography with a charging and service partner; deploy a revamped OEM co-op pilot that favors digital content and trackable conversions; sign conditional supply agreements with cell providers.
- 6–12 months (scale & defend): Harden software-delivery processes, roll out subscription services where unit economics are favorable, and negotiate dealer economics rebalancing that rewards service and digital lead conversion.
- 12–24 months (transform): Accelerate any necessary M&A for battery or software capabilities, commit to targeted manufacturing retooling for EV powerpacks, and institutionalize data-driven marketing to capture lifetime value improvements.
Risk vectors and mitigation
- Supply shocks — secure conditional contracts, diversify supplier base, and model inventory buffers in our scenario toolset.
- Regulatory surprises — maintain a regulatory watchlist and a rapid-spec-change operating cadence with dealer partners to reduce stock write-offs.
- Channel displacement — invest in dealer digital enablement and performance-based co-op models to preserve physical network viability while pursuing digital direct channels.
- Consumer adoption lags for EVs — match incentives, warranty structures and charging partnerships to bridge TCO perception gaps.
How to use the full PW Consulting report
This preview outlines the strategic levers and the operational playbook. The full report contains the proprietary, granular segment and regional tables, sensitivity-tested financial models, and executable annexes (including a prioritized M&A screen and a dealer economics workbook) that your strategy, product and finance teams can plug directly into scenario planning and board materials.
We have intentionally withheld the detailed segment-level splits and certain granular dashboards to preserve the competitive value of the comprehensive study. To access the complete dataset, downloadable models, and an executive briefing tailored to your organization’s position in the value chain, please visit our report page or contact PW Consulting’s advisory team for a confidential briefing.
In short: the Power Sports market is growing, technologically active, and strategically consequential for 2026 decisions. Firms that align capital to electrification and software, redesign co-op and dealer economics for digital-first consumer journeys, and lock down critical supply relationships will capture the disproportionate share of upside as the market matures toward 2032.
For detailed analysis of this topic, please visit the official page: Power Sports Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Alumina Zirconia Oxide Abrasives Market to Reach USD 436.18M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-23
Alumina Zirconia Oxide Abrasives Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
As companies plan capital allocation, procurement strategies, and product roadmaps for 2026, clarity on the alumina zirconia oxide abrasives market is critical. PW Consulting’s new market research—anchored on a 2025 base year with a 2026–2032 forecast horizon—synthesizes historical dynamics (2020–2025) with forward-looking scenarios to help executives convert uncertainty into actionable choices. The global market has expanded steadily from the early 2020s and, under our central-case outlook, grows at a compound annual growth rate (CAGR) of 5.2% through the forecast window—moving from a mid-three‑hundred million USD base in 2025 toward a substantially larger market by 2032. This preview outlines the study’s strategic value for 2026 decisions while intentionally withholding granular segment tables to encourage full report access for transaction-level intelligence.
Alumina Zirconia Oxide Abrasives Market
Why this market matters in 2026
-
Material substitution is shifting demand composition. Alumina zirconia grades are gaining share across metalworking and bonded-abrasive applications where improved cut rates and life-cycle performance justify higher unit costs. That shift interacts with evolving manufacturing tolerances and surface-finish requirements—creating premiumization opportunities for suppliers able to demonstrate total cost-of-ownership advantages.
Alumina Zirconia Oxide Abrasives Market -
Supply-side structural constraints are re-shaping sourcing strategy. Global raw-material movements—illustrated by higher bauxite throughput and changing refinery footprints—are increasing exposure to upstream volatility. Our research highlights the linkages between bauxite and zirconia sourcing, substitution levers (e.g., silicon carbide), and their cost and performance trade-offs.
Alumina Zirconia Oxide Abrasives Market -
Market concentration amplifies competitive dynamics. The sector exhibits a high concentration among leading producers; our concentration metrics indicate that the top few firms command a dominant share of market supply. For buyers, that translates into negotiating asymmetries but also predictable innovation pipelines from incumbent R&D investments.
Key takeaways for 2026 decision-making
-
Procurement: shift from unit price to lifecycle cost metrics. Firms that revise procurement KPIs to prioritize grinding-life, downtime reduction, and disposal/recycling economics will unlock near-term margin expansion. Our modeling shows that modest premium on per-unit abrasion media can be offset by reduced cycle time and fewer wheel changes in many metalworking contexts.
-
Manufacturing & product development: prioritize performance demonstrators. OEMs and abrasive formulators should invest in in-field validation pilots that quantify per-batch productivity gains. Suppliers that couple materials science with application engineering (e.g., coated slurry optimizations, binder chemistry adjustments) will secure longer-term specification placements.
-
M&A and JV strategy: target capability and feedstock control. Given the market’s concentration and the criticality of raw-material access, acquisitions that secure upstream inputs, or that add differentiated grain technologies and customer applications expertise, will be accretive faster than greenfield capacity. Our diligence templates prioritize feedstock security, regulatory exposure, and process scalability.
-
Sustainability and regulation: incorporate material-circularity roadmaps. Leading players are already positioning recycled-content grades and lower-CO2 melt routes as procurement filters become common in large OEM supply chains. Regulatory signals—particularly in raw-material sourcing and energy-intensive production—will increasingly influence siting and contract terms.
Market trajectory and scenarios
Our baseline model—driven by historical volume and price dynamics from 2020–2025, and calibrated to macro-industrial demand scenarios—projects steady growth over 2026–2032 at a 5.2% CAGR. We present three scenario envelopes (conservative, base, and upside) that reflect permutations of raw-material shocks, capital expenditures by incumbents, and accelerated adoption of premium grains. Each scenario includes sensitivity analyses on price escalation, substitution rates, and productivity adoption curves to help firms stress-test strategic options.
Competitive landscape: what the preview reveals
-
Incumbent leadership and R&D intensity. Major global producers continue to invest in differentiated grain chemistries, premium grade rollouts, and sustainability claims. For example, a large European producer recently introduced a branded family of lower-carbon-content AZ grades as part of an explicit sustainability roadmap—an instructive case of product and positioning integration.
-
Regional production hubs and export dynamics. Asian manufacturing systems maintain cost and scale advantages for commodity-grade grains, while select European and North American players focus on premium bonded and finished abrasive systems. Trade show participation and targeted product launches in late 2025 underline an intensifying competition for specification placements across geographies.
-
Adjacency threat: engineered abrasives. Precision-shaped grains and engineered ceramic abrasives are competing across applications traditionally served by alumina zirconia. Some displacement is already visible in metalworking discs and specialty bonded tools, where longevity and predictable wear profiles outweigh raw-material cost differences.
Notable corporate activity (signal, not exhaustive)
-
Product innovation: A leading abrasives group launched a sustainability-focused premium AZ family in mid‑2025, emphasizing recycled inputs and lower embodied carbon for selected grades.
-
Market engagement: A major Chinese producer showcased its full alumina-zirconia portfolio at late‑2025 industry exhibitions, signalling an explicit push into precision grinding and finished-surface markets.
-
Competitive differentiation: Global industrial conglomerates continue to promote engineered grain technologies that target wear life and cut efficiency, challenging conventional alumina zirconia positioning.
Operational and supply-chain dynamics
Raw-material flows matter. In 2025, industry reporting pointed to elevated bauxite consumption and an increase in throughput compared to the prior year—factors that influence cost pass-throughs across the abrasive supply chain. Substitution levers (e.g., silicon carbide usage) exist but typically carry a premium; therefore, supply shocks to bauxite or zirconia streams can create both risks and arbitrage opportunities for integrated producers. In the United States, refinery capacity dynamics and higher import prices for crude dry bauxite and metallurgical grades underscore the need to model import-price scenarios and contingency sourcing strategies in procurement playbooks.
What the full report contains (high-level)
-
Market sizing and forecast model — Robust, auditable projections from 2020 through 2032 with scenario toggles for adoption rates, price paths, and substitution elasticity.
-
Supply-chain maps and cost stacks — End-to-end mapping from raw-material sourcing to finished bonded/coated products including energy and process levers.
-
Application and product segmentation — Demand drivers and growth vectors across product families (note: this preview omits the full segment-value tables to preserve subscription value).
-
Competitive benchmarking — Strategy matrices, technology roadmaps, and capability heatmaps for the leading suppliers and emergent challengers.
-
M&A and investment playbook — Deal screening criteria, valuation multipliers specific to abrasives, and integration risk checklists focused on feedstock and process scale.
-
Regulatory and sustainability matrix — Jurisdictional risk scoring, decarbonization levers, and compliance timelines that affect siting and capital planning.
-
Practical tools — Negotiation brief templates, pilot KPIs, and a supplier due-diligence checklist tailored to alumina-zirconia purchases.
How to use this intelligence in 90/180/360-day plans
-
First 90 days: Validate your exposure—map current bills of materials to abrasive types and suppliers; run immediate cost-of-ownership trials on high-volume SKUs.
-
Next 180 days: Execute supplier pilots that prioritize productivity metrics; begin conversations for longer-term supply agreements that lock in feedstock access and price bands.
-
360 days and beyond: Reassess your product portfolio and capital rhythm—consider bolt-on M&A or JV options to secure downstream specification control or upstream raw-material access.
Methodological note
The report is rooted in an auditable methodology: a blend of bottom‑up supply-side buildouts, top‑down demand calibration, customer channel interviews, and trade-data triangulation. Historical series cover 2020–2025 with a 2025 base year; forecasts run from 2026 through 2032. Sensitivity matrices for raw-material pricing, substitution rates, and policy shocks are included to stress-test strategic options.
Next steps — where this preview leads
This preview is intentionally selective: it demonstrates the strategic rigor and practical orientation of PW Consulting’s full study while omitting the granular segment and regional tables that many decision-makers need for transaction execution. If your 2026 strategic plan hinges on reliable segment-level demand curves, price-trajectory scenarios, supplier scorecards, or a downloadable financial model, the complete report and accompanying data pack provide those deliverables.
Contact PW Consulting to request the full market intelligence package, licensing options for the forecast model, and bespoke advisory workshops designed to convert these insights into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Alumina Zirconia Oxide Abrasives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Facial Water Spray Market Set to Expand at a 6.98% CAGR Through 2032
By pmarketresearch, 2026-07-23
Facial Water Spray Market — Strategic Imperatives for 2026 Decision-Makers
As global beauty and personal care portfolios pivot toward lightweight, natural, and on-the-go hydration formats, facial water sprays have emerged from niche wellness counters to a mainstream, fast-growing category. PW Consulting’s latest market study (base year 2025; historical coverage 2020–2025; forecast horizon 2026–2032) quantifies this shift and translates it into actionable strategic options for executives planning 2026 investments and product roadmaps. At a compound annual growth rate (CAGR) of approximately 6.98% across the forecast window, the category demonstrates resilient expansion driven by product innovation, premiumization, and channel diversification.
Facial Water Spray Market
Why this study matters for 2026 strategy
-
Timing: 2026 is a pivotal planning year — consumers’ expectations around clean ingredients, micro-dosing packaging, and multifunctional formats have crystallized. Our study isolates the vectors of sustained demand versus transient hype so leadership teams can prioritize capital allocation with confidence.
Facial Water Spray Market -
Clarity on scale: The market’s base size in 2025 and its projected trajectory through 2032 provide a clear revenue envelope within which R&D, M&A, and route-to-market experiments should be evaluated. Scenario modeling in the report translates CAGR-driven growth into opportunity pools by strategic priority (e.g., premiumization, travel-size formats, ingredient-led skus).
Facial Water Spray Market -
Competitive context: With a moderate top-tier concentration and room for regional champions, the report equips mid-cap and incumbent players with differentiated escape routes — whether via brand extension, ingredient sourcing, or channel specialization.
Data-driven snapshot (high level)
Our analysis anchors on audited historicals (2020–2025) and a granular forecast (2026–2032). The category showed steady recovery and expansion post-2021 as consumers rebalanced skincare routines with convenience-led formats. Projected growth of roughly 7% CAGR across 2026–2032 reflects both volume expansion and meaningful premiumization: innovations in formulation (prebiotics, botanical actives, mineral fortification), packaging (recyclable and tamper-evident systems), and go-to-consumer models (travel retail, D2C subscriptions, and influencer-driven limited editions) are contributing to ASP increases alongside unit growth.
Importantly, market concentration metrics indicate a partially consolidated top tier (a meaningful share captured by leading heritage and dermatology-first brands), while the remaining share remains accessible to agile challengers and private labels. This structure favors strategic plays that combine brand credibility with channel agility.
What the PW Consulting report delivers (practical modules)
-
Market sizing and scenario modeling — base case, upside (premiumization-led), and downside (cost-pressure) scenarios for 2026–2032 with sensitivity to pricing, ingredient premiums, and packaging costs.
-
Demand drivers and consumer archetypes — segmentation by occasion, lifestyle, and ingredient preference; elasticity matrices for price and feature trade-offs targeted at urban Millennials and Gen Z.
-
Channel and route-to-market playbooks — decision frameworks for prioritizing travel retail, pharmacy/derm channels, e-commerce marketplaces, and branded D2C; converters and heuristics for channel margin and CAC comparisons.
-
Innovation and NPD pipeline mapping — ingredient roadmaps (thermal and mineral waters, botanical extracts, microbiome-friendly actives), formulation case studies, and IP/claim risk assessments.
-
Packaging and sustainability assessment — lifecycle cost models for recyclable vs. refillable formats, supplier scorecards, and trade-off analyses for tamper-resistance vs. consumer convenience.
-
Regulatory & compliance matrix — practical checklists for global market entry including mandatory labeling, pressurized container requirements, and U.S. import declarations to minimize customs and retail rejection risk.
-
Competitive benchmarking and M&A playbook — capability heatmaps across top players, valuation multipliers observed for recent transactions, and integration playbooks for thermal-spring sourced brands.
-
Retailer and partner negotiation templates — term sheets for co-branded launches, margin-sharing models for travel retail, and pilot KPIs for retail media investments.
Competitive landscape and strategic moves to watch
The competitive set mixes heritage thermal-spring specialists, prestige fashion houses, dermatology-first brands, and lifestyle incumbents. Leading companies continue to leverage provenance narratives, clinical credibility, and packaging innovation to defend and extend their positions.
-
Avène — continues to translate thermal spring credentials into skin microbiome-forward claims; recent launches (e.g., prebiotic-enriched mists) signal a strategy to occupy the sensitive-skin trust space while enabling premium price points.
-
La Roche-Posay — evolving packaging and mist technology demonstrates a dual play: product performance and sustainability. Enhanced dispersion tech and recyclable materials reduce usage friction and respond to retailer ESG screening.
-
Evian — partnering with regional skincare players to blend mineral water provenance with localized botanical extracts shows a modular co-branding approach that accelerates market entry while preserving core brand equity.
-
Clinique — experimentation with travel-size customizable scent kits highlights an omnichannel tactic: leveraging duty-free and online exclusives to boost trial and repeat purchase without diluting full-size positioning.
-
Prestige houses (e.g., DIOR, Vichy, Caudalie) — investing in organic claims, anti-aging narratives, and grapevine/mineral stories to justify premium AS RPs and to target specialty retail and high-margin e-commerce cohorts.
-
Regional premium and professional brands (e.g., Uriage, Origins, Shu Uemura) — maintain differentiation through source storytelling, botanical formulations, and salon/professional channel partnerships.
Collectively, recent industry actions (product launches with eco-packaging, prebiotic-enriched formulations, and co-branded regional partnerships) validate three enduring beats for 2026 strategic planning: (1) provenance + science narratives; (2) packaging that balances sustainability with regulatory tamper-resistance; (3) channel-first launches to capture trial and convert to higher-margin D2C relationships.
Regulatory and supply-side dynamics that will dictate execution
-
Labeling & import: Regulatory obligations such as mandatory English country-of-origin statements, ingredient declarations, and net quantity statements introduce operational frictions for cross-border launches. These are not mere checklist items — label iteration cycles impact time-to-shelf and cost of goods.
-
Container rules: Self-pressurized and liquid cosmetic containers are subject to specific declarations; brands must integrate tamper-resistant design early in the NPD process to avoid costly reworks and retailer non-compliance.
-
Raw material sourcing: Thermal and mineral spring waters remain the core input for many high-end sprays; botanical and functional inclusions (aloe, rose water, vitamin E, coconut derivatives) have premium price volatility and supplier concentration risks.
-
Pricing dynamics: Formulas containing natural or certified ingredients command price premiums. Our cost-to-margin models evaluate whether premiumization can offset higher procurement and sustainable packaging expenses across multiple launch scenarios.
Strategic options for 2026 — executable and measurable
-
Premiumization play: For brands with strong provenance, prioritize clinical claims, recyclable/smart packaging, and selective travel-retail exclusives. KPI: premium SKU ASP uplift and repeat purchase rate within 6–9 months.
-
Channel specialization: Deploy targeted D2C pilots to capture first-party data for personalization and subscription upsells; use marketplace and travel retail for reach. KPI: CAC payback <12 months for subscription cohorts.
-
Co-branding acceleration: Use modular co-development (local botanicals + core mineral water) to penetrate APAC and regional premium markets without full-fledge local ops. KPI: time-to-market and wholesale margin splits vs. in-house launches.
-
Cost leadership in mass segments: For players targeting mass channels, focus on reformulation for cost efficiency and tamper-resistant, lower-cost recyclable packaging; preserve a “clean” ingredient story. KPI: gross margin expansion while maintaining price parity.
-
M&A and licensing: Target thermal-source brands for portfolio depth or acquire formulation and packaging specialists to secure supply and accelerate sustainability goals. KPI: integration synergies within 12–18 months.
How PW Consulting’s deliverables accelerate decision-making
Our report is structured to move stakeholders from insight to action. Rather than a long list of numbers, it provides decision-makers with decision-ready tools: sensitivity models, prioritized investment heatmaps, retailer negotiation templates, regulatory checklists, and a 12–24 month NPD and commercialization roadmap tailored to common corporate constraints (cap-ex limits, supply chain lead times, regulatory filing cycles).
To preserve commercial value and to respect client confidentiality in high-stakes categories, the public summary intentionally omits granular regional and application-level splits. The full study contains the detailed segmentation, price-point ladders, and channel-level forecasts that product teams and M&A groups will require to finalize 2026 budgets and go-to-market schedules.
Next steps for leaders
-
Shortlist your strategic priority (premium growth, channel expansion, or cost optimization) for 2026 and request the tailored scenario pack from PW Consulting that maps the category’s revenue envelope to your chosen path.
-
Run a 90-day pilot: use our market-access checklist and sample retail terms to execute a controlled market test in one key channel; capture CAC, repeat rate, and supply resilience metrics to inform Q4 funding decisions.
-
Engage on M&A diligence: if inorganic expansion is on the table, our M&A playbook and valuation comparables will accelerate target screening and offer structuring.
PW Consulting’s Facial Water Spray Market study is designed to convert category momentum into durable business outcomes. For the granular segmentation data, channel-level forecasts, and the full suite of execution templates that will inform 2026 boardroom decisions, please consult the complete report on our website or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Facial Water Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Photo Frame Market to Hit USD 235.6M by 2032 at 3.2% CAGR
By pmarketresearch, 2026-07-23
Digital Photo Frame Market — Strategic Preview for 2026 Decision-Making
As organizations and investors prepare strategy for 2026 and beyond, understanding the nuanced dynamics of the Digital Photo Frame (DPF) market has moved from a nice‑to‑have to a competitive imperative. Our PW Consulting market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes the commercial, technological and geopolitical forces shaping supplier economics, product roadmaps and commercialization models for the next growth cycle. This preview outlines the report’s strategic value, the macro trajectory, the competitive topology and the actionable themes leaders should prioritise—while deliberately reserving detailed subsegment figures to encourage direct access to the full analysis.
Digital Photo Frame Market
Why this study matters for 2026-level decisions
-
Portfolio prioritization: The DPF category is maturing—growth is steady rather than explosive—so executives must choose between incremental product innovation and adjacencies (services, subscription content, or enterprise deployments). Our research converts market shape and momentum into investment tradeoffs calibrated for 2026 budget cycles.
Digital Photo Frame Market -
Supply‑chain and sourcing strategy: Recent geopolitical and regulatory volatility has made sourcing decisions strategic. The report maps supplier concentration, margin sensitivity to logistics shocks, and feasible nearshore/onshore scenarios to help procurement and operations teams de‑risk rollouts and protect gross margins.
Digital Photo Frame Market -
M&A and partner screening: With a concentrated top tier of players and many viable regional OEMs, 2026 is a window for bolt‑on acquisitions and strategic alliances. Our due diligence frameworks reduce integration risk and highlight value-capture levers.
-
Commercial model decisions: The DPF market is evolving from one‑off hardware purchases to hybrid revenue models (hardware + cloud subscriptions + content licensing). The research quantifies the revenue implications of alternate go‑to‑market approaches so commercial leaders can model ARR and lifetime value tradeoffs.
Market snapshot (concise, data-driven)
On the macro level, the DPF market is in a low‑to‑mid growth phase. From a 2025 base (our reference year), the market is forecast to expand at a compound annual growth rate (CAGR) of approximately 3.2% across 2026–2032. That trajectory reflects a stable, consumer‑led category supplemented by steady commercial use cases—creating a forecasted expansion through the early 2030s that is predictable enough for disciplined capital allocation but modest enough to demand operational efficiency and differentiation.
Concentration is meaningful: the three largest vendors account for a dominant share of market value, and the top five even more so. That concentration shapes competitive dynamics, margins, channel leverage and price elasticity—factors we model in scenario detail in the full report.
Dynamics shaping the 2026 operating environment
-
Geopolitics and regulatory pressure: Ongoing trade tensions and cross‑border regulatory friction have pushed manufacturers to diversify assembly and reconsider component provenance. These forces accelerate product redesign cycles—especially around batteries and end‑of‑life handling—while compressing time‑to‑market for new display technologies.
-
Supply‑chain fragility and cost pass‑throughs: The sector remains sensitive to logistics disruption. Periods of heightened geopolitical risk have historically increased inventory carrying costs and insurance premiums materially, and these tail events are now embedded in many suppliers’ pricing models. Buyers and sellers must plan buffer capital and flexible logistics to avoid margin erosion.
-
Regulatory compliance and product development: Safety standards (battery, electronic waste) and consumer privacy regulation in key jurisdictions are pushing vendors toward safer batteries, more robust recyclability claims, and tighter data governance for cloud-enabled frames. These regulatory costs are non‑trivial and should be built into product cost‑of‑goods and roadmap timelines.
-
Labor and manufacturing footprint: Competitive OEMs in the region continue to underpin competitive pricing with local labour economics. Companies that can optimize labor mix across assembly, testing and packaging—combined with modular component sourcing—will retain an advantage in price‑sensitive channels.
Segmentation and opportunity pockets (strategic, not prescriptive)
The DPF market is widely segmented by product technology (LCD, LED, emerging OLED/e‑paper), and by end‑use across residential, commercial and institutional deployments. The full report contains a rigorous segmentation matrix and elasticity curves; here we outline the strategic implications without exposing granular split metrics:
-
Premium consumer vs. value hardware: There is durable demand for premium, connected frames that integrate app ecosystems and cloud sharing—driven by consumers who see these devices as lifestyle purchases. Conversely, a large value segment remains price sensitive and will pursue low‑cost, no‑frills offerings.
-
Enterprise and institutional adoption: Increasingly, DPFs are being repurposed for wayfinding, corporate communications and healthcare information delivery. These deployments favor ruggedization, remote provisioning and integration with third‑party content management systems—areas that incumbents and challengers can monetise through managed services.
-
Display innovation as a differentiator: Material shifts—OLED and e‑paper advances, anti‑glare coatings, and power management—are creating differentiation pathways. Firms that can balance cost, supply risk and unique user experiences will command higher ASPs and better retention on subscription layers.
Competitive landscape — focused profiles and tactical takeaways
The competitive topology includes a mix of digitally native premium brands, established consumer electronics labels and competent OEMs often operating behind private labels. Our study benchmarks product portfolios, channel strategies and R&D focus areas for the leading players.
-
Aura (U.S.) — Premium experience leadership: Aura has positioned itself around high‑end hardware, app‑centric user experience and aesthetic design. Its playbook reflects premium pricing, strong direct‑to‑consumer (DTC) presence and an emphasis on battery life and visual presentation features. For incumbents, Aura’s model shows how brand + ecosystem can insulate ASPs from commoditisation.
-
Nixplay (U.S.) — Cloud and voice integration: Nixplay combines cloud services with consumer hardware and has leaned into integrations (voice assistants, mixed media support). This shows the strategic value of platform thinking—where hardware drives recurrent cloud revenues and data‑driven upsell.
-
Aluratek (U.S.) — Feature breadth and calendar/utility focus: Recent launches (e.g., Smart WiFi Digital Calendar Photo Frames, April 2025) demonstrate a pragmatic approach of extending product utility—appealing to users who value hybrid functionality (photo + schedule + basic smart features).
-
Sungale (China) — Cost & scale: Sungale exemplifies OEM‑scale economics and aggressive cost‑to‑value positioning with a broad portfolio of cloud and plug‑n‑play frames. Suppliers operating from China continue to be central to global price dynamics and private‑label supply chains.
-
PhotoSpring, Kodak, Digital Foci — Niche plays and partnerships: Firms like PhotoSpring emphasize instant sharing and ease of setup; Kodak provides licensing muscle and brand recognition; Digital Foci focuses on both consumer and enterprise solutions. Each demonstrates alternative routes to market: UX differentiation, brand leverage, and B2B solutionisation respectively.
What the PW Consulting report delivers (practical components)
-
Market model with scenario sensitivity: We provide a base case and two alternate scenarios that stress test pricing, supply shocks and adoption shifts—suitable for financial planning and risk‑adjusted valuation.
-
Supplier scorecards and partner matrix: Comparative assessments of product portfolios, manufacturing risk, compliance readiness and partnership fit—ready to support procurement or M&A shortlisting.
-
Go‑to‑market playbooks: Channel strategies and launch plans for premium vs. value propositions, including marketing funnels, content strategies for cloud offerings and recommended sales incentives by channel.
-
Regulatory & sourcing checklist: Practical steps to match product roadmaps to emerging battery and e‑waste rules, plus a sourcing decision tree for nearshoring, split manufacturing and supplier dual‑sourcing.
-
IP and tech roadmap implications: Assessment of display technology adoption curves, component supply risks, and where to concentrate R&D to unlock ASP uplift or operational savings.
Strategic priorities for 2026 (recommended plays)
-
Choose a clear value capture model: Decide whether your organisation will pursue premium UX + subscription, low‑cost scale, or enterprise systems integration. Each requires different investments in product development, channel partnerships and customer support.
-
Invest in supply chain optionality now: Build at least one qualified alternative for critical components and plan phased nearshoring for high‑risk parts. Embedding supply‑chain flexibility into product cost models is a near‑term competitive advantage.
-
Monetize beyond hardware: Identify serviceable revenue streams (cloud storage, curated content, enterprise management) and pilot subscription bundles that can raise lifetime value without undermining initial sales conversion.
-
Prepare for regulatory lift: Integrate EOL (end‑of‑life) and battery compliance into product cost and warranty modelling to avoid late‑cycle remediation costs.
-
Pursue targeted M&A: Look for tuck‑ins that add cloud capability, regional distribution, or IP in energy management/display tech—acquisitions that accelerate margin expansion and reduce time‑to‑market.
Concluding note — the value of the full study
This preview outlines the strategic contours executives need to consider for 2026: a modestly growing global market with concentrated incumbency, meaningful supply chain and regulatory risk, and clear pathways to monetize product differentiation and services. PW Consulting’s full Digital Photo Frame Market report provides the quantitative backbone (detailed segmentation matrices, supplier rankings and scenario models) and the operational playbooks necessary to move from insight to execution. We purposefully refrain from publishing granular segment splits in this preview—those details, along with proprietary supplier assessments and deal frameworks, are available in the comprehensive study to support high‑confidence decisions.
For teams preparing strategic plans, procurement cycles and M&A pipelines in 2026, this research is designed as the actionable intelligence layer that reduces execution risk and accelerates value capture. Contact PW Consulting to access the complete report and the interactive market model.
For detailed analysis of this topic, please visit the official page: Digital Photo Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Dichromate Market Poised for 5.2% CAGR Through 2032
By pmarketresearch, 2026-07-23
Sodium Dichromate Market — Strategic Briefing for 2026 Decision Makers
As PW Consulting’s Chief Industry Analyst, I present a targeted preview of our forthcoming Sodium Dichromate Market study — a synthesis of market mechanics, regulatory inflection points, supply dynamics, and strategic options that senior executives and investment committees must factor into 2026 planning cycles. This briefing highlights the report’s strategic value, core conclusions at the market level, and the practical, decision-ready analysis contained in the full report. Detailed segment-level tables and proprietary models are intentionally omitted here to preserve the value of the full study and direct readers to the source for actionable granularity.
Sodium Dichromate Market
Why this study matters for 2026
-
Timing: the market is at a crossroads. Our base year is 2025 and our forecast horizon extends through 2032. Between 2020 and 2025 the global sodium dichromate market grew from a measured baseline to a materially larger industry, and our forward model — using a 5.2% CAGR across the forecast period — indicates continued expansion under multiple stressors and opportunities.
Sodium Dichromate Market -
Regulatory inflection: recent regulatory actions in Europe (notably the European Chemicals Agency’s April 2025 intent to propose restrictions under REACH, the listing of sodium dichromate on the Candidate List, and the fact that Cr(VI) substances are subject to authorization under REACH Annex XIV) materially increase compliance complexity and potential market reconfiguration for 2026 and beyond.
Sodium Dichromate Market -
Supply-chain and feedstock sensitivity: chromite ore remains the primary feedstock; volatility and geopolitical exposure in ore supply chains create earnings and supply risk for producers and downstream integrators. Procurement strategies implemented in 2026 will lock in exposures through several years and thus must be informed by robust scenario analysis.
Market snapshot — headline macro numbers
At the market level, our analysis consolidates global revenues in USD (Million). From a baseline near USD 1.22 billion in 2020, the market expanded to roughly USD 1.52 billion by the 2025 base year. Using our forecast assumptions and a 5.2% compound annual growth rate (CAGR) for the period 2026–2032, the market is projected to approach just over USD 2.17 billion by 2032. These aggregate figures encapsulate demand across metal finishing, pigments, wood preservation, leather tanning and other industrial applications, while excluding detailed breakdowns that are available in the full report.
Market concentration is moderate: the top three firms account for roughly one‑third of global market revenue, and the top five firms only modestly increase that share. This structure signals meaningful space for regional specialists and low-cost producers to exert influence, even as certain incumbents leverage scale and distribution networks.
Key dynamics shaping 2026 decisions
-
Regulatory pressure and substitution pathways — The recent ECHA activity marks a substantive shift: potential REACH restrictions and authorization requirements raise the cost of market participation for producers and users in Europe and for exporters to EU markets. Companies should treat regulatory exposure not as a binary compliance matter but as a strategic force that reshapes pricing power, supply chains, and product portfolios. The report provides a ranked matrix of exposure by use-case and region (full proprietary data in the report).
-
Demand composition — End-use demand remains diversified across industrial applications. While traditional metal finishing and pigment uses continue to anchor volumes, innovation and regulatory signals are accelerating the search for lower‑chromium alternatives in specific subsegments. Our scenario work identifies which end uses are most likely to see substitution pressure before 2032 and where premium, compliant grades can command a margin uplift.
-
Feedstock and input-cost volatility — Chromite ore dynamics govern variable cost for sodium dichromate production. The report models several supply‑shock scenarios and their pass-through effects on producer margins and downstream pricing, offering practical hedging and contract structures for procurement teams.
-
Consolidation and regional specialization — Given the moderate concentration ratio and the cost of environmental compliance, the market is primed for selective consolidation in regions where regulation raises barriers to entry and for fragmented competition where lower-cost feedstock and less stringent enforcement prevail.
What the full report contains — practical, actionable modules
-
Executive dashboard: concise, C-suite-ready market sizing, growth scenarios, and heat maps of regulatory and supply risk at the market and submarket level (proprietary tables and downloadable models are available in the full product).
-
Demand forecasting by use-case: bottom-up models explaining drivers in metal finishing, pigments, wood preservation, leather processing and 'other' industrial uses, with sensitivity testing under alternative regulatory and raw-material circumstances.
-
Supply and trade: plant-level capacity mapping, trade-flow analysis, and an assessment of logistics chokepoints and export control exposure. This section includes practical scenario playbooks for sourcing and inventory strategy.
-
Regulatory impact assessment: authoritative review of REACH developments, authorization timelines, and national/regional regulatory permutations. We translate legal exposure into quantifiable cost impacts and market access scenarios for 2026–2028.
-
Competitive profiling: in-depth dossiers on manufacturers and distributors, capability maps, product specifications, packaging and logistics practices, and recent investments. Profiles include strategic assessments of capacity expansion plans, product purity positioning, and export orientation.
-
Value-chain risk and mitigation playbook: practical recommendations for procurement, product stewardship, customer contracts, and R&D investment to secure demand under tightening regulation or feedstock shocks.
-
M&A and partnership opportunities: target identification and valuation frameworks for acquirers and investors, including playbooks for integrating capacity, closing supply gaps, or accessing compliant formulations.
Competitive landscape — what executives need to know now
Our public-entity and primary-research synthesis highlights a group of established producers who collectively shape market dynamics. These companies range from integrated producers with export capabilities to regional specialists serving domestic markets. Key companies examined in the report include, among others, Vishnu Chemicals Limited (India), Nippon Chemical Industrial Co., Ltd. (Japan), Hubei Zhenhua Chemical Co., Ltd. (China), Yinhe Group (China Yinhe Chemical Industry Group), and Soda Sanayii A.S. (Turkey). Each profile assesses production technology, product purity positioning, packaging/logistics capabilities, and strategic moves such as capacity expansion or export orientation.
Illustrative takeaways from our company analysis (high level):
-
Some Asian producers emphasize scale and cost-competitiveness for bulk industrial grades, with broad distribution networks across regional end-users.
-
Producers in developed markets and select Asian manufacturers focus on high‑purity grades for demanding applications such as aerospace and specialized chemical synthesis, investing in quality assurance and certifications that support premium pricing.
-
Several firms have signaled capacity investments to meet growing export demand; however, regulatory constraints in key consuming markets create uncertainty about future access and margin stability.
Strategic actions for 2026 — a pragmatic checklist
-
Reassess procurement contracts now: lock in pricing and volume flexibility clauses tied to feedstock indices and regulatory milestones. Short‑dated contracts with trigger-based renegotiation clauses are prudent as the REACH process unfolds.
-
Prioritize compliance and traceability investments: invest in upstream traceability of chromite ore sourcing, product stewardship systems, and documentation to facilitate market access under evolving authorization regimes.
-
Evaluate product portfolio rationalization: identify high-risk SKUs and high-margin compliant formulations. Redirect R&D to alternative chemistries where substitution risk is high and commercial feasibility exists.
-
Plan for regional shifts: model demand and profitability under scenarios that assume tighter EU access. Consider near‑market partnerships or tolling arrangements to maintain EU presence if direct exports become constrained.
-
Use M&A selectively to secure feedstock or compliant capacity: target assets that offset regulatory risk (e.g., facilities with advanced waste handling and emissions controls) or that provide access to critical customers under long-term contracts.
How PW Consulting informs your 2026 roadmap
The full Sodium Dichromate Market report is built to be operationally useful: our models are distributed in editable spreadsheets, our regulatory impact matrices are calibrated to likely timelines, and our scenario work includes decision gates tailored for CFO, COO, and Head of Procurement audiences. The study converts complex regulatory and supply signals into prioritized actions with quantified P&L and cash-flow implications across a range of realistic 2026 scenarios.
In short: for executives weighing capital deployment, sourcing strategies, or M&A in 2026, this study provides the market-level orientation, risk quantification, and playbooks needed to make informed, defensible decisions — while the full dataset and granular segmentation remain gated within the complete report to preserve their commercial value.
Next steps
For teams preparing 2026 budgets, procurement roadmaps, or strategic investment memoranda, we recommend procuring the full report to access the proprietary segment matrices, supplier scorecards, and downloadable scenario models. PW Consulting stands ready to run bespoke stress tests on your specific supply contracts and product mix and to facilitate workshops that translate the report’s insights into executable 90‑, 180‑ and 360‑day plans.
For detailed analysis of this topic, please visit the official page: Sodium Dichromate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stereo Bluetooth Headsets Market Poised for 8.95% CAGR Through 2032
By pmarketresearch, 2026-07-23
Stereo Bluetooth Headsets Market — Strategic Outlook & 2026 Decision Playbook
As organizations plan for a fast-evolving audio accessories landscape in 2026, actionable market intelligence that combines rigorous forecasting, competitive mapping, and operable playbooks becomes a strategic necessity. PW Consulting’s latest Stereo Bluetooth Headsets Market briefing (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) answers that need. The market we track reached approximately USD 1,980 Million in 2025 and is projected to grow at a compounded annual growth rate of 8.95% through the forecast window, roughly doubling in scale by the end of the period. This synthesis explains why that trajectory matters to executive decision-making in 2026 — and what practical moves should follow.
Stereo Bluetooth Headsets Market
Why 2026 Is a Pivotal Year
-
Product innovation is accelerating. Between 2023 and 2024 new product development in stereo Bluetooth headsets surged dramatically, with true wireless stereo (TWS) designs accounting for the majority of new launches. Advances such as Bluetooth 5.3+ integration, expanded active noise cancellation (ANC) features, touch-gesture controls, and embedded AI audio enhancements are shifting buyer expectations and raising baseline feature sets.
Stereo Bluetooth Headsets Market -
Supply-side fragility persists. Component shortages (notably lithium-ion cells, Bluetooth SoCs, and MEMS sensors) and logistics constraints have increased component costs and extended lead times—pressures that continue to shape sourcing, pricing, and inventory strategies.
Stereo Bluetooth Headsets Market -
Regulatory and geopolitical shifts are forcing reconfigurations of both product engineering and supply footprints. New European rules on common chargers and government manufacturing incentives in South Asia are examples of structural influences that will affect product design and where value chains are located.
Market Dynamics: What’s Driving Revenue and Margin Movements
-
Premiumization and feature-led differentiation: Consumers and enterprises increasingly pay for audio fidelity, ANC, spatial audio, and seamless multi-device integration. These features lift average selling prices and expand the premium segment.
-
TWS standardization: TWS architectures are now the dominant product architecture in new launches and premium SKUs, driving R&D focus and changing accessory and packaging ecosystems.
-
Cost inflation and lead-time risk: Industry data indicate component cost inflation in the low double digits and average shipping delays adding weeks to lead times, which compress gross margins unless offset by pricing power or cost mitigation programs.
-
Channel and use-case diversification: Growth is coming from both classic consumer electronics and specialized pockets such as gaming and professional communications where reliability, latency, and microphone performance matter more than ever.
Competitive Landscape — Strategic Positions to Watch
-
Sony — Premium audio innovation: Sony’s product strategy centers on best-in-class ANC and immersive sound tuning. Their flagship stereo TWS products signal a continued focus on premium user experience and frequent firmware-driven feature upgrades to defend ASPs.
-
Apple — Ecosystem and user experience moat: Apple leverages deep integration across devices and services to maintain pricing power. Their audio roadmap emphasizes spatial audio and seamless device switching that sustain high-perceived value.
-
Bose — Brand-led ANC and consumer trust: Bose sits on brand equity in noise-cancellation performance and comfort, which helps preserve shelf space in premium retail and enterprise channels.
-
Samsung — Platform-driven differentiation: Samsung combines hardware innovation with mobile platform synergies and distribution reach across numerous markets to pursue share gains.
-
Jabra / Poly / Logitech — Enterprise and hybrid work plays: These vendors focus heavily on professional-grade headsets that emphasize microphone clarity, battery life, and unified communications certification — an important growth vector as hybrid work persists.
-
Sennheiser / JBL / Anker — From audiophile to value segments: These brands span the spectrum from high-fidelity niches to aggressive value propositions, using product breadth to capture multiple price bands.
Across the market, concentration remains modest: the top three and five firms do not dominate the space to the degree seen in some other consumer electronics categories. That fragmentation creates attractive windows for targeted consolidation, white-label partnerships, and niche differentiation plays.
What the Full Report Contains (Practical, Executable Assets)
PW Consulting’s full Stereo Bluetooth Headsets Market report delivers practitioner-focused tools designed for 2026 strategy cycles. Highlights include:
-
A calibrated market model (historical 2020–2025; base year 2025) and scenario-driven forecasts through 2032, enabling upside/downside planning for product, channel, and M&A initiatives.
-
Product innovation tracker mapping feature adoption curves (ANC, Bluetooth versions, AI audio, gesture controls), and time-to-market benchmarks for new launches.
-
Supply-chain heatmaps and supplier risk matrices that quantify exposure to critical components and logistics corridors, plus mitigations including supplier diversification and nearshoring.
-
Competitive scorecards and capability matrices for the leading vendors—assessing engineering depth, channel strength, service ecosystems, and IP positions.
-
Go-to-market playbooks tailored to distinct strategies: premium direct-to-consumer, enterprise UC partnerships, gaming-focused channel builds, and value-tier mass-market rollouts.
-
Pricing and margin sensitivity models that let commercial teams stress-test pricing responses to component cost inflation and promotional cadence.
-
M&A screening framework and integration checklist oriented to bolt-on audio brands, audio IP picks, and contract manufacturers that accelerate time-to-market.
To preserve the value of this briefing as a strategic “trailer,” the report intentionally withholds granular segment share tables and SKU-level revenue breakdowns from this summary; those detailed matrices are available in the downloadable dataset and appendices.
2026 Strategic Imperatives — How Leaders Should Act
-
Secure and rationalize supply chains now. Component price inflation and lead-time volatility are not one-off problems. Build multi-sourced procurement lanes for batteries, RF/SoC, and MEMS; invest in buffer inventory strategies; and prioritize suppliers with local assembly capabilities to mitigate logistics risk.
-
Design with regulatory foresight. European common-charging rules and ongoing reviews require product teams to align charging strategies, reduce accessory fragmentation, and plan SKUs that comply without sacrificing margin.
-
Differentiate through software and services. With hardware feature parity increasing, firms that layer firmware upgrades, personalized audio tuning, and subscription services will protect ASPs and create recurring revenue.
-
Segment route-to-market by use case. Gaming, professional communications, and premium consumer audio each require distinct product, channel, and support strategies. Avoid one-size-fits-all launches—focus instead on optimized SKUs and GTM plans per vertical.
-
Use manufacturing incentives to diversify footprint. Government programs in South Asia are attracting component suppliers and assembly investment; firms that move selected assembly closer to demand can reduce tariff and logistics exposure.
-
Prepare M&A and partnership playbooks. Moderate market concentration means strategic acquisitions can quickly deliver scale and capability (e.g., audio IP, UC certifications, or distribution networks).
Scenario Considerations You Must Model in 2026
-
Base scenario: Continued mid-to-high single-digit CAGR driven by premiumization and feature upgrades (consistent with our central 8.95% CAGR outlook for the stereo segment).
-
Supply-shock downside: Extended semiconductor or battery constraints that materially raise component costs beyond current estimates and compress sell-through during peak seasons.
-
Regulatory upside/downside: Faster imposition of cross-border interoperability standards (e.g., expanded ‘common charger’ categories) that raise short-term reengineering costs but reduce accessory fragmentation long-term.
-
Consolidation upside: Accelerated M&A and OEM consolidation that increases scale advantages for incumbents, raising barriers for small entrants focused on hardware-only differentiation.
Closing — What This Means for Your 2026 Plan
For executives building 2026 business plans, the core takeaway is straightforward: the stereo Bluetooth headset market is expanding at a pace that rewards early, disciplined investments in supply resilience, software-enabled differentiation, and use-case-specific route-to-market execution. PW Consulting’s report provides the quantitative forecasts, risk-adjusted scenarios, and go-to-market toolkits that leadership teams need to convert market growth into durable share gains and margin expansion.
To access the full dataset, company scorecards, and executable playbooks that underpin the forecasts summarized here, please download the full Stereo Bluetooth Headsets Market report. For bespoke strategy engagements — including M&A target screening, supply-chain redesign, or product roadmap optimization — PW Consulting’s industry practice stands ready to partner on rapid, high-impact implementations.
For detailed analysis of this topic, please visit the official page: Stereo Bluetooth Headsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emotion Analytics Market Poised for USD 4,753.44 Million by 2032 with 15.5% CAGR
By pmarketresearch, 2026-07-23
Emotion Analytics Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
By the end of 2025 the global emotion analytics market had reached institutional scale, and our PW Consulting report—rooted in a 2025 base year, a 2020–2025 historical window, and a 2026–2032 forecast horizon—maps the trajectory organizations must plan around. The market is growing at a robust compound annual growth rate (CAGR) of 15.5%, and our model projects a multi‑fold expansion through the forecast period. For firms making investment, product, or regulatory-compliance decisions in 2026, this research is designed to convert market momentum into repeatable advantage while protecting enterprises from legal, ethical, and operational pitfalls.
Emotion Analytics Market
Why this matters in 2026
- Acceleration meets regulation: 2025–2026 is the inflection where technological capability (multimodal sensing, edge compute, and scalable cloud AI) collides with stricter privacy and biometric rules. Organizations that treat emotion analytics as merely a technical add-on risk costly non-compliance or brand damage.
- Commercial utility is expanding: Emotion analytics is moving from experimental proof‑of‑concepts into production use across customer experience, healthcare, automotive safety, and public safety programs. That movement changes how procurement, legal, and product teams must coordinate.
- Strategic timing: Decisions taken in 2026 — about architecture (cloud vs. on‑premise), vendor selection, consent frameworks, and go‑to‑market playbooks — will determine whether firms capture disproportionate value or become reactive spend centers.
Market trajectory: what the macro numbers mean for strategy
Our top‑level model shows the market evolving from a mid‑market base in 2025 to a substantially larger opportunity by the end of the forecast period. The sustained 15.5% CAGR implies that organizations that enter early with sound governance and modular architectures can capture high growth without being locked into obsolete solutions.
Emotion Analytics Market
Two practical implications follow. First, vendors and buyers should assume technology refresh cadence will accelerate — plan for a 24–36 month upgrade/resilience cycle rather than longer legacy cycles. Second, total cost of ownership (TCO) analyses must include privacy remediation, consent management, and jurisdictional data‑sovereignty costs as line items; these are material to ROI in 2026 procurement decisions.
Emotion Analytics Market
Key market dynamics that should shape your 2026 playbook
- Regulatory constraints are now business constraints. Legislations such as the EU AI Act and evolving biometric interpretations under privacy regimes require explicit re‑engineering of systems that capture facial expressions or physiological signals. In several jurisdictions, workplace and educational uses face strict prohibitions or additional compliance gates. Legal risk is now an operational variable in solution design.
- Data architecture matters. Cloud-native offerings provide elasticity and rapid model retraining, while on‑premise deployments remain necessary for healthcare, banking, and other regulated verticals. Hybrid architectures and edge inference are emerging as the default compromise for enterprises that need low latency, privacy preservation, and centralized model governance.
- Fragmented vendor landscape with specialist leaders. The market displays a mix of focused emotion‑AI specialists and large cloud/platform vendors extending their cognitive services. Competitive intensity is increasing around multimodal pipelines, explainability toolkits, and privacy‑first deployment patterns.
- Operational readiness drives adoption. Adoption is constrained less by model accuracy than by integration complexity: labeling workflows, calibration to local populations, consent workflows, and the availability of domain‑qualified ML engineers.
Competitive landscape: who to watch and what they signal
The market comprises a blend of specialist providers delivering verticalized emotion solutions and major platform vendors scaling multimodal cognitive services. Our competitive analysis in the full report profiles the strategic positioning, go‑to‑market focus, and technical differentiators of leading providers.
- Smart Eye AB (Sweden): Focused on multimodal emotion recognition and driver monitoring, Smart Eye’s recent product integrations illustrate how OEM partnerships in automotive accelerate on‑vehicle safety use cases and edge deployment strategies.
- Uniphore (United States): With an agentic enterprise platform, Uniphore demonstrates how speech‑centric emotion analytics can be embedded into contact center automation and sovereign cloud offerings for regulated enterprises.
- iMotions A/S (Denmark): iMotions’ emphasis on eye‑tracking and privacy‑first SDKs signals the commercial importance of on‑device analytics and research‑grade instrumentation for behavioral studies.
- Realeyes Ltd. (United States): A cloud‑native player specializing in facial emotion recognition for advertising and CX measurement, Realeyes highlights the continued demand for cloud analytics in media and marketing workflows.
- Noldus Information Technology (Netherlands): Noldus’ research‑oriented video analytics tools show the cross‑pollination between academic/clinical use cases and commercial behavioral analytics.
- Cognitec Systems (Germany): Cognitec’s behavioral and biometric platforms indicate persistent demand in security, aviation, and public safety where verification and emotion cues converge.
- Beyond Verbal Ltd. (Israel) & NViso SA (Switzerland): These vendors underscore modality specialization—voice and physiological/EEG inputs respectively—and the value of modality‑specific pipelines for constrained or privacy‑sensitive environments.
- IBM & Microsoft (United States): Large platform incumbents are expanding cognitive services with cross‑cultural models, fairness testing, and enterprise integrations; their moves lower the barrier to entry for many buyers but also raise questions about dependency and differentiation.
Collectively, these providers show two clear market dynamics: specialization (modalities, verticals, deployment models) and platformization (bundling into larger enterprise AI stacks). Our market concentration analysis characterizes the market as moderately fragmented—enough room for vertical specialists to thrive, but with growing competitive pressure from platform incumbents.
Regulatory, privacy and ethical guardrails
- EU AI Act and regional bans: Certain uses of emotion‑tracking AI in workplaces and schools are prohibited or heavily restricted, compelling redesigns and explicit consent/opt‑in architectures.
- Biometric data as special category: Regulations treating facial expression and physiological signals as sensitive biometric data require explicit consent, purpose limitation, and robust minimization strategies.
- State‑level biometric rules: Jurisdictions such as some U.S. states impose strict enforcement mechanisms that translate into litigation and insurance cost considerations for consumer‑facing applications.
- Ethics and explainability: Beyond legal compliance, enterprises must address explainability and harms‑testing to preserve customer trust. Fairness audits and cross‑cultural validations are now procurement must‑haves.
What the full PW Consulting report delivers (practical takeaways)
The report is structured as an executable toolkit for 2026 decision‑makers. Highlights include:
- Market sizing and scenario forecasts (base year 2025; forecast period 2026–2032) with bottoms‑up and top‑down validation.
- Actionable vendor assessment framework: evaluation criteria, due‑diligence checklists, and a vendor short‑listing methodology tailored to deployment model and vertical constraints.
- Integration playbooks: step‑by‑step guidance for embedding emotion analytics into CX platforms, telehealth, automotive safety stacks, and public‑safety workflows without triggering legal risk.
- Data architecture blueprints: reference designs for cloud, edge, and hybrid deployments, including model governance, retraining pipelines, and data‑sovereignty patterns.
- Privacy & ethics toolkit: consent flows, data minimization patterns, record‑keeping templates, and fairness validation protocols compatible with major regulatory regimes.
- TCO and business case templates: quantifiable levers, sensitivity analyses, and operational cost drivers (including the specialized labor required for on‑premise setups).
- Case studies and vendor negotiation playbooks: real procurement scenarios, licensing models, SLAs, and integration pitfalls to avoid.
How to use this intelligence in 2026 — a practical roadmap
- Month 0–3: Risk triage and pilot scoping. Run a regulatory heatmap, identify prohibited use cases, and scope a minimum viable pilot that isolates sensitive modalities and minimizes data retention.
- Month 3–9: Build modular proofs and governance layers. Prefer modular architectures that separate inference, storage, and labeling. Establish consent and audit trails before any production release.
- Month 9–18: Measure, iterate, and industrialize. Move from single‑use pilots to composable services with standardized APIs, model‑explainability dashboards, and operational runbooks for retraining and drift detection.
- Ongoing: Monitor legal and tech shifts. Regulatory interpretations, new fairness metrics, and vendor consolidation are fast moving—build a quarterly review cadence into vendor contracts and product roadmaps.
Recent market signals that justify urgency
- Specialist vendors are shipping privacy‑first, on‑device SDKs and vehicle integrations, accelerating edge use cases that avoid cloud transfer of biometric signals.
- Platform vendors continue to add cross‑cultural emotion models and fairness tooling, lowering integration effort but increasing strategic dependency considerations.
- Regulators have moved from principle statements to enforceable restrictions in several jurisdictions. That transition creates both risk and first‑mover advantage for compliant implementations.
Conclusion and next steps
For executives and product leaders, 2026 is the year to decide how emotion analytics fits into broader AI strategy: whether to adopt specialist solutions for narrowly defined, high‑value use cases; to leverage platform providers for scale; or to defer until regulatory clarity increases. The PW Consulting Emotion Analytics Market report provides the analytical foundation, governance frameworks, and tactical playbooks to make those choices with confidence.
To access the full data tables, granular segmentation, vendor scorecards and implementation templates that are intentionally summarized here, please consult the full report on our website—where the proprietary breakdowns and downloadable assets live. PW Consulting’s research is built to be directly operationalized by procurement, compliance, product, and data science teams preparing for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Emotion Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com