

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Power Sports Market to reach USD 344.8 Million by 2032 at 6.8% CAGR

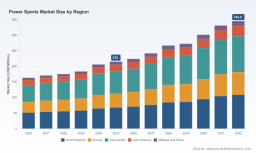
Power Sports Market 2026: A Strategic Preview for Executive Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a high-impact preview of our full Power Sports Market study to help executives make sound strategic choices in 2026. The sector is in clear growth mode: the market expanded from approximately USD 163.2 Million in 2020 to USD 215.0 Million in 2025, and our baseline forecast projects continued expansion to roughly USD 344.8 Million by 2032 at a compound annual growth rate of 6.8% over the 2026–2032 forecast period. This preview synthesizes the implications of those top-line trends for product strategy, go-to-market design, capital allocation, and competitive positioning — while withholding certain proprietary segment breakouts to preserve the full report’s commercial value.
Power Sports Market
Why this research matters for 2026 decisions
- Prioritize investment with confidence: A 6.8% CAGR baseline means steady market expansion, but returns will vary significantly by product configuration, tech investment and route-to-market. Executives must translate macro growth into micro portfolio bets.
- Electrification and software are no longer peripheral experiments — they are strategic imperatives. EV powerpacks and connected features are altering product roadmaps, supplier relationships, and aftersales economics.
- Regulation and public capital are forcing short supply‑chain and dealer-model changes. New certification standards and government park investments reallocate opportunity across rental, fleet, and retail channels.
- Competitive dynamics are shaped by differentiated engineering features and software ecosystems. Product launches in 2025–2026 illustrate how incumbents are pushing on performance, user experience and electrified variants.
Practical contents of the full PW Consulting study (high level)
The full deliverable is designed for immediate operational use and board-level decisioning. It includes:
Power Sports Market
- Top-down market sizing and bottom-up revenue build for 2020–2032, including base, upside and downside scenarios aligned to macroeconomic and adoption assumptions.
- Demand-driver models that translate consumer preferences and policy shifts into quantifiable changes in unit demand and lifetime value by vehicle archetype and channel.
- Roadmaps and feature‑economics: margin and price elasticity analyses for ICE, hybrid and BEV powertrains, including Level 2 charging economics and TCO comparisons.
- Channel and dealer economics: revised dealer-margin models for new product mixes, rental/fleet partners and digital-direct experiments; inventory stress tests under shifting helmet/regulatory norms.
- Supplier and raw-material stress maps, including battery cell sensitivity, power electronics constraints, and mitigation pathways via strategic sourcing and vertical partnerships.
- Competitive positioning matrices, capability gap analyses, and a prioritized M&A target list (screened by technical fit, distribution access and margin uplift potential).
- Playbooks for marketing and OEM co-op redesign to capture digital-first consumer journeys, with sample creative-performance KPIs and ROI thresholds.
Key market dynamics shaping 2026 strategy
Several convergent forces will determine winners and losers in the coming 12–36 months:
Power Sports Market
- Product convergence around experience and software. Recent launches show a dual focus: mechanical performance (advanced suspension, geared reverse, towing capability) and enhanced digital ecosystems (large touch displays, ride-management software, smartphone integration). Expect software monetization opportunities but rising expectations for over-the-air support and UX quality.
- Electrification acceleration. Established OEMs are bringing electric variants to mainstream segments. This shifts cost structures (battery spend, charging enablement) and creates new partnerships with cell suppliers and charging networks.
- Regulatory and public-spend tailwinds. For example, targeted public investments into parks and trails in early 2026 unlock demand for rental fleets, trail-based experiences and public-private partnerships — but also change product specifications for safety and noise compliance.
- Standards and certification changes. Recent rule shifts on permissible helmet certifications and other safety standards force rapid inventory and spec adjustments across retail networks, with direct P&L and warranty impacts.
- Marketing program reallocation. OEM co-op programs are explicitly shifting toward digital advertising and original content; companies that optimize co-op spend for measurable digital outcomes will create outsized advantage.
- Fragmented supplier landscape and concentrated component risk. Battery and power-electronics supply remain the pivotal constraint; firms that secure capacity or vertically integrate selectively will mitigate margin erosion and time-to-market risk.
Competitive landscape — what matters to executives
The leading OEMs remain technologically capable and brand-rich, but each pursues distinct routes:
- Polaris Inc. — Strong in off‑road performance platforms and increasingly focused on connected experiences via vehicle software and integrated displays. Their recent product introductions emphasize suspension and user-control innovations that defend premium segment leadership.
- BRP Inc. — Creative with propulsion: their move into electric ATVs signals an aggressive play on electrified utility and performance offerings. Expect BRP to push on powerpack integration, charging speed and modular battery strategies.
- Yamaha Motor Corporation — Deep engineering pedigree in two- and four-wheel performance, with iterative improvements in traction control and ECU features that appeal to enthusiast segments. Yamaha blends mechanical refinement with incremental electronics integration.
- Honda Motor Co., Ltd. — Leveraging global scale across powertrains and distribution; their advantage lies in manufacturing discipline and cost control as the market bifurcates between premium tech-led models and value-conscious mainstream units.
- Harley-Davidson, Inc. — Premium motorcycle brand expanding its feature set and rider assistance systems. Their product launches show an emphasis on ride comfort, integrated infotainment and accessory ecosystems for higher-margin sales.
For challengers and mid-market players, the strategic choices are binary: invest materially in electrification, software and digital distribution — or consolidate around niche strengths such as rental fleet partnerships, regional manufacturing or aftermarket specialization.
2026 decision playbook — a concise roadmap
- 0–90 days (stabilize & prioritize): Run a scenario overlay using the study’s baseline CAGR (6.8%) and stress cases; reassign near-term capex to product lines with the shortest path to positive free cash flow. Audit dealer inventory for regulatory compliance and safety certification exposure.
- 3–6 months (test & iterate): Pilot an EV product in a controlled geography with a charging and service partner; deploy a revamped OEM co-op pilot that favors digital content and trackable conversions; sign conditional supply agreements with cell providers.
- 6–12 months (scale & defend): Harden software-delivery processes, roll out subscription services where unit economics are favorable, and negotiate dealer economics rebalancing that rewards service and digital lead conversion.
- 12–24 months (transform): Accelerate any necessary M&A for battery or software capabilities, commit to targeted manufacturing retooling for EV powerpacks, and institutionalize data-driven marketing to capture lifetime value improvements.
Risk vectors and mitigation
- Supply shocks — secure conditional contracts, diversify supplier base, and model inventory buffers in our scenario toolset.
- Regulatory surprises — maintain a regulatory watchlist and a rapid-spec-change operating cadence with dealer partners to reduce stock write-offs.
- Channel displacement — invest in dealer digital enablement and performance-based co-op models to preserve physical network viability while pursuing digital direct channels.
- Consumer adoption lags for EVs — match incentives, warranty structures and charging partnerships to bridge TCO perception gaps.
How to use the full PW Consulting report
This preview outlines the strategic levers and the operational playbook. The full report contains the proprietary, granular segment and regional tables, sensitivity-tested financial models, and executable annexes (including a prioritized M&A screen and a dealer economics workbook) that your strategy, product and finance teams can plug directly into scenario planning and board materials.
We have intentionally withheld the detailed segment-level splits and certain granular dashboards to preserve the competitive value of the comprehensive study. To access the complete dataset, downloadable models, and an executive briefing tailored to your organization’s position in the value chain, please visit our report page or contact PW Consulting’s advisory team for a confidential briefing.
In short: the Power Sports market is growing, technologically active, and strategically consequential for 2026 decisions. Firms that align capital to electrification and software, redesign co-op and dealer economics for digital-first consumer journeys, and lock down critical supply relationships will capture the disproportionate share of upside as the market matures toward 2032.
For detailed analysis of this topic, please visit the official page: Power Sports Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com