

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sodium Dichromate Market Poised for 5.2% CAGR Through 2032

Sodium Dichromate Market — Strategic Briefing for 2026 Decision Makers
As PW Consulting’s Chief Industry Analyst, I present a targeted preview of our forthcoming Sodium Dichromate Market study — a synthesis of market mechanics, regulatory inflection points, supply dynamics, and strategic options that senior executives and investment committees must factor into 2026 planning cycles. This briefing highlights the report’s strategic value, core conclusions at the market level, and the practical, decision-ready analysis contained in the full report. Detailed segment-level tables and proprietary models are intentionally omitted here to preserve the value of the full study and direct readers to the source for actionable granularity.
Sodium Dichromate Market
Why this study matters for 2026
-
Timing: the market is at a crossroads. Our base year is 2025 and our forecast horizon extends through 2032. Between 2020 and 2025 the global sodium dichromate market grew from a measured baseline to a materially larger industry, and our forward model — using a 5.2% CAGR across the forecast period — indicates continued expansion under multiple stressors and opportunities.
Sodium Dichromate Market -
Regulatory inflection: recent regulatory actions in Europe (notably the European Chemicals Agency’s April 2025 intent to propose restrictions under REACH, the listing of sodium dichromate on the Candidate List, and the fact that Cr(VI) substances are subject to authorization under REACH Annex XIV) materially increase compliance complexity and potential market reconfiguration for 2026 and beyond.
Sodium Dichromate Market -
Supply-chain and feedstock sensitivity: chromite ore remains the primary feedstock; volatility and geopolitical exposure in ore supply chains create earnings and supply risk for producers and downstream integrators. Procurement strategies implemented in 2026 will lock in exposures through several years and thus must be informed by robust scenario analysis.
Market snapshot — headline macro numbers
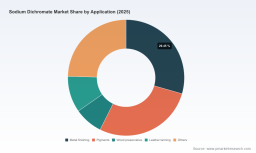
At the market level, our analysis consolidates global revenues in USD (Million). From a baseline near USD 1.22 billion in 2020, the market expanded to roughly USD 1.52 billion by the 2025 base year. Using our forecast assumptions and a 5.2% compound annual growth rate (CAGR) for the period 2026–2032, the market is projected to approach just over USD 2.17 billion by 2032. These aggregate figures encapsulate demand across metal finishing, pigments, wood preservation, leather tanning and other industrial applications, while excluding detailed breakdowns that are available in the full report.
Market concentration is moderate: the top three firms account for roughly one‑third of global market revenue, and the top five firms only modestly increase that share. This structure signals meaningful space for regional specialists and low-cost producers to exert influence, even as certain incumbents leverage scale and distribution networks.
Key dynamics shaping 2026 decisions
-
Regulatory pressure and substitution pathways — The recent ECHA activity marks a substantive shift: potential REACH restrictions and authorization requirements raise the cost of market participation for producers and users in Europe and for exporters to EU markets. Companies should treat regulatory exposure not as a binary compliance matter but as a strategic force that reshapes pricing power, supply chains, and product portfolios. The report provides a ranked matrix of exposure by use-case and region (full proprietary data in the report).
-
Demand composition — End-use demand remains diversified across industrial applications. While traditional metal finishing and pigment uses continue to anchor volumes, innovation and regulatory signals are accelerating the search for lower‑chromium alternatives in specific subsegments. Our scenario work identifies which end uses are most likely to see substitution pressure before 2032 and where premium, compliant grades can command a margin uplift.
-
Feedstock and input-cost volatility — Chromite ore dynamics govern variable cost for sodium dichromate production. The report models several supply‑shock scenarios and their pass-through effects on producer margins and downstream pricing, offering practical hedging and contract structures for procurement teams.
-
Consolidation and regional specialization — Given the moderate concentration ratio and the cost of environmental compliance, the market is primed for selective consolidation in regions where regulation raises barriers to entry and for fragmented competition where lower-cost feedstock and less stringent enforcement prevail.
What the full report contains — practical, actionable modules
-
Executive dashboard: concise, C-suite-ready market sizing, growth scenarios, and heat maps of regulatory and supply risk at the market and submarket level (proprietary tables and downloadable models are available in the full product).
-
Demand forecasting by use-case: bottom-up models explaining drivers in metal finishing, pigments, wood preservation, leather processing and 'other' industrial uses, with sensitivity testing under alternative regulatory and raw-material circumstances.
-
Supply and trade: plant-level capacity mapping, trade-flow analysis, and an assessment of logistics chokepoints and export control exposure. This section includes practical scenario playbooks for sourcing and inventory strategy.
-
Regulatory impact assessment: authoritative review of REACH developments, authorization timelines, and national/regional regulatory permutations. We translate legal exposure into quantifiable cost impacts and market access scenarios for 2026–2028.
-
Competitive profiling: in-depth dossiers on manufacturers and distributors, capability maps, product specifications, packaging and logistics practices, and recent investments. Profiles include strategic assessments of capacity expansion plans, product purity positioning, and export orientation.
-
Value-chain risk and mitigation playbook: practical recommendations for procurement, product stewardship, customer contracts, and R&D investment to secure demand under tightening regulation or feedstock shocks.
-
M&A and partnership opportunities: target identification and valuation frameworks for acquirers and investors, including playbooks for integrating capacity, closing supply gaps, or accessing compliant formulations.
Competitive landscape — what executives need to know now
Our public-entity and primary-research synthesis highlights a group of established producers who collectively shape market dynamics. These companies range from integrated producers with export capabilities to regional specialists serving domestic markets. Key companies examined in the report include, among others, Vishnu Chemicals Limited (India), Nippon Chemical Industrial Co., Ltd. (Japan), Hubei Zhenhua Chemical Co., Ltd. (China), Yinhe Group (China Yinhe Chemical Industry Group), and Soda Sanayii A.S. (Turkey). Each profile assesses production technology, product purity positioning, packaging/logistics capabilities, and strategic moves such as capacity expansion or export orientation.
Illustrative takeaways from our company analysis (high level):
-
Some Asian producers emphasize scale and cost-competitiveness for bulk industrial grades, with broad distribution networks across regional end-users.
-
Producers in developed markets and select Asian manufacturers focus on high‑purity grades for demanding applications such as aerospace and specialized chemical synthesis, investing in quality assurance and certifications that support premium pricing.
-
Several firms have signaled capacity investments to meet growing export demand; however, regulatory constraints in key consuming markets create uncertainty about future access and margin stability.
Strategic actions for 2026 — a pragmatic checklist
-
Reassess procurement contracts now: lock in pricing and volume flexibility clauses tied to feedstock indices and regulatory milestones. Short‑dated contracts with trigger-based renegotiation clauses are prudent as the REACH process unfolds.
-
Prioritize compliance and traceability investments: invest in upstream traceability of chromite ore sourcing, product stewardship systems, and documentation to facilitate market access under evolving authorization regimes.
-
Evaluate product portfolio rationalization: identify high-risk SKUs and high-margin compliant formulations. Redirect R&D to alternative chemistries where substitution risk is high and commercial feasibility exists.
-
Plan for regional shifts: model demand and profitability under scenarios that assume tighter EU access. Consider near‑market partnerships or tolling arrangements to maintain EU presence if direct exports become constrained.
-
Use M&A selectively to secure feedstock or compliant capacity: target assets that offset regulatory risk (e.g., facilities with advanced waste handling and emissions controls) or that provide access to critical customers under long-term contracts.
How PW Consulting informs your 2026 roadmap
The full Sodium Dichromate Market report is built to be operationally useful: our models are distributed in editable spreadsheets, our regulatory impact matrices are calibrated to likely timelines, and our scenario work includes decision gates tailored for CFO, COO, and Head of Procurement audiences. The study converts complex regulatory and supply signals into prioritized actions with quantified P&L and cash-flow implications across a range of realistic 2026 scenarios.
In short: for executives weighing capital deployment, sourcing strategies, or M&A in 2026, this study provides the market-level orientation, risk quantification, and playbooks needed to make informed, defensible decisions — while the full dataset and granular segmentation remain gated within the complete report to preserve their commercial value.
Next steps
For teams preparing 2026 budgets, procurement roadmaps, or strategic investment memoranda, we recommend procuring the full report to access the proprietary segment matrices, supplier scorecards, and downloadable scenario models. PW Consulting stands ready to run bespoke stress tests on your specific supply contracts and product mix and to facilitate workshops that translate the report’s insights into executable 90‑, 180‑ and 360‑day plans.
For detailed analysis of this topic, please visit the official page: Sodium Dichromate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com