

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Wood Furniture Market to Reach USD 325B in 2025; 4.95% CAGR Ahead
By pmarketresearch, 2026-07-23
Wood Furniture Market 2026: Strategic Imperatives from PW Consulting
As firms prepare capital allocation, supply-chain moves, and product roadmaps for 2026, the wood furniture sector is at a strategic inflection. Our latest Wood Furniture Market study — calibrated to a 2025 base year and projecting through 2032 — synthesizes historical performance (2020–2025), near-term shocks, and mid-term structural trends into an actionable decision-readiness framework. The global market, estimated at USD 325.0 Billion in 2025, is projected to advance at a compound annual growth rate (CAGR) of 4.95% across the forecast window, pushing overall value materially higher by 2032. For executive teams, the distilled question is simple: how do you convert this macro tailwind into durable, defensible profit pools while navigating regulatory and trade volatility?
Wood Furniture Market
What this research delivers — pragmatic intelligence, not theory
- Robust market sizing and a dynamic forecasting model (2026–2032) that integrates base-year validation, scenario overlays, and sensitivity to tariff and raw-material inputs.
- Regulatory and trade-impact modules that quantify near-term earnings and supply-chain stress under policy shocks (tariffs, duties, and traceability mandates).
- Supply-chain risk heatmaps, supplier concentration indices, and a practical supplier resilience playbook for rapid implementation.
- Competitive benchmarking and strategic options for incumbent manufacturers, pure-play artisans, and omni-channel retailers — including M&A playbooks and value-creep mitigation strategies.
- Commercial go-to-market templates for product premiumization, modularization for urban living, and digital direct-to-consumer acceleration.
- Implementation roadmaps, prioritized by ROI and execution risk, to convert insight into 90/180/365 day actions.
Note: this article demonstrates the depth of our analysis but intentionally omits the detailed regional and application-level tables and unit economics that are included in the full report. Those core segmentation matrices are available through the report landing page and client portal.
Wood Furniture Market
Where the market stands in early 2026 — concise takeaways
- Macro trajectory: The sector’s trajectory is healthy — an above-inflation growth profile in nominal terms driven by persistent consumer demand for higher-quality furnishings, elevated renovation cycles, and rebound in commercial fit-outs in select markets.
- Fragmentation and consolidation potential: Market concentration metrics point to a fragmented industry (CR3 ≈ 23.5%; CR5 ≈ 31.5%), which creates scope for strategic consolidation, roll-up strategies, and bolt-on supply assets that capture scale economics in procurement and distribution.
- Regulatory and trade inflection points: Policy moves enacted in late 2025 and early 2026 materially change cost and compliance dynamics — these are not transitory inconveniences but structural inputs that should reframe sourcing, pricing, and product design.
Policy and supply dynamics executives must internalize now
- Tariff and duty regime: A series of U.S. trade measures implemented in late 2025 imposes ad valorem tariffs on timber and on certain finished wood products, with escalations effective early 2026. Simultaneously, anti-dumping and countervailing actions have amplified landed costs for key inputs originating from traditional suppliers — a dynamic that has already elevated regional lumber prices and margins for some domestic producers.
- Traceability and provenance: From December 30, 2025, EU-level traceability requirements (EUDR) create mandatory due diligence for timber entering the European market — forcing global players to redesign multi-country supply chains and documentation practices.
- Raw-material reality: Domestic timber production remains sizable in traditional supplier markets; for example, U.S. softwood output provides a substantial primary raw-material base. Yet production does not insulate downstream makers from price and availability shocks when policy and global demand shift concurrently.
Competitive landscape: strategic archetypes and tactical responses
Our analysis profiles leading firms across three archetypes: mass-market integrators, office/contract specialists, and premium/handcrafted artisans. Each archetype faces distinct playbooks for 2026.
Wood Furniture Market
- Mass-market integrators (e.g., Ashley Furniture Industries) — Their advantages are scale, distribution reach, and merchandising. Near-term priorities: tariff pass-through strategies, inventory hedging, and SKU rationalization to protect margins while maintaining shelf velocity.
- Office and contract specialists (e.g., HNI Corporation, Haworth Inc.) — Exposure to commercial cyclicality and supply-chain lead times make hybrid manufacturing footprints and modular product design key to regaining time-to-contract and improving margin resilience.
- Premium/handcrafted artisans (e.g., Vermont Woods Studios, Furnirem, Whittier Wood, Stickley, Arista Wood) — These brands can capture premiumization upside by emphasizing provenance and sustainable sourcing. However, they must operationalize traceability and third-party verification to convert sustainability claims into commercial premiums, especially for markets bound by EUDR.
Recent tactical moves underscore playbook evolution: Furnirem’s March 2026 product-line expansion demonstrates how urban-living features (nesting, integrated storage) can unlock incremental ASPs and new household penetration. Arista Wood’s rebranding in February 2026 signals a strategic pivot toward reclaimed and fine hardwood narratives that align with sustainability-conscious consumers — a positioning that, if paired with rigorous traceability, can command category differentiation.
Risk vs. opportunity: concise matrix for 2026 planning
- Top downside risks: tariff-induced margin compression, compliance costs from traceability mandates, raw-material price spikes, and execution failure on nearshoring or supplier diversification plans.
- High-conviction opportunities: premium solid-wood and reclaimed-wood segments, integrated servicing (refinishing, buyback), modular designs for high-density housing, digital customization platforms, and targeted consolidation to capture procurement synergies.
- Short-term arbitrage: suppliers with domestic resource access or vertically integrated timber holdings can monetize price arbitrage; non-compliant supply chains face market access risk in regulated geographies.
Concrete actions for 90–365 day decision windows
- 90 days: Launch a supply-contract stress test. Quantify exposure to tariff schedules and antidumping outcomes; renegotiate clauses to include force majeure and pass-through triggers where feasible.
- 180 days: Execute a prioritized traceability pilot for at-risk SKUs destined for EUDR markets. Integrate chain-of-custody documentation into ERP and supplier scorecards.
- 365 days: Reconfigure footprint where warranted. Consider nearshoring low-value, high-weight SKUs, and locking in strategic timber supply via JV or long-term offtake to stabilize input costs.
- Ongoing: Institute a portfolio management cadence — retire low-turn, low-margin SKUs, accelerate premiumization initiatives, and deploy targeted M&A for distribution or procurement scale.
Why PW Consulting’s report is strategically different
- Action orientation: Every analytical output maps to a decision and an operational owner — whether procurement, product, commercial, or corporate development.
- Scenario-native forecasting: Beyond a point forecast (our base-year validated model indicates an immediate-year step-up into 2026), we deliver tariff and regulatory scenario modules that show P&L and working-capital sensitivity under alternative policy trajectories.
- Competitive playbooks: We combine primary interviews, trade-level channel economics, and public filings to generate executable options — from small cap bolt-ons to large-scale M&A — matched to the organization’s capabilities and appetite for change.
- Implementation-first deliverables: Templates, vendor-selection checklists, and a 12-month change-management timeline to move from strategic intent to measurable outcomes.
Final perspective: convert visibility into optionality
2026 will not be a year for passive planning in the wood furniture industry. Policy shifts, rising input volatility, and evolving consumer preferences will reward firms that combine a disciplined financial view with operational nimbleness and regulatory compliance. The market’s long-term growth path is intact — the challenge is capturing the right share of that growth while insulating earnings from tariff and compliance shocks. With market concentration still relatively low, the window for strategic consolidation and capability-driven differentiation remains open.
Our full Wood Furniture Market report contains the detailed segment tables, regional breakdowns, supplier heatmaps, and the functional toolkits executives need to act this year. Those granular datasets and playbooks are intentionally not reproduced here; they are embedded in the report’s interactive model and appendices. For access to the complete dataset, scenario files, and tailored implementation support from PW Consulting’s industry team, please visit the report landing page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Wood Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hookah (Shisha) Tobacco Market Poised for 6.98% CAGR Through 2032
By pmarketresearch, 2026-07-23
Hookah (Shisha) Tobacco Market — Strategic Briefing for 2026 Decision-Making
Executive snapshot
By 2025 the global Hookah (Shisha) Tobacco market reached an estimated USD 215.0 Million (base year 2025), having expanded steadily during the 2020–2025 historical window. Our forecast model projects the market to grow to approximately USD 344.8 Million by 2032, implying a compound annual growth rate (CAGR) of roughly 6.98% across the 2026–2032 forecast period. Market concentration remains low: the top three and top five producers together account for roughly a quarter of the market, underscoring a highly competitive, fragmented landscape with ample space for differentiation.
Hookah (Shisha) Tobacco Market
Why this study matters for 2026 strategic planning
-
Timing matters: 2026 is the hinge year for firms planning new product launches, channel expansion, or M&A activity. Our research synthesizes macro growth drivers, regulatory inflection points, and competitive moves so that leadership teams can prioritize investments with a 3–5 year horizon in mind.
Hookah (Shisha) Tobacco Market -
From volatility to advantage: the market’s steady mid-single-digit CAGR hides pockets of rapid premiumization and regulatory-driven re-segmentation. Companies that convert regulatory constraints into distribution or product advantages will capture outsized share.
Hookah (Shisha) Tobacco Market -
Actionable intelligence: this brief highlights the tactical playbooks and the risk mitigants that proved decisive for market leaders in 2024–2025, allowing executives to build concrete 2026 roadmaps rather than abstract strategies.
Market dynamics shaping 2026
-
Premiumization and flavor innovation continue to be primary revenue drivers. Brands that combine novel flavor profiles with premium packaging and single-serve convenience are commanding higher margins in core urban centers.
-
Regulatory reclassification and local restrictions are altering unit economics. For example, the Hookah Clarification Act of 2025 in the United States created a distinct tax classification for waterpipe tobacco (amended tax rate specified at USD 0.5662 per pound), shifting pricing and margin calculus for imports and domestically distributed products. Similarly, state-level restrictions such as the California Flavored Tobacco Sales Law (2026) change where flavored shisha can be sold and how retail compliance is managed.
-
Alternative formulations and tobacco-free substitutes are emerging as defensive and offensive plays. Manufacturers that invest in tobacco-free or hybrid formulations gain shelf-space in regulated jurisdictions and new consumer segments concerned about perceived health trade-offs.
-
Channel evolution: lounge and experiential channels remain brand-critical, but online specialty retailers and subscription models are becoming meaningful acquisition and retention conduits—especially for premium and limited-edition releases.
Competitive landscape — who’s shaping the market
The market is characterized by a mix of long-established regional producers, innovative boutique brands, and industrial-scale manufacturers. Notable firms included in our analysis represent different strategic archetypes:
-
Al Fakher Tobacco Factory (Ajman, UAE) — a volume-focused legacy brand that leverages broad flavor portfolios; recent strategic moves include celebrity collaborations aimed at premiumization and cultural resonance.
-
Adalya Tobacco (Izmir, Turkey) — export-led strategy with emphasis on fruity premium blends and diversification across markets through licensed distribution partners.
-
Fumari (San Diego, USA) — boutique premiumizer: small-batch formulations, flavor-lock packaging, and a rapid product cadence designed to sustain premium price points and direct-to-consumer loyalty.
-
Afzal Shisha (India) — large-scale production capability combined with localized flavor innovation; one of the global volume producers with wide export reach.
-
Nakhla Tobacco Company (Cairo, Egypt) — heritage positioning and strong traditional segment credentials, with distribution networks that support cross-border flows.
-
Mujeeb Sons (India) — notable for product diversification into 100% tobacco-free substitutes, a strategic response to shifting consumer preferences and regulatory hurdles.
-
Al Waha (METCO, Jordan) — premium molasses and flavored blends focused on lounge and cafe channels.
-
Starbuzz Tobacco (Lake Forest, USA) — brand-led premium portfolio with attention-grabbing flavor series and consumer marketing designed to drive lifestyle affinity.
Recent industry moves are illustrative. In late 2025, Al Fakher launched celebrity-partnered flavors, signaling a deliberate pivot to cultural co-branding as a differentiation lever; Fumari continued its product cadence with new dessert-forward releases in mid-2025; and several players adjusted pricing to reflect input-cost and tax changes earlier in 2025. Each of these actions offers a template for how product, pricing, and marketing levers can be coordinated in response to external shocks.
Practical segments and incubation opportunities
-
Premium flavored blends and experiential consumables: higher margin, brand-dependent, and best supported by lounge partnerships and DTC distribution.
-
Tobacco-free and hybrid formulations: strategic hedge for channels or jurisdictions where flavored tobacco sales are restricted; high potential for private-label and white-label supply agreements.
-
Single-serve and convenience packaging: addresses out-of-home consumption patterns and reduces friction for occasional users while enabling premium pricing per use-case.
-
Adjacent product ecosystems: coal/heating tech, disposable devices, and flavor enhancers offer cross-sell opportunities and can lock-in customers over longer lifetime cycles.
Regulatory and supply-side risk matrix
-
Taxation shifts and classification risk: changes like the 2025 U.S. tax amendment materially affect landed cost and upstream pricing models; scenario modeling should be built into procurement and pricing systems immediately.
-
Point-of-sale restrictions: localized laws restricting flavored tobacco sales to specific outlet types necessitate differentiated channel strategies and compliance programs.
-
Raw material variability: leaf quality, flavoring concentrates, and supply chain bottlenecks can create short-term margin pressure—multi-sourcing and forward contracting should be evaluated.
-
Public health campaigns and consumer sentiment: reputational management and transparent labeling will be increasingly important for access to mainstream retail and foodservice partnerships.
Strategic playbook for 2026 — prioritized actions
-
Reprice intelligently: incorporate new tax treatments and projected input-cost trajectories into a tiered pricing architecture that protects low-end volume while capturing premium margins.
-
Product portfolio optimization: accelerate tobacco-free SKUs and single-serve formats for regulated markets; pilot celebrity or culture-driven collaborations in targeted metros to test premium elasticity.
-
Channel-sharp GTM: treat lounges as marketing and R&D labs for experiential products, while using online specialty retailers and subscription bundles to scale niche premium SKUs.
-
Operational resilience: hedge leaf purchases, diversify manufacturing footprints across trade zones, and adopt modular production to switch between tobacco and tobacco-free recipes quickly.
-
Regulatory readiness: implement a regulatory-watch framework and a compliance playbook for rapid adaptation to jurisdictional restrictions on flavored tobacco.
What the full PW Consulting report delivers (practical contents)
-
Proprietary market model (2020–2032) with scenario outputs—base, downside (regulatory-intensive), and upside (premium acceleration).
-
Channel and pricing playbooks that translate tax and regulation scenarios into concrete pricing ladders and margin impact analyses.
-
Go-to-market roadmaps for premium launches, tobacco-free rollouts, and lounge partnership pilots—each with resourcing templates and 12–18 month KPIs.
-
Competitive battle-cards for key players including product positioning, recent moves, and white-space opportunities.
-
Supply-chain stress-tests and sourcing strategies, including recommended hedging instruments and contract structures.
-
Regulatory and compliance matrix by jurisdiction, with playbooks to preserve market access where flavored products face restrictions.
-
M&A and partnership screening framework, designed to prioritize targets that accelerate premiumization, distribution reach, or formulation capabilities.
Note: This brief intentionally summarizes the strategic implications and hides granular segmentation tables and regional/application splits. The full report contains detailed sub-segment revenue breakdowns, market-share matrices, and downloadable model files that are essential for transaction diligence and internal strategy execution.
How to use this intelligence in 90 days
-
Immediate (0–30 days): Run the tax-and-cost re-price scenario across current SKUs; freeze promotional discounts that erode margin under the new tax or input cost environment.
-
Short-term (30–90 days): Pilot a tobacco-free SKU in one or two regulated states or controlled lounge partners; negotiate forward contracts for primary leaf inputs and set a monitored replenishment cadence.
-
Medium-term (90–180 days): Deploy a premium-limited run tied to a cultural or celebrity partnership to test elasticity and DTC acquisition economics; align legal and compliance teams around state-level flavored sales limitations.
Closing perspective
The Hookah (Shisha) Tobacco market in 2026 is not a single story of growth or decline—it is a mosaic of premiumization, regulatory constraints, product innovation, and channel evolution. With a base of USD 215.0 Million in 2025 and a modeled path to roughly USD 344.8 Million by 2032 at a near‑7% CAGR through the forecast window, the opportunity exists for disciplined players to scale profitably. However, actionable advantage will come from integrating regulatory intelligence, product design, and distribution execution into a single operating rhythm.
PW Consulting’s full study provides the granular forecasts, competitive maps, and executable playbooks needed to convert this strategic view into measured action. Access the complete dataset and model files on our research portal to power 2026 decisions with confidence.
For detailed analysis of this topic, please visit the official page: Hookah (Shisha) Tobacco Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acupuncture Needles Market to Reach USD 344.8 Million by 2032
By pmarketresearch, 2026-07-23
Acupuncture Needles Market — Strategic Briefing for 2026 Decisions
Between 2020 and 2025 the global acupuncture needles market experienced steady expansion, rising from roughly USD 163 million to an estimated USD 215 million in 2025 (base year). Our forward view models a continuation of that growth into the next planning cycle: the market is forecast to grow through 2026–2032 at a compound annual growth rate of approximately 6.98%, reaching an implied near‑term target in the mid‑300s million USD by 2032. For commercial leaders and investors preparing budgets, product roadmaps and M&A agendas for 2026, these macro trajectories frame the opportunity set, but the real value lies in translating top‑line growth into defensible, executable strategies across regulatory, procurement, manufacturing and distribution functions.
Acupuncture Needles Market
Why this research matters for 2026 planning
Market size and growth rates are necessary but not sufficient inputs for strategic decisions. Our research converts those macro indicators into operational levers: where to prioritize certification and quality investments, which manufacturer and distributor archetypes will win share as clinical practice standards harden, how reimbursement and coding norms will influence purchasing behaviors, and which supply‑chain vulnerabilities could interrupt access to sterile, single‑use products. This is particularly important for 2026, when buyers and regulators increasingly expect traceability, ISO‑grade quality systems and demonstrable post‑market surveillance programs as a baseline for procurement.
Acupuncture Needles Market
Key demand and supply dynamics shaping near‑term strategy
-
Clinical and professional demand is rising in tandem with broader acceptance of integrative medicine. The result is predictable volume growth but divergent value capture across product types: premium, precision needles and supply‑chain certified disposables command pricing power; commodity lines compete on cost and logistics.
Acupuncture Needles Market -
Regulatory rigor is intensifying. Acupuncture needles are regulated as Class II medical devices in the U.S., triggering sterilization, single‑use labeling and biocompatibility requirements for devices marketed to licensed practitioners. Parallel expectations—such as adherence to ISO 13485 for manufacturers selling into international markets—are becoming non‑negotiable market access gates. These rules materially affect product design, labeling, and capital needs for contract manufacturers.
-
Reimbursement practices blunt unit‑level price transparency. In several payor systems, the cost of needles is bundled into acupuncture service codes, limiting the extent to which providers can pass through device costs directly. Practically, this forces suppliers to work more closely with clinics and hospitals on total cost of care propositions—reducing per‑needle cost while improving procurement efficiency and after‑sales support.
-
Material and manufacturing economics favor established producers with automated precision lines. Surgical‑grade stainless steel wire is the industry standard for biocompatibility and handling characteristics, and supply security for this raw material is a contingent factor for continuity of supply.
-
Quality events and vigilance data increasingly influence buying committees. Public adverse event records (for example, a reported foreign‑body retention associated with a well‑known product in 2024) have elevated the importance of device traceability, lot control and rapid recall protocols in procurement evaluations.
Competitive landscape — what incumbents and challengers tell us
The market retains a mix of long‑established branded manufacturers, regional players with strong distribution ties, and specialized distributors. A short, non‑exhaustive reading of the competitive set illustrates the strategic vectors that buyers, partners and acquirers should monitor:
-
Seirin Corporation (Shizuoka, Japan; https://www.global.seirin.jp/english/): a recognized leader in precision and “painless” needle engineering with automated manufacturing lines and multiple disposable product families. Its sustained investment in branding and quality positioning makes it a benchmark for premium clinical offerings and a potential price‑maker in segments prioritizing practitioner experience and patient comfort.
-
AcuMedic (London, UK; https://www.acumedic.com/): a distributor and service provider model focused on premium sterile single‑use and reusable formats. Distributors with clinical‑services capability are increasingly important intermediaries for market entry and for educating institutional buyers on bundled procurement and inventory management.
-
Suzhou Medical Appliance Factory — Hwato brand (Suzhou, China; http://www.hwato-med.com/): a legacy manufacturer with deep production scale, multiple international certifications and strategic distribution partnerships. Recent moves to formalize distribution into the U.S. illustrate a supplier pathway to capture licensed practitioner demand via local partners, not just direct export.
-
Dongbang Medical (Woorim, South Korea; https://dbneedle.com/): a specialist in siliconized stainless‑steel lines, supplying CE/FDA/ISO‑certified options. Suppliers focused on material science and process improvements are well positioned to defend against commoditization by differentiating on insertion comfort and reduced tissue trauma.
-
Other notable manufacturers (Wuxi Jiajian, Asiamed, and similar regional OEMs) are actively pursuing export certifications, trade show presence and distributor agreements to broaden their reach. Participation in major events and targeted distribution deals in 2025–2026 shows a push to convert production scale into international market share.
Recent commercial and go‑to‑market signals
-
Distribution partnerships continuing into late 2025 demonstrate that established practitioners still prefer procuring familiar brands through local or specialized wholesalers—these partnerships reduce friction for regulatory compliance and post‑sale support.
-
Visibility at leading medical trade forums underscores an industry pivot to clinical buyers in hospitals and health systems; expect product messaging to shift from traditional TCM markets toward evidence‑based clinical benefits and safety credentials.
What the full report delivers (practical contents for corporate use)
Our full PW Consulting report translates the macro outlook into step‑by‑step tools and templates for 2026 execution. Highlights include:
-
Market sizing and forward scenarios (base year 2025; historical 2020–2025 context; 2026–2032 forecast with sensitivity bands), allowing finance teams to stress‑test P&L assumptions.
-
Supplier scorecards and a manufacturing capability map, enabling procurement to shortlist partners based on certifications, automation maturity, and contingency planning.
-
Regulatory matrix and compliance checklist (U.S. FDA Class II expectations, ISO 13485 alignment, labeling and sterility requirements), designed for product managers and regulatory affairs teams accelerating time to market.
-
Reimbursement and contracting playbook that integrates local coding realities and hospital purchasing behaviors—practical for commercial teams designing pricing and bundling strategies.
-
Post‑market surveillance and risk mitigation playbook, highlighting traceability best practices and recall protocols informed by public vigilance data.
-
M&A and partnership scouting list with investment theses and integration checklists for target diligence—helpful for corporates seeking bolt‑on optics or scale plays.
Actionable recommendations for 2026
-
Prioritize ISO 13485 and related certification investments now. For organizations entering new markets in 2026, certifications will be gating factors for distributor agreements and hospital tenders.
-
Build procurement scenarios that assume bundled payments for services. Needle suppliers should articulate total cost of ownership (TCO) propositions—inventory optimization, 반환/reorder automation, and waste handling—to maintain margin in bundled billing environments.
-
Invest in traceability and lot‑level control. Buyers and regulators increasingly expect rapid root‑cause analysis when adverse events are reported; suppliers with end‑to‑end digital traceability will be preferred.
-
Design a dual channel approach: maintain relationships with established distributors for clinical reach while piloting direct models with large integrated health systems where scale warrants it.
-
Scan suppliers for raw material supply resilience. Secure agreements or second sources for surgical‑grade stainless steel wire to avoid production disruptions and defend lead times.
How to use this briefing and next steps
This note is intended as a condensed strategic companion to the full PW Consulting Acupuncture Needles Market report. It highlights the decision levers that matter in 2026, but it deliberately omits granular segment tables and region‑by‑application breakdowns that are essential for procurement scoring, commercial segmentation and site‑level rollout. Those tables, supplier performance metrics and playbook templates are contained in the full deliverable.
If your 2026 planning cycle includes procurement renegotiations, product portfolio prioritization, or M&A screening, the full report supplies the data and the executable templates your teams will need to move from intent to action. Reach out to PW Consulting to obtain the complete dataset, customizable scorecards and our implementation workshop offering to translate insights into prioritized initiatives for the coming fiscal year.
For detailed analysis of this topic, please visit the official page: Acupuncture Needles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acrylic Impact Modifier (AIM) Market to Reach USD 4.13B by 2032 at 5.7% CAGR
By pmarketresearch, 2026-07-23
AIM (Acrylic Impact Modifier) Market — Strategic Snapshot for 2026 Decision Makers
Executive overview
As strategic advisors to senior leadership teams, we prepared the PW Consulting AIM Market study to convert technical polymer-market signals into executable choices for 2026. The Acrylic Impact Modifier (AIM) market has demonstrated steady expansion through the last half-decade and continues on a multi-year growth trajectory. Using a 2025 base year and a historical window of 2020–2025, our modelling projects the market through 2026–2032. The market is measured in Billion USD, expanded from the low‑single‑digit base in 2020 to a materially larger base by 2025, and our forecast trajectory implies a compound annual growth rate (CAGR) of 5.7% across the modelling horizon. These headline dynamics create a planning environment where investments in capacity, product development, and commercial differentiation can deliver measurable upside — provided organizations act with a clear view of risk exposures and competitive positioning.
AIM (Acrylic Impact Modifier) Market
Why this study matters for 2026 corporate strategy
- Investment timing: With a mid‑single‑digit CAGR and an observable inflection in demand patterns post‑2025, deployment timing for brownfield or greenfield capacity will materially affect unit economics. Our study maps where near‑term demand gaps and mid‑term surpluses are most likely to emerge under alternate scenarios.
- Supply‑chain resilience: Raw material volatility and logistical shifts are now first‑order issues. The report evaluates feedstock cost sensitivity and provides an actionable matrix for securing methyl methacrylate, butadiene, and other precursor streams under different supply scenarios.
- Product and go‑to‑market choices: The AIM space is bifurcating along performance and sustainability dimensions (e.g., low‑temperature performance vs. bio‑based credentials). The research distils which technical levers produce the highest margin expansion for PVC profile, pipe, and outdoor applications, and offers commercialization playbooks for each route.
- Regulatory and reputational risk management: Emerging regulatory debates in the EU on phthalate and heavy‑metal stabilizers — plus accelerating incentives for recyclable and bio‑based modifiers — change the risk/return calculus for incumbents and new entrants alike. We translate those regulatory signals into compliance roadmaps and capex prioritization recommendations.
What the report delivers — practical contents
- Quantitative demand model: An integrated bottom‑up demand model covering the historical period and a seven‑year forecast window, with scenario toggles for raw material price shocks, regulatory constraints, and substitution dynamics.
- Commercial playbooks: Tailored go‑to‑market frameworks for specialty producers, commodity AIM suppliers, and PVC compounders — including pricing tactics, channel prioritization, and OEM engagement strategies.
- Supply and cost benchmarking: A modular toolkit to assess feedstock exposure, unit cost curves, and break‑even capacity thresholds across alternative technologies and geographies.
- Technology and product roadmaps: Comparative profiles of emerging core‑shell, MBS‑hybrid and bio‑derived AIM chemistries, mapped to application performance and cost implications.
- Competitive clan maps and M&A heatmaps: A stratified view of third‑party concentration, partnership levers, and target archetypes for bolt‑on acquisitions or joint ventures.
- Regulatory sensitivity and mitigation playbook: Compliance checklists, timeline trackers for key jurisdictions, and product reformulation pathways.
- Executive decision pack: Board‑level slides and scenario summaries designed for capital allocation, procurement, and R&D committees.
Note — in keeping with the “preview” intent of this article, certain granular segmentation outputs (regional/application splits and confidential supplier volume shares) are intentionally excluded here; the full dataset and downloadable model are accessible in the PW Consulting report portal.
AIM (Acrylic Impact Modifier) Market
Market structure and competitive dynamics — what leaders must know
The AIM market shows a moderate level of concentration: the three largest players account for a majority share of production capacity, and the top five approach closely to roughly seven in ten of market capacity. This structure creates both advantages and constraints: established players enjoy scale economics and channel reach, while mid‑sized regional producers retain agility to serve specialized formulations and local compliance needs.
AIM (Acrylic Impact Modifier) Market
- Global majors and technology champions — Firms with global R&D platforms and extensive product portfolios (examples in the study include established European, Japanese, and North American chemical companies) continue to protect margin through innovation (e.g., weatherable, UV‑resistant grades and engineering‑plastic modifiers) and by leveraging brand and compliance credentials in regulated markets.
- Regional specialists — Several Chinese and other regional manufacturers have expanded core‑shell acrylic capacity and developed localized cost advantages. These producers play a critical role in price‑sensitive PVC markets and act as acquisition targets for global firms seeking scale in faster‑growing end‑markets.
- Emerging consolidation logic — The interplay of capacity expansions, product upgrades, and regulatory pressures is generating a predictable consolidation corridor. Buyers should expect selective M&A and partnership activity over 2026–2028 as firms seek to plug portfolio gaps or accelerate access to sustainable chemistries.
Company patterns and strategic implications (select examples)
- Producers with differentiated AIM grades emphasizing fusion, UV durability, and low‑temperature performance have superior commercial traction in premium PVC applications. For incumbents, defending margin requires a roadmap to incremental product improvements and application‑specific testing support.
- Regional players that combine competitive cost structures with fast response to local compliance shifts are attractive partners for licensing or distribution alliances — particularly for firms seeking rapid entry into high‑growth pockets without committing to full capacity builds.
- Recent corporate moves (product launches, capacity expansions, updated compliance certifications) indicate that the fastest responders are those aligning R&D spend with regulatory change and end‑use OEM requirements rather than chasing short‑term price competition alone.
Recent industry signals to watch in 2026
- Product launches and line upgrades highlight a continued emphasis on higher‑value grades suitable for engineering plastics and exposed profile applications.
- Certification updates for compliance frameworks underscore that regulatory alignment is increasingly non‑negotiable to access certain customer segments and geographies.
- Capacity expansions in key producing countries reflect both demand confidence and the strategic desire to secure regional supply; these moves will moderate price volatility if matched by end‑market growth as forecasted, but will exacerbate margin pressure if demand softens.
Raw materials, regulation and macro risk — practical reading
Feedstock trends materially influence AIM economics. In 2025, methyl methacrylate exhibited a soft‑to‑stable cost environment in Asia driven by weaker downstream demand and balanced supply; butadiene priced lower through much of the year with regionally varied assessments. These raw material dynamics reduce near‑term input pressure but increase the value of flexible procurement strategies and strategic hedging. On the regulatory front, ongoing EU discussions regarding restrictions on phthalates and certain heavy‑metal stabilizers signal potential substitution demand — a strategic tailwind for AIM grades compatible with new PVC stabilizer regimes. Simultaneously, public and policy incentives for bio‑based and recyclable additives are creating clear product development imperatives for manufacturers and compounders alike.
Actionable recommendations for 2026
- Prioritize feedstock diversification and contractual flexibility: establish tiered supply agreements and short‑term hedging to protect margins against abrupt volatility in MMA and butadiene.
- Invest in differentiated chemistries that align with regulatory trajectories: focus R&D on weatherability, low‑temperature performance, and bio‑content while preparing reformulation pathways for potential phthalate restrictions.
- Adopt a targeted M&A and alliance playbook: screen acquisition targets by technological fit and regional channel strength rather than headline revenues alone; consider minority equity ties to fast‑moving regional producers as an acceleration mechanism.
- Deploy commercial pilots with OEMs in priority end‑uses: demonstrate lifecycle benefits and regulatory compliance to secure specification wins that translate into long‑term offtake agreements.
- Build scenario‑based capital plans: use the report’s demand model to stress‑test capacity decisions under divergent regulatory and raw‑material permutations.
- Elevate sustainability reporting and certification readiness: proactive compliance (e.g., REACH‑aligned documentation) shortens time‑to‑market in regulated geographies and preserves premium pricing potential.
Closing — how to use our AIM intelligence in 2026
The PW Consulting AIM Market study is designed to convert polymer chemistry and market data into board‑ready decisions for 2026. The headline trajectory — a consistent multi‑year expansion at a mid‑single‑digit CAGR — validates the strategic interest in AIM capacity, product upgrades, and targeted M&A. Yet, success will hinge on how companies navigate feedstock swings, regulatory shifts, and the evolving competitive map. This article intentionally presents the strategic narrative and operational playbooks while withholding proprietary segment detail; firms requiring the full quantitative model, regional and application‑level breakdowns, supplier scorecards, and the downloadable scenario workbook should consult the full report available on the PW Consulting AIM Market page.
For detailed analysis of this topic, please visit the official page: AIM (Acrylic Impact Modifier) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Safety Gloves Market Poised for 7.41% CAGR Through 2032
By pmarketresearch, 2026-07-23
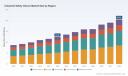
Industrial Safety Gloves Market: Strategic Imperatives for 2026
As industrial risk profiles and regulatory expectations converge in 2026, safety gloves move from being a procurement line-item to a strategic lever for frontline resilience, cost control, and brand protection. PW Consulting’s latest Industrial Safety Gloves Market research — anchored on a 2025 base year with historical coverage 2020–2025 and a forecast through 2032 — maps this transition. The market has expanded from roughly USD 8.7 Million in 2020 to approximately USD 12.44 Million in 2025, and is projected to reach about USD 13.53 Million in 2026, following a compound annual growth rate of 7.41% across the forecast period and reaching roughly USD 20.52 Million by 2032. For executives making allocation, sourcing and M&A decisions in 2026, this research translates these headline numbers into decision-ready intelligence.
Industrial Safety Gloves Market
Why this report matters for 2026 decisions
- Risk-aware procurement: With standards and enforcement tightening, glove selection now directly affects compliance, worker safety metrics, and liability exposure.
- Cost and margin management: Raw-material volatility is driving asymmetric cost shocks; manufacturers and distributors must adapt pricing and sourcing strategies rapidly.
- Product and channel prioritization: The market’s growth trajectory rewards firms that pair technical differentiation (cut resistance, chemical protection, accelerator-free formulations) with optimized go-to-market routes.
- M&A and supply-chain realignment: Moderate market concentration and pockets of regional specialization present acquisition targets and partnership opportunities for scale and capability access.
Macro forces shaping the market in 2026
Three systemic forces will determine winners and laggards in the near term: regulation, raw-material dynamics, and application-level demand. The ANSI/ISEA 105-2024 update — introducing a new pentagon-shaped pictogram to communicate abrasion, cut and puncture ratings — and its de-facto link to OSHA guidance have elevated label clarity and certification as commercial differentiators. Parallel to regulatory tightening, raw-material inputs (latex, nitrile, NBR and polymer compounds) have experienced acute price swings; in particular recent geopolitically driven NBR price shocks have materially increased production costs for exposed manufacturers. Finally, demand across industrial verticals continues to diversify: end users now evaluate gloves on a matrix of risk profile, ergonomics, environmental footprint and lifecycle cost, not just unit price.
Industrial Safety Gloves Market
Competitive landscape — what incumbents and challengers are doing
The market exhibits moderate concentration (CR3 ≈ 54.2%, CR5 ≈ 61.8%), indicating meaningful scale benefits for leading brands and room for mid-market specialists. Our qualitative review of core players highlights distinct strategic postures:
Industrial Safety Gloves Market
- Superior Glove (Ontario) emphasizes engineered protection and long-standing certification credentials — a clear fit for industrial and institutional buyers prioritizing specification-level compliance.
- Ansell (U.S.) leverages breadth across chemical-resistant and industrial ranges (e.g., AlphaTec) to serve OEMs and large contractors where product breadth and global supply stability matter.
- Magid Glove & Safety and regional specialists such as Showa focus on cut-resistant and general-purpose portfolios, competing on targeted performance and channel intimacy.
- Midas Safety’s SKU breadth and recent launches (e.g., mid-2025 CutXprt series) demonstrate how product innovation at the SKU level can unlock share in specific risk segments.
- Emerging manufacturers and regional producers (including suppliers from China, India and Southeast Asia) compete on cost and speed to market, with some differentiating via novel formulations such as accelerator-free nitrile offerings.
For buyers and investors, the implication is straightforward: national and multinational customers increasingly bifurcate purchases between certified, premium suppliers for high-risk tasks and competitive, cost-efficient suppliers for commodity use. Distribution strength, certification pedigree and supply-chain transparency are decisive selection criteria in 2026.
Product and technology trends to watch
- Certification-driven differentiation: Conformance to ANSI/ISEA 105-2024 and equivalent regional standards is now table-stakes for industrial spec buyers; pictogram-based labeling improves procurement accuracy and reduces mismatch risk on-site.
- Material innovation: Accelerator-free nitriles, synthetic substitutes (e.g., emerging Syntex synthetics), and hybrid constructions are gaining traction as manufacturers balance performance, allergy mitigation and cost.
- Ergonomics and human factors: Lightweight, dexterity-focused coatings and fit technologies are becoming key competitive attributes for assembly and precision tasks.
- Sustainability and traceability: Recycled content, lower-emission production methods and transparent raw-material sourcing are increasingly part of RFPs for major industrial customers.
Supply-chain and raw-material risk management
Raw-material exposure is the dominant operational risk for manufacturers. Recent industry data show acute impacts in Asia-Pacific manufacturing hubs and episodic price surges tied to geopolitical events. A practical risk playbook in 2026 includes:
- Dynamic hedging and layered contracts — combining short and long-term purchase agreements to smooth input-cost volatility.
- Diversified sourcing — qualifying alternate polymer suppliers across geographies to reduce single-source vulnerability.
- Material substitution roadmaps — investing in validated alternative formulations (e.g., synthetic nitrile variants) that preserve performance while reducing supply concentration risk.
- Vertical integration or strategic joint ventures — selectively capturing upstream capacity to stabilize margins where volumes justify capex.
Commercial playbook for 2026 — practical moves for executives
Translate market growth and risk dynamics into executable initiatives that protect margins and accelerate share gains:
- Segment the customer base by risk-sensitivity and willingness-to-pay; concentrate premium sales motions on high-risk accounts while optimizing low-touch channels for commodity volumes.
- Introduce value-added services (fit training, on-site glove audits, digital compliance trackers) to increase wallet share and reduce churn.
- Embed certification and labeling education into sales collateral to shorten procurement cycles for technically-sophisticated buyers.
- Revisit pricing architecture: implement cost-plus frameworks with transparent escalation clauses tied to benchmark raw-material indices.
- Prioritize product SKUs with the highest margin resilience and strategic value; consider SKU rationalization where inventory complexity erodes operational agility.
- Accelerate partnerships with distributors and PPE integrators to expand reach into hard-to-penetrate industrial segments.
- Pursue M&A selectively to acquire material science capabilities, regional manufacturing footprint, or digital compliance tools.
M&A, partnership and capex signals to monitor
Given the moderate market concentration and ongoing product innovation, 2026 is likely to see strategic deals that consolidate regional scale or add technological differentiation. Acquirers should prioritize targets with:
- Robust certification pipelines and documented compliance processes,
- Differentiated material IP or access to alternative polymers,
- Strong channel partnerships and sticky contractual relationships with industrial buyers, and
- Manufacturing footprints that hedge raw-material and logistics risk.
What PW Consulting’s full report delivers (practical, executable modules)
- Detailed market sizing and validated 2020–2032 forecasts with scenario modelling under alternate raw-material trajectories.
- Segmentation frameworks and decision matrices (by risk profile, product attribute, and buyer persona) to prioritize go-to-market investments.
- Comprehensive competitive profiles and strategic benchmarking of leading suppliers, including strengths, risks and capability gaps.
- Regulatory impact assessment mapping ANSI/ISEA 105-2024, OSHA referencing and regional certification requirements to procurement and labeling strategy.
- Supply-chain stress tests, cost pass-through models and hedging playbooks calibrated to real-world price shock scenarios.
- Actionable M&A screeners, due-diligence checklists and integration playbooks tailored to glove-sector targets.
- A commercial execution toolkit — pricing templates, distributor scorecards, SKU prioritization frameworks and pilot roadmaps for new product adoption.
Closing — decisions that matter in 2026
The Industrial Safety Gloves market is maturing: growth is strong, regulatory scrutiny is increasing, and input-cost volatility is reshaping supply economics. For 2026, the strategic imperative for executives is to convert market momentum into defensible margin and scope advantages — by aligning product portfolios to risk-based demand, shoring up material security, and moving beyond price-only competition toward certified, service-backed solutions. PW Consulting’s research is designed to accelerate those choices: it decodes the growth trajectory, diagnoses the structural risks and supplies the pragmatic tools needed to act decisively.
For access to the full dataset, granular segmentation analysis, and the executable playbooks referenced above, please visit PW Consulting’s Industrial Safety Gloves Market page or contact our strategy team for a 2026 briefing tailored to your organization.
For detailed analysis of this topic, please visit the official page: Industrial Safety Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
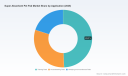
Super Absorbent Pet Pad Market: Strategic Outlook for 2026 — A PW Consulting Preview
Introduction
As PW Consulting’s senior strategy team, we prepared this executive preview to orient senior leaders, investors, and product-line owners to the strategic levers that will matter in 2026 for the Super Absorbent Pet Pad market. This narrative synthesizes our diagnostic work across market sizing, supplier economics, regulatory shifts, and competitive positioning. It intentionally surfaces the evidence-based judgments and decision frameworks that clients will need to act quickly — while preserving the proprietary, granular segmentation and scenario outputs that form the core of our paid analysis.
Super Absorbent Pet Pad Market
Market Snapshot: What the Macro Picture Shows
Using 2025 as the base year and a historical series beginning in 2020, PW Consulting’s topline model shows a steady expansion of the global Super Absorbent Pet Pad market through our forecast horizon to 2032. From a mid‑single‑hundred million USD industry base in 2020, the market rose materially by 2025 and is projected to continue expanding under our central scenario. Our forecast period spans 2026–2032 and embeds a compound annual growth rate (CAGR) of 3.6% from the base year through the forecast window.
Super Absorbent Pet Pad Market
To translate that into perspective: the market has matured beyond its early rapid‑growth phase and is now characterized by moderate, resilient growth driven by premiumization, channel shifts to e‑commerce, and product differentiation (odor control, leak protection, and sustainability claims). That growth profile creates a different strategic playbook than a high‑growth market: efficiency, margin protection, and selective innovation become the priority levers for 2026.
Super Absorbent Pet Pad Market
What the Full Report Delivers (Practical, Transaction-Grade Outputs)
- Dynamic market sizing and a reconciled forecast model (2020–2032) with downloadable scenario inputs so financial teams can re-run sensitivities under alternate SAP price and demand-shock assumptions.
- Actionable segmentation framework across product types, applications, and channels — with proprietary elasticities and unit‑price ladders for prioritizing SKUs.
- Supplier and input-cost benchmarking, including a componentized bill‑of‑materials that isolates the share and volatility of super absorbent polymer (SAP) in unit economics.
- Competitive heat maps and capability diagnostics for OEM/ODM players and private labels, including go‑to‑market scorecards and recommended partnership archetypes.
- Regulatory and standards playbook: implementation timelines and retailer compliance triggers tied to ASTM standardization efforts and voluntary certification pathways.
- Investment and M&A decision support: valuation multiples observed across recent transactions, integration risks, and potential synergies for horizontal consolidation or backward integration into SAP supply.
- Operational playbooks for production scale-up, QC, and logistics optimization under raw-material stress scenarios.
Key Market Dynamics and Strategic Implications for 2026
Below we summarize the dynamics that will materially influence near‑term decisions and the strategic options companies should prioritize in 2026.
- Input-cost concentration around SAP: Our industry engagement and cost modeling show that SAP is the single largest raw material contributor in pad manufacturing. That concentration means SAP price moves have outsized impacts on margins and retail pricing. Firms that can lock favorable long‑term supply, qualify alternative chemistries, or vertically integrate will gain a durable advantage in pricing flexibility.
- Sustainability as a double-edged sword: Degradable SAP alternatives are materially more expensive on a unit basis (industry participants reference 2–5x higher unit cost in developer conversations). While these materials open routes to premium positioning and retail shelf eligibility in sustainability programs, adoption will be constrained where price elasticity is acute. A staged product-release strategy and targeted premium channels work better than across‑the‑board reformulation in 2026.
- Standards and retailer pressure: The establishment of an ASTM subcommittee focused on pet products is accelerating voluntary standardization. Major retailers are already signaling they will favor suppliers who can demonstrate compliance. For 2026, compliance readiness will be a non‑negotiable for supply to tier‑one retail and institutional customers; proactive certification is a market access cost, not an optional marketing exercise.
- Channel bifurcation and private label dynamics: E‑commerce and private‑label programs continue to exert price pressure while creating volume opportunities. National retailers and platforms are increasingly optimizing assortments toward products that balance absorption performance with predictable cost structures. Brands that can differentiate on performance (odor control, quick‑dry, leak barriers) and simultaneously defend margins through private‑label manufacturing partnerships will capture both volume and margin.
- Quality and third‑party testing as a trust signal: Independent lab testing is becoming a buyer expectation — not just a marketing claim. Recent third‑party testing programs highlight performance variance across products; suppliers that invest in verified performance will unlock premium positioning and retailer shelf support.
Competitive Landscape — Who Matters and Why
The market exhibits moderate concentration at the top, with a small number of large suppliers commanding meaningful share while a broad set of specialized OEM/ODM firms serve differentiated product niches. That structure creates two viable strategic archetypes for 2026: scale‑driven cost leadership and specialist premiumation.
- ElinTree (China) — A specialist OEM/ODM with a focus on configurable absorbency ranges, odor control, and eco‑friendly material options. Certifications and quality systems position ElinTree as a reliable partner for branded manufacturers seeking customization and export compliance.
- Hangzhou Haoyue Personal Care — A legacy player with deep manufacturing experience. Its long production pedigree supports complex OEM contracts and consistent unit economics for larger private‑label programs.
- Tianjin Yiyi Hygiene Products — A high‑volume manufacturer with a strong export footprint, particularly in the U.S. market. Their scale and OEM capabilities make them an attractive partner for retailers and fast‑scaling private labels.
- Amazon Basics (United States) — A private‑label incumbent emphasizing performance at value price points. Represents the channel leverage private labels have over shelf assortment and the importance of manufacturing partnerships.
- Glad for Pets (United States) — A retail brand that pairs activated carbon odor control with mass retail reach; demonstrates the value of trusted consumer brands in driving purchase preference despite a crowded SKUscape.
Recent market events — a March 2026 new product launch by a named brand at Global Pet Expo and independent lab testing conducted in January 2026 — crystallize two practical points: (1) product innovation remains a necessary signal in the market, and (2) verified performance testing increasingly separates credible claims from marketing noise.
Market Concentration and Strategic Options
Our concentration analysis shows the market is neither a pure commodity nor a closed oligopoly. With the largest three firms accounting for a significant but not dominant share and the top five increasing that footprint further, scale matters for procurement and SAP exposure mitigation. Yet meaningful opportunity remains for nimble, quality-focused players to carve premium niches — particularly where they can pair validated performance with sustainability credentials and retailer endorsements.
2026 Playbook: Prioritized Actions for Executive Teams
- Hedge and secure SAP supply: Negotiate multi‑year contracts with volume bands and optionality clauses; evaluate co‑development or equity partnerships with SAP producers.
- Segment your innovation: Reserve high-cost degradable SAP formulations for targeted premium SKUs and sustainability pilots; defend core value SKUs with incremental performance improvements that do not materially raise cost.
- Certify early for ASTM-aligned standards: Invest in testing and documentation now to avoid downstream delisting from major retailers as voluntary standards crystallize into procurement requirements.
- Optimize channel mix: Use private‑label manufacturing as a margin and volume play while protecting your branded premium positions with demonstrable, third‑party validated features.
- Scenario-test price pass-through: Update pricing models to incorporate SAP cost swings and consumer elasticity thresholds, and model breakpoints at which premium features can be introduced without jeopardizing volume.
- Pursue targeted M&A or JV activity: Look for bolt‑on capabilities in odor control technologies, sustainable SAP developers, or last‑mile logistics to shorten time to market and strengthen margin capture.
How to Use PW Consulting’s Full Study
The complete PW Consulting report provides the proprietary models, SKU‑level demand curves, and supplier scorecards referenced above. It contains interactive spreadsheets for CFOs, an operations module for plant managers to run capacity stress tests under raw‑material shocks, and a retailer readiness checklist aligned to evolving ASTM guidance. If your 2026 planning cycle involves CAPEX allocation, product roadmap prioritization, or M&A screening in this category, the report was designed to be used as the central decision support artifact.
Conclusion — Why This Matters in 2026
For 2026, the Super Absorbent Pet Pad market offers stable growth, but strategic advantage will accrue to companies that treat SAP not just as an input but as a strategic asset. An integrated approach — combining supplier hedging, staged sustainability adoption, verified performance positioning, and proactive standards compliance — will separate winners from the pack. PW Consulting’s full report equips decision makers with the quantitative, operational, and regulatory tools to execute that approach; this preview highlights the direction and the core risks so your leadership team can prioritize the right near‑term actions.
To unlock the full dataset, scenario models, and supplier scorecards, refer to PW Consulting’s Super Absorbent Pet Pad Market study — the operational playbook you will want at your desk for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Super Absorbent Pet Pad Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thick Film Resistors Market Eyes USD 773.27M by 2032 at 4.86% CAGR
By pmarketresearch, 2026-07-23
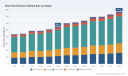
Thick Film Resistors Market 2026: Strategic Preview for Executive Decision-Making
Introduction — Why thick film resistors matter now
As power density, electrification and connectivity demands accelerate across automotive, industrial and telecom ecosystems, thick film resistors have moved from a mature commodity into a strategic component class. Our market model, anchored on a 2025 base year, shows the global market expanding at a compound annual growth rate (CAGR) of 4.86% through a 2026–2032 forecast horizon. The market climbed steadily from the early-2020s and is projected to continue that trajectory, providing a stable but evolving opportunity set for component manufacturers, subsystem suppliers and OEMs pursuing cost, performance and supply resiliency trade-offs.
Thick Film Resistors Market
Strategic relevance for 2026 decisions
For executive teams planning capital allocation, product roadmaps, sourcing strategies or M&A activity in 2026, the thick film resistor landscape presents several immediate decision points:
Thick Film Resistors Market
- Procurement & pricing: Raw material shocks and tradeduty headwinds have materially changed margin dynamics, making short-term hedges and medium-term supplier diversification essential.
- Product positioning: Advances that blur the performance gap between thick and thin film resistors demand decisive portfolio choices—either to defend commodity volumes or to climb to higher-margin, higher-spec product segments.
- Manufacturing footprint: Tariff escalation and regional policy shifts have raised the value of nearshoring and multi-region capacity. Timing investments in 2026 will determine competitiveness through the next technology cycle.
- Partnering & M&A: A market where three firms account for a significant share and the top five increase concentration further points to selective consolidation and strategic partnerships as pathways to scale and capability.
What this research delivers — actionable content (high level)
The full PW Consulting study is structured to be operationally useful to commercial, engineering and corporate development teams. Key deliverables include:
Thick Film Resistors Market
- Market sizing and validated demand trajectories from 2020 through 2032, including a detailed base-year benchmarking (2025) and the 4.86% CAGR assumption that underpins scenario work.
- Scenario-driven revenue and margin models that let teams stress-test procurement, pass-through pricing and capacity plans under alternative raw-material and tariff paths.
- Supply chain heatmaps and risk matrices identifying single-source exposure, critical raw-material nodes, and tariff-exposed shipping lanes to prioritize mitigation investments.
- Commercial playbooks: go-to-market and pricing tactics for defending commodity chip volume versus pursuing differentiated, automotive-grade and power-electronics segments.
- Technical comparators and qualification roadmaps to fast-track portfolio upgrades (for example, meeting automotive AEC-Q standards or power dissipation targets) without prolonging time-to-revenue.
- Interactive Excel workbooks and dashboards for scenario simulation, supplier scorecards and M&A screens to move from analysis to board-ready recommendations within weeks.
To preserve commercial value, this preview intentionally refrains from publishing core segmented figures in full — the detailed split by product, region and application is available in the complete report.
Competitive landscape — implications for 2026
The thick film resistor industry features a mix of diversified electronic component majors and specialist precision houses. Notable players profiled in our research include Bourns, Vishay, Panasonic, KOA, ROHM, TE Connectivity, Yageo and Caddock. Our competitive assessment focuses on capability vectors that matter in 2026: power handling, precision, automotive-grade qualification, scale and geographic footprint.
- Bourns, Inc.: Recent launches targeting high-heat power applications signal a deliberate push into motor drives and battery-system markets. For competitors and OEMs, this highlights an opportunity to develop higher-value thermal-management co-designs or to secure supply partnerships where compact power dissipation is a system differentiator.
- Vishay Intertechnology: Continued investment in automotive-precision thick film series reinforces the trend of thick-film solutions moving into safety- and reliability-critical vehicle systems. OEMs should expect heightened competition on qualification speed and price-performance trade-offs.
- Panasonic Holdings: With product introductions that bring thick film tolerances closer to thin-film levels, the technological bar is rising. This is a strategic signal for incumbents to either accelerate R&D or to reposition offerings around cost, lead times and integration services.
- KOA Corporation / KOA Speer: Known for surge-resistant and automotive-focused families, KOA’s positioning underlines the premium customer willingness to pay for ruggedization in electrified powertrains and industrial drives.
- ROHM and TE Connectivity: Both firms show breadth in power and shunt solutions for current sensing—critical where accuracy under thermal stress is non-negotiable. Collaborations with semiconductor and module suppliers will become a differentiator.
- Yageo Corporation: Capacity expansions aligned to 5G and industrial demand point to acceleration risk and opportunity—new volume wins can compress lead times and drive scale economies for those expanding early.
- Caddock Electronics: As a precision and high-reliability supplier, Caddock demonstrates the viability of a specialist route where stringent specs and long lifecycle programs command margins and stickiness.
Market concentration metrics in our model indicate meaningful scale advantages: the top three players account for a significant share while the top five increase industry concentration further. That dynamic is creating a bifurcating market — a scale-based channel for commodity volumes and a higher-margin specialist channel focused on differentiated capabilities.
Market dynamics shaping near-term action
Several market forces are accelerating the need for decisive 2026 action:
- Raw-material volatility: Precious-metal inputs such as ruthenium and silver experienced pronounced price swings that materially increased paste and component costs, squeezing margins and prompting rapid price adjustments across the value chain.
- Trade and tariff complexity: Escalating duties and policy measures have raised landed costs and extended qualification lead times for cross-border sourcing — a core reason to revisit geographic supply strategies this year.
- Rising compliance and labor expense: Precision manufacturing costs have increased due to both higher input prices and the need to meet automotive and industrial certifications, shifting the calculus on where and how to compete.
- Technology convergence: Product innovations are eroding historic performance boundaries between thick and thin film technologies, creating both substitution risk and product-upgrade opportunities.
For managers, these dynamics translate into practical choices: institute raw-material hedges and long-term supply contracts; re-evaluate sourcing footprints and supplier qualification timelines; prioritize product platforms that capture higher margin and stickier OEM relationships; and accelerate engineering investments where thick-film advantages align with system-level performance needs.
Scenario planning — tactical timelines for 2026
We recommend a three-horizon decision framework for 2026-facing programs:
- 0–12 months (stabilize): Lock in hedges and contingent supply agreements, update pricing clauses to reflect material pass-through, and run targeted cost-to-serve analyses for at-risk OEM customers.
- 12–36 months (adapt): Begin capacity reallocation or nearshoring pilots, accelerate qualification programs for automotive and power segments, and pursue selective co-development deals with module or motor OEMs.
- 36+ months (scale): Pursue M&A or greenfield investments to secure upstream paste capacity or to broaden product portfolios into adjacent sensing and power-resistor technologies.
Each horizon is modeled under our base-case CAGR assumption as well as upside and downside variants that stress raw-material and tariff scenarios. These scenario models are included in the full report and are calibrated to client-ready templates.
Concluding guidance — where to focus in 2026
For executives, the core strategic choice is whether to compete on scale, specialist performance, or integrated solutions. The market’s steady growth profile (anchored by the 4.86% CAGR) creates room for both plays, but the near-term volatility in inputs and trade policy compresses the window to act. Decisions made in 2026 — about hedging, qualification cadence, and footprint — will materially affect competitive positioning through the next growth cycle.
PW Consulting’s full Thick Film Resistors Market report provides the granular segmentation, pricing matrices, supplier scorecards and scenario simulations needed to convert this strategic viewpoint into executable plans. For teams preparing board-level recommendations, the full dataset and playbooks accelerate execution while preserving optionality under uncertainty.
Next step
Access the complete study to obtain the detailed segmentation, interactive models and supplier benchmarking that underpin the strategic recommendations summarized here. The full report contains the operational detail required to move from strategic intent to 90-day action plans and multi-year capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Thick Film Resistors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: RLG Market to Reach USD 10.9 Billion by 2032 with 9.2% CAGR
By pmarketresearch, 2026-07-23
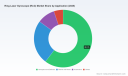
Ring Laser Gyroscope (RLG) Market 2026: Strategic Imperatives for Decision-Makers
As organizations finalize budgets and strategic roadmaps for 2026, understanding the trajectory of enclosure-grade inertial sensing is critical. Our PW Consulting Ring Laser Gyroscope (RLG) Market study — anchored on a 2025 base year with historical coverage from 2020–2025 and forward-looking projections to 2032 — synthesizes commercial, defense, and industrial demand signals into a single, executable guide. The global RLG market has expanded materially over the past half-decade (rising from roughly USD 3.15 Billion in 2020 to about USD 5.29 Billion in 2025) and, under our central scenario, is expected to continue growing at a compound annual growth rate (CAGR) of around 9.2% through 2032, reaching an estimated USD 10.9 Billion by the end of the forecast horizon. For executives weighing product bets, supplier relationships, and M&A options in 2026, the study provides the pragmatic, risk-aware intelligence required to convert opportunity into advantage.
Ring Laser Gyroscope (RLG) Market
Why this study matters in 2026
-
Strategic inflection across end-markets: RLGs remain foundational for high-reliability navigation across aerospace, defense, maritime, and emerging autonomy platforms. Recent product and technology rollouts—particularly solid-state RLGs tuned for unmanned and defense platforms—accelerate replacement cycles for legacy systems and create differentiated value propositions for integrators and OEMs.
Ring Laser Gyroscope (RLG) Market -
Technology convergence and supplier specialization: Advances in optical finishing and cavity engineering are raising the bar for performance while compressing the supplier base for truly high-spec components. Ultra-low micro-roughness optics and ultra-high finesse cavity components are not commodity items; they create durable technical walls that shape competitive dynamics.
Ring Laser Gyroscope (RLG) Market -
Regulatory and supply-chain friction: Export controls, defense certification regimes, and certified production standards are raising the cost of entry but also creating moats for compliant manufacturers. Likewise, suppliers that provide vertically integrated component packages — including precision frames and substrates — are shaping procurement strategies and time-to-deployment.
-
Moderate industry concentration opens strategic choices: The sector shows moderate concentration among leading suppliers, implying that scale and deep technical capability matter, yet there remains space for focused challengers and regional specialists to capture value.
What our report delivers — actionable, not academic
-
Proven market-sizing and scenario models: We reconcile bottom-up BOM builds with top-down demand drivers to deliver a robust 2020–2032 market model. The report includes three investment scenarios (conservative, central, upside) with sensitivity analyses tied to defense procurement cycles, aerospace OEM ramp rates, and unmanned platform adoption curves.
-
Go-to-market and procurement playbooks: Practical templates for supplier selection, RFx frameworks calibrated for high-reliability optical components, and an SLA & warranty model tailored to RLG lifecycles.
-
Vendor benchmarking and positioning maps: A qualitative and quantitative assessment of incumbent and emergent suppliers across capability axes—ranging from optical finishing, cavity finesse, and frame materials to systems integration and certification strength. (Note: detailed vendor share tables and proprietary scoring matrices are included in the full report.)
-
Supply-chain risk and mitigation toolkit: Sourcing heatmaps, critical-path components analysis (including specialized substrates and precision mirrors), dual-sourcing checklists, and scenario-driven contingency playbooks for key bottlenecks.
-
Investment and M&A roadmaps: Target screens for strategic buyers and private equity, valuation axioms for RLG assets, and an acquisition integration checklist that prioritizes IP retention and qualification pipelines.
-
Commercial models and TCO calculators: Ready-to-use financial models that generate expected payback under different unit-cost, volume, and warranty scenarios—enabling procurement and product teams to make informed trade-offs between in-house development and supplier partnerships.
Competitive landscape — profiles and strategic implications
-
G&H Products (California, United States): A hand-crafted manufacturer that supplies complete RLG component packages, including precision frames and optical assemblies. Their emphasis on certified production processes and defense-compliant registrations positions them as a preferred partner for programs requiring traceable, auditable supply chains and rapid qualification pathways. Strategic takeaway: partner or co-develop where program-level certification velocity matters; expect premium pricing for end-to-end responsibility.
-
Excelitas Technologies Corp. (Pittsburgh, Pennsylvania, United States): A specialist in ultra-high precision optics tailored for RLG cavities, delivering best-in-class surface finishes and minimized scattering losses. Suppliers with this level of optical performance materially improve IMU stability and system-level error budgets. Strategic takeaway: optical capability can be a decisive differentiator—buyers should bake optical performance thresholds into procurement specifications rather than treating optics as a commodity line item.
-
Micro Magic (United States): A systems integrator producing complete RLG-based inertial navigation systems (INS), with recent introductions of new solid-state RLG models targeting defense and unmanned platforms. Systems vendors that vertically integrate optical and control subsystems reduce integration risk for OEMs and prime contractors. Strategic takeaway: anticipate intensified competition among integrators as they push for platform-level wins; partnerships with systems vendors offer speed-to-market but require strict IP and qualification governance.
Across these supplier archetypes, the industry is neither fully fragmented nor monopolized. Leading suppliers capture meaningful scale and possess technical depth, but buyers retain leverage by enforcing standards, aggregating demand, and leveraging multi-year contracts tied to certification timelines.
Key implications for investors, OEMs, and procurement leaders in 2026
-
Prioritize supplier qualification early. Locking in suppliers that meet rigorous optical and systems certification criteria is a multi-quarter endeavor. Start qualification flows in Q1 2026 to align with program timelines and to capture favorable pricing on longer-term purchase commitments.
-
Evaluate integration versus component sourcing using a disciplined TCO lens. While vertically integrated systems reduce integration risk and shorten time-to-platform, component-level sourcing can preserve margin capture and enable platform differentiation if the OEM has the integration capability.
-
Incorporate export-control and certification risk into valuation models. ITAR and related regimes materially affect go-to-market strategies for defense and dual-use products. Compliance-capable suppliers offer optionality but at a cost that must be quantified in procurement decisions.
-
Use concentrated-supplier negotiating dynamics strategically. Moderate concentration means exclusivity or near-exclusive supply agreements are possible but require trade-offs in price, lead time guarantees, and capacity reservation clauses.
-
Invest in optical and systems-level R&D selectively. Small investments in optical metrology, control-loop improvements, and mechanical stabilization can deliver outsized system-level performance improvements—especially relevant where GNSS-denied navigation is a mission requirement.
Risks, mitigations, and near-term triggers to monitor
-
Supply-chain pinch points: Specialized substrates and precision mirrors are subject to capacity constraints. Mitigation: develop multi-tiered sourcing plans, secure long-lead inventory, and consider co-investment in supplier capacity where justified by volume.
-
Regulatory shifts and export controls: New or tightened controls can alter addressable markets. Mitigation: maintain audited compliance programs, pursue appropriate certifications, and evaluate localized manufacturing where market access and security requirements mandate.
-
Technology displacement: Emerging inertial technologies and hybridization can change value equations. Mitigation: adopt a staged investment approach that preserves optionality and conducts ongoing tech-scouting.
-
Contractual and qualification risk: Defense and aerospace qualification cycles can extend timelines and consume budget. Mitigation: embed qualification milestones in contracts and adopt phased acceptance with clear qualification criteria.
How to convert insight into action in 90 days
-
Run a supplier audit and a three-year sourcing plan: Use our supplier scorecard to shortlist partners and set qualification timelines tied to program gates.
-
Execute a pilot integration project: Select a single RLG SKU or module to validate integration assumptions and quantify system-level benefits before committing to fleet-wide changes.
-
Stress-test financial models: Apply our TCO calculators to your unit-cost assumptions and procurement scenarios to identify break-even points for vertical integration versus outsourcing.
-
Define an M&A scouting brief: If inorganic growth is in scope, use our target-screen filters—technology fit, certification status, and supplier relationships—to build a prioritized outreach list.
Conclusion: For firms making 2026 allocation decisions, the RLG market represents a structured growth opportunity balanced by technical and regulatory complexity. Our study equips executives with the decision-quality intelligence to commit capital, choose partners, and de-risk programs. The materials described above—including full segmentation tables, vendor market shares, and proprietary scoring matrices—are intentionally withheld from this preview to preserve their strategic value; the complete dataset, models, and supplier scorecards are available in the full PW Consulting report and dataset. Accessing the full report will enable you to convert the insights in this overview into prioritized, measurable actions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ring Laser Gyroscope (RLG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com