

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: RLG Market to Reach USD 10.9 Billion by 2032 with 9.2% CAGR

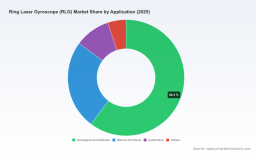
Ring Laser Gyroscope (RLG) Market 2026: Strategic Imperatives for Decision-Makers
As organizations finalize budgets and strategic roadmaps for 2026, understanding the trajectory of enclosure-grade inertial sensing is critical. Our PW Consulting Ring Laser Gyroscope (RLG) Market study — anchored on a 2025 base year with historical coverage from 2020–2025 and forward-looking projections to 2032 — synthesizes commercial, defense, and industrial demand signals into a single, executable guide. The global RLG market has expanded materially over the past half-decade (rising from roughly USD 3.15 Billion in 2020 to about USD 5.29 Billion in 2025) and, under our central scenario, is expected to continue growing at a compound annual growth rate (CAGR) of around 9.2% through 2032, reaching an estimated USD 10.9 Billion by the end of the forecast horizon. For executives weighing product bets, supplier relationships, and M&A options in 2026, the study provides the pragmatic, risk-aware intelligence required to convert opportunity into advantage.
Ring Laser Gyroscope (RLG) Market
Why this study matters in 2026
-
Strategic inflection across end-markets: RLGs remain foundational for high-reliability navigation across aerospace, defense, maritime, and emerging autonomy platforms. Recent product and technology rollouts—particularly solid-state RLGs tuned for unmanned and defense platforms—accelerate replacement cycles for legacy systems and create differentiated value propositions for integrators and OEMs.
Ring Laser Gyroscope (RLG) Market -
Technology convergence and supplier specialization: Advances in optical finishing and cavity engineering are raising the bar for performance while compressing the supplier base for truly high-spec components. Ultra-low micro-roughness optics and ultra-high finesse cavity components are not commodity items; they create durable technical walls that shape competitive dynamics.
Ring Laser Gyroscope (RLG) Market -
Regulatory and supply-chain friction: Export controls, defense certification regimes, and certified production standards are raising the cost of entry but also creating moats for compliant manufacturers. Likewise, suppliers that provide vertically integrated component packages — including precision frames and substrates — are shaping procurement strategies and time-to-deployment.
-
Moderate industry concentration opens strategic choices: The sector shows moderate concentration among leading suppliers, implying that scale and deep technical capability matter, yet there remains space for focused challengers and regional specialists to capture value.
What our report delivers — actionable, not academic
-
Proven market-sizing and scenario models: We reconcile bottom-up BOM builds with top-down demand drivers to deliver a robust 2020–2032 market model. The report includes three investment scenarios (conservative, central, upside) with sensitivity analyses tied to defense procurement cycles, aerospace OEM ramp rates, and unmanned platform adoption curves.
-
Go-to-market and procurement playbooks: Practical templates for supplier selection, RFx frameworks calibrated for high-reliability optical components, and an SLA & warranty model tailored to RLG lifecycles.
-
Vendor benchmarking and positioning maps: A qualitative and quantitative assessment of incumbent and emergent suppliers across capability axes—ranging from optical finishing, cavity finesse, and frame materials to systems integration and certification strength. (Note: detailed vendor share tables and proprietary scoring matrices are included in the full report.)
-
Supply-chain risk and mitigation toolkit: Sourcing heatmaps, critical-path components analysis (including specialized substrates and precision mirrors), dual-sourcing checklists, and scenario-driven contingency playbooks for key bottlenecks.
-
Investment and M&A roadmaps: Target screens for strategic buyers and private equity, valuation axioms for RLG assets, and an acquisition integration checklist that prioritizes IP retention and qualification pipelines.
-
Commercial models and TCO calculators: Ready-to-use financial models that generate expected payback under different unit-cost, volume, and warranty scenarios—enabling procurement and product teams to make informed trade-offs between in-house development and supplier partnerships.
Competitive landscape — profiles and strategic implications
-
G&H Products (California, United States): A hand-crafted manufacturer that supplies complete RLG component packages, including precision frames and optical assemblies. Their emphasis on certified production processes and defense-compliant registrations positions them as a preferred partner for programs requiring traceable, auditable supply chains and rapid qualification pathways. Strategic takeaway: partner or co-develop where program-level certification velocity matters; expect premium pricing for end-to-end responsibility.
-
Excelitas Technologies Corp. (Pittsburgh, Pennsylvania, United States): A specialist in ultra-high precision optics tailored for RLG cavities, delivering best-in-class surface finishes and minimized scattering losses. Suppliers with this level of optical performance materially improve IMU stability and system-level error budgets. Strategic takeaway: optical capability can be a decisive differentiator—buyers should bake optical performance thresholds into procurement specifications rather than treating optics as a commodity line item.
-
Micro Magic (United States): A systems integrator producing complete RLG-based inertial navigation systems (INS), with recent introductions of new solid-state RLG models targeting defense and unmanned platforms. Systems vendors that vertically integrate optical and control subsystems reduce integration risk for OEMs and prime contractors. Strategic takeaway: anticipate intensified competition among integrators as they push for platform-level wins; partnerships with systems vendors offer speed-to-market but require strict IP and qualification governance.
Across these supplier archetypes, the industry is neither fully fragmented nor monopolized. Leading suppliers capture meaningful scale and possess technical depth, but buyers retain leverage by enforcing standards, aggregating demand, and leveraging multi-year contracts tied to certification timelines.
Key implications for investors, OEMs, and procurement leaders in 2026
-
Prioritize supplier qualification early. Locking in suppliers that meet rigorous optical and systems certification criteria is a multi-quarter endeavor. Start qualification flows in Q1 2026 to align with program timelines and to capture favorable pricing on longer-term purchase commitments.
-
Evaluate integration versus component sourcing using a disciplined TCO lens. While vertically integrated systems reduce integration risk and shorten time-to-platform, component-level sourcing can preserve margin capture and enable platform differentiation if the OEM has the integration capability.
-
Incorporate export-control and certification risk into valuation models. ITAR and related regimes materially affect go-to-market strategies for defense and dual-use products. Compliance-capable suppliers offer optionality but at a cost that must be quantified in procurement decisions.
-
Use concentrated-supplier negotiating dynamics strategically. Moderate concentration means exclusivity or near-exclusive supply agreements are possible but require trade-offs in price, lead time guarantees, and capacity reservation clauses.
-
Invest in optical and systems-level R&D selectively. Small investments in optical metrology, control-loop improvements, and mechanical stabilization can deliver outsized system-level performance improvements—especially relevant where GNSS-denied navigation is a mission requirement.
Risks, mitigations, and near-term triggers to monitor
-
Supply-chain pinch points: Specialized substrates and precision mirrors are subject to capacity constraints. Mitigation: develop multi-tiered sourcing plans, secure long-lead inventory, and consider co-investment in supplier capacity where justified by volume.
-
Regulatory shifts and export controls: New or tightened controls can alter addressable markets. Mitigation: maintain audited compliance programs, pursue appropriate certifications, and evaluate localized manufacturing where market access and security requirements mandate.
-
Technology displacement: Emerging inertial technologies and hybridization can change value equations. Mitigation: adopt a staged investment approach that preserves optionality and conducts ongoing tech-scouting.
-
Contractual and qualification risk: Defense and aerospace qualification cycles can extend timelines and consume budget. Mitigation: embed qualification milestones in contracts and adopt phased acceptance with clear qualification criteria.
How to convert insight into action in 90 days
-
Run a supplier audit and a three-year sourcing plan: Use our supplier scorecard to shortlist partners and set qualification timelines tied to program gates.
-
Execute a pilot integration project: Select a single RLG SKU or module to validate integration assumptions and quantify system-level benefits before committing to fleet-wide changes.
-
Stress-test financial models: Apply our TCO calculators to your unit-cost assumptions and procurement scenarios to identify break-even points for vertical integration versus outsourcing.
-
Define an M&A scouting brief: If inorganic growth is in scope, use our target-screen filters—technology fit, certification status, and supplier relationships—to build a prioritized outreach list.
Conclusion: For firms making 2026 allocation decisions, the RLG market represents a structured growth opportunity balanced by technical and regulatory complexity. Our study equips executives with the decision-quality intelligence to commit capital, choose partners, and de-risk programs. The materials described above—including full segmentation tables, vendor market shares, and proprietary scoring matrices—are intentionally withheld from this preview to preserve their strategic value; the complete dataset, models, and supplier scorecards are available in the full PW Consulting report and dataset. Accessing the full report will enable you to convert the insights in this overview into prioritized, measurable actions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ring Laser Gyroscope (RLG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com