

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Acrylic Impact Modifier (AIM) Market to Reach USD 4.13B by 2032 at 5.7% CAGR

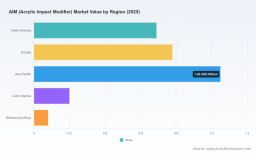
AIM (Acrylic Impact Modifier) Market — Strategic Snapshot for 2026 Decision Makers
Executive overview
As strategic advisors to senior leadership teams, we prepared the PW Consulting AIM Market study to convert technical polymer-market signals into executable choices for 2026. The Acrylic Impact Modifier (AIM) market has demonstrated steady expansion through the last half-decade and continues on a multi-year growth trajectory. Using a 2025 base year and a historical window of 2020–2025, our modelling projects the market through 2026–2032. The market is measured in Billion USD, expanded from the low‑single‑digit base in 2020 to a materially larger base by 2025, and our forecast trajectory implies a compound annual growth rate (CAGR) of 5.7% across the modelling horizon. These headline dynamics create a planning environment where investments in capacity, product development, and commercial differentiation can deliver measurable upside — provided organizations act with a clear view of risk exposures and competitive positioning.
AIM (Acrylic Impact Modifier) Market
Why this study matters for 2026 corporate strategy
- Investment timing: With a mid‑single‑digit CAGR and an observable inflection in demand patterns post‑2025, deployment timing for brownfield or greenfield capacity will materially affect unit economics. Our study maps where near‑term demand gaps and mid‑term surpluses are most likely to emerge under alternate scenarios.
- Supply‑chain resilience: Raw material volatility and logistical shifts are now first‑order issues. The report evaluates feedstock cost sensitivity and provides an actionable matrix for securing methyl methacrylate, butadiene, and other precursor streams under different supply scenarios.
- Product and go‑to‑market choices: The AIM space is bifurcating along performance and sustainability dimensions (e.g., low‑temperature performance vs. bio‑based credentials). The research distils which technical levers produce the highest margin expansion for PVC profile, pipe, and outdoor applications, and offers commercialization playbooks for each route.
- Regulatory and reputational risk management: Emerging regulatory debates in the EU on phthalate and heavy‑metal stabilizers — plus accelerating incentives for recyclable and bio‑based modifiers — change the risk/return calculus for incumbents and new entrants alike. We translate those regulatory signals into compliance roadmaps and capex prioritization recommendations.
What the report delivers — practical contents
- Quantitative demand model: An integrated bottom‑up demand model covering the historical period and a seven‑year forecast window, with scenario toggles for raw material price shocks, regulatory constraints, and substitution dynamics.
- Commercial playbooks: Tailored go‑to‑market frameworks for specialty producers, commodity AIM suppliers, and PVC compounders — including pricing tactics, channel prioritization, and OEM engagement strategies.
- Supply and cost benchmarking: A modular toolkit to assess feedstock exposure, unit cost curves, and break‑even capacity thresholds across alternative technologies and geographies.
- Technology and product roadmaps: Comparative profiles of emerging core‑shell, MBS‑hybrid and bio‑derived AIM chemistries, mapped to application performance and cost implications.
- Competitive clan maps and M&A heatmaps: A stratified view of third‑party concentration, partnership levers, and target archetypes for bolt‑on acquisitions or joint ventures.
- Regulatory sensitivity and mitigation playbook: Compliance checklists, timeline trackers for key jurisdictions, and product reformulation pathways.
- Executive decision pack: Board‑level slides and scenario summaries designed for capital allocation, procurement, and R&D committees.
Note — in keeping with the “preview” intent of this article, certain granular segmentation outputs (regional/application splits and confidential supplier volume shares) are intentionally excluded here; the full dataset and downloadable model are accessible in the PW Consulting report portal.
AIM (Acrylic Impact Modifier) Market
Market structure and competitive dynamics — what leaders must know
The AIM market shows a moderate level of concentration: the three largest players account for a majority share of production capacity, and the top five approach closely to roughly seven in ten of market capacity. This structure creates both advantages and constraints: established players enjoy scale economics and channel reach, while mid‑sized regional producers retain agility to serve specialized formulations and local compliance needs.
AIM (Acrylic Impact Modifier) Market
- Global majors and technology champions — Firms with global R&D platforms and extensive product portfolios (examples in the study include established European, Japanese, and North American chemical companies) continue to protect margin through innovation (e.g., weatherable, UV‑resistant grades and engineering‑plastic modifiers) and by leveraging brand and compliance credentials in regulated markets.
- Regional specialists — Several Chinese and other regional manufacturers have expanded core‑shell acrylic capacity and developed localized cost advantages. These producers play a critical role in price‑sensitive PVC markets and act as acquisition targets for global firms seeking scale in faster‑growing end‑markets.
- Emerging consolidation logic — The interplay of capacity expansions, product upgrades, and regulatory pressures is generating a predictable consolidation corridor. Buyers should expect selective M&A and partnership activity over 2026–2028 as firms seek to plug portfolio gaps or accelerate access to sustainable chemistries.
Company patterns and strategic implications (select examples)
- Producers with differentiated AIM grades emphasizing fusion, UV durability, and low‑temperature performance have superior commercial traction in premium PVC applications. For incumbents, defending margin requires a roadmap to incremental product improvements and application‑specific testing support.
- Regional players that combine competitive cost structures with fast response to local compliance shifts are attractive partners for licensing or distribution alliances — particularly for firms seeking rapid entry into high‑growth pockets without committing to full capacity builds.
- Recent corporate moves (product launches, capacity expansions, updated compliance certifications) indicate that the fastest responders are those aligning R&D spend with regulatory change and end‑use OEM requirements rather than chasing short‑term price competition alone.
Recent industry signals to watch in 2026
- Product launches and line upgrades highlight a continued emphasis on higher‑value grades suitable for engineering plastics and exposed profile applications.
- Certification updates for compliance frameworks underscore that regulatory alignment is increasingly non‑negotiable to access certain customer segments and geographies.
- Capacity expansions in key producing countries reflect both demand confidence and the strategic desire to secure regional supply; these moves will moderate price volatility if matched by end‑market growth as forecasted, but will exacerbate margin pressure if demand softens.
Raw materials, regulation and macro risk — practical reading
Feedstock trends materially influence AIM economics. In 2025, methyl methacrylate exhibited a soft‑to‑stable cost environment in Asia driven by weaker downstream demand and balanced supply; butadiene priced lower through much of the year with regionally varied assessments. These raw material dynamics reduce near‑term input pressure but increase the value of flexible procurement strategies and strategic hedging. On the regulatory front, ongoing EU discussions regarding restrictions on phthalates and certain heavy‑metal stabilizers signal potential substitution demand — a strategic tailwind for AIM grades compatible with new PVC stabilizer regimes. Simultaneously, public and policy incentives for bio‑based and recyclable additives are creating clear product development imperatives for manufacturers and compounders alike.
Actionable recommendations for 2026
- Prioritize feedstock diversification and contractual flexibility: establish tiered supply agreements and short‑term hedging to protect margins against abrupt volatility in MMA and butadiene.
- Invest in differentiated chemistries that align with regulatory trajectories: focus R&D on weatherability, low‑temperature performance, and bio‑content while preparing reformulation pathways for potential phthalate restrictions.
- Adopt a targeted M&A and alliance playbook: screen acquisition targets by technological fit and regional channel strength rather than headline revenues alone; consider minority equity ties to fast‑moving regional producers as an acceleration mechanism.
- Deploy commercial pilots with OEMs in priority end‑uses: demonstrate lifecycle benefits and regulatory compliance to secure specification wins that translate into long‑term offtake agreements.
- Build scenario‑based capital plans: use the report’s demand model to stress‑test capacity decisions under divergent regulatory and raw‑material permutations.
- Elevate sustainability reporting and certification readiness: proactive compliance (e.g., REACH‑aligned documentation) shortens time‑to‑market in regulated geographies and preserves premium pricing potential.
Closing — how to use our AIM intelligence in 2026
The PW Consulting AIM Market study is designed to convert polymer chemistry and market data into board‑ready decisions for 2026. The headline trajectory — a consistent multi‑year expansion at a mid‑single‑digit CAGR — validates the strategic interest in AIM capacity, product upgrades, and targeted M&A. Yet, success will hinge on how companies navigate feedstock swings, regulatory shifts, and the evolving competitive map. This article intentionally presents the strategic narrative and operational playbooks while withholding proprietary segment detail; firms requiring the full quantitative model, regional and application‑level breakdowns, supplier scorecards, and the downloadable scenario workbook should consult the full report available on the PW Consulting AIM Market page.
For detailed analysis of this topic, please visit the official page: AIM (Acrylic Impact Modifier) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com