

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wood Furniture Market to Reach USD 325B in 2025; 4.95% CAGR Ahead

Wood Furniture Market 2026: Strategic Imperatives from PW Consulting
As firms prepare capital allocation, supply-chain moves, and product roadmaps for 2026, the wood furniture sector is at a strategic inflection. Our latest Wood Furniture Market study — calibrated to a 2025 base year and projecting through 2032 — synthesizes historical performance (2020–2025), near-term shocks, and mid-term structural trends into an actionable decision-readiness framework. The global market, estimated at USD 325.0 Billion in 2025, is projected to advance at a compound annual growth rate (CAGR) of 4.95% across the forecast window, pushing overall value materially higher by 2032. For executive teams, the distilled question is simple: how do you convert this macro tailwind into durable, defensible profit pools while navigating regulatory and trade volatility?
Wood Furniture Market
What this research delivers — pragmatic intelligence, not theory
- Robust market sizing and a dynamic forecasting model (2026–2032) that integrates base-year validation, scenario overlays, and sensitivity to tariff and raw-material inputs.
- Regulatory and trade-impact modules that quantify near-term earnings and supply-chain stress under policy shocks (tariffs, duties, and traceability mandates).
- Supply-chain risk heatmaps, supplier concentration indices, and a practical supplier resilience playbook for rapid implementation.
- Competitive benchmarking and strategic options for incumbent manufacturers, pure-play artisans, and omni-channel retailers — including M&A playbooks and value-creep mitigation strategies.
- Commercial go-to-market templates for product premiumization, modularization for urban living, and digital direct-to-consumer acceleration.
- Implementation roadmaps, prioritized by ROI and execution risk, to convert insight into 90/180/365 day actions.
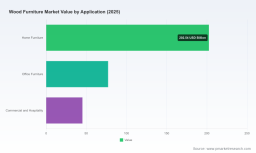
Note: this article demonstrates the depth of our analysis but intentionally omits the detailed regional and application-level tables and unit economics that are included in the full report. Those core segmentation matrices are available through the report landing page and client portal.
Wood Furniture Market
Where the market stands in early 2026 — concise takeaways
- Macro trajectory: The sector’s trajectory is healthy — an above-inflation growth profile in nominal terms driven by persistent consumer demand for higher-quality furnishings, elevated renovation cycles, and rebound in commercial fit-outs in select markets.
- Fragmentation and consolidation potential: Market concentration metrics point to a fragmented industry (CR3 ≈ 23.5%; CR5 ≈ 31.5%), which creates scope for strategic consolidation, roll-up strategies, and bolt-on supply assets that capture scale economics in procurement and distribution.
- Regulatory and trade inflection points: Policy moves enacted in late 2025 and early 2026 materially change cost and compliance dynamics — these are not transitory inconveniences but structural inputs that should reframe sourcing, pricing, and product design.
Policy and supply dynamics executives must internalize now
- Tariff and duty regime: A series of U.S. trade measures implemented in late 2025 imposes ad valorem tariffs on timber and on certain finished wood products, with escalations effective early 2026. Simultaneously, anti-dumping and countervailing actions have amplified landed costs for key inputs originating from traditional suppliers — a dynamic that has already elevated regional lumber prices and margins for some domestic producers.
- Traceability and provenance: From December 30, 2025, EU-level traceability requirements (EUDR) create mandatory due diligence for timber entering the European market — forcing global players to redesign multi-country supply chains and documentation practices.
- Raw-material reality: Domestic timber production remains sizable in traditional supplier markets; for example, U.S. softwood output provides a substantial primary raw-material base. Yet production does not insulate downstream makers from price and availability shocks when policy and global demand shift concurrently.
Competitive landscape: strategic archetypes and tactical responses
Our analysis profiles leading firms across three archetypes: mass-market integrators, office/contract specialists, and premium/handcrafted artisans. Each archetype faces distinct playbooks for 2026.
Wood Furniture Market
- Mass-market integrators (e.g., Ashley Furniture Industries) — Their advantages are scale, distribution reach, and merchandising. Near-term priorities: tariff pass-through strategies, inventory hedging, and SKU rationalization to protect margins while maintaining shelf velocity.
- Office and contract specialists (e.g., HNI Corporation, Haworth Inc.) — Exposure to commercial cyclicality and supply-chain lead times make hybrid manufacturing footprints and modular product design key to regaining time-to-contract and improving margin resilience.
- Premium/handcrafted artisans (e.g., Vermont Woods Studios, Furnirem, Whittier Wood, Stickley, Arista Wood) — These brands can capture premiumization upside by emphasizing provenance and sustainable sourcing. However, they must operationalize traceability and third-party verification to convert sustainability claims into commercial premiums, especially for markets bound by EUDR.
Recent tactical moves underscore playbook evolution: Furnirem’s March 2026 product-line expansion demonstrates how urban-living features (nesting, integrated storage) can unlock incremental ASPs and new household penetration. Arista Wood’s rebranding in February 2026 signals a strategic pivot toward reclaimed and fine hardwood narratives that align with sustainability-conscious consumers — a positioning that, if paired with rigorous traceability, can command category differentiation.
Risk vs. opportunity: concise matrix for 2026 planning
- Top downside risks: tariff-induced margin compression, compliance costs from traceability mandates, raw-material price spikes, and execution failure on nearshoring or supplier diversification plans.
- High-conviction opportunities: premium solid-wood and reclaimed-wood segments, integrated servicing (refinishing, buyback), modular designs for high-density housing, digital customization platforms, and targeted consolidation to capture procurement synergies.
- Short-term arbitrage: suppliers with domestic resource access or vertically integrated timber holdings can monetize price arbitrage; non-compliant supply chains face market access risk in regulated geographies.
Concrete actions for 90–365 day decision windows
- 90 days: Launch a supply-contract stress test. Quantify exposure to tariff schedules and antidumping outcomes; renegotiate clauses to include force majeure and pass-through triggers where feasible.
- 180 days: Execute a prioritized traceability pilot for at-risk SKUs destined for EUDR markets. Integrate chain-of-custody documentation into ERP and supplier scorecards.
- 365 days: Reconfigure footprint where warranted. Consider nearshoring low-value, high-weight SKUs, and locking in strategic timber supply via JV or long-term offtake to stabilize input costs.
- Ongoing: Institute a portfolio management cadence — retire low-turn, low-margin SKUs, accelerate premiumization initiatives, and deploy targeted M&A for distribution or procurement scale.
Why PW Consulting’s report is strategically different
- Action orientation: Every analytical output maps to a decision and an operational owner — whether procurement, product, commercial, or corporate development.
- Scenario-native forecasting: Beyond a point forecast (our base-year validated model indicates an immediate-year step-up into 2026), we deliver tariff and regulatory scenario modules that show P&L and working-capital sensitivity under alternative policy trajectories.
- Competitive playbooks: We combine primary interviews, trade-level channel economics, and public filings to generate executable options — from small cap bolt-ons to large-scale M&A — matched to the organization’s capabilities and appetite for change.
- Implementation-first deliverables: Templates, vendor-selection checklists, and a 12-month change-management timeline to move from strategic intent to measurable outcomes.
Final perspective: convert visibility into optionality
2026 will not be a year for passive planning in the wood furniture industry. Policy shifts, rising input volatility, and evolving consumer preferences will reward firms that combine a disciplined financial view with operational nimbleness and regulatory compliance. The market’s long-term growth path is intact — the challenge is capturing the right share of that growth while insulating earnings from tariff and compliance shocks. With market concentration still relatively low, the window for strategic consolidation and capability-driven differentiation remains open.
Our full Wood Furniture Market report contains the detailed segment tables, regional breakdowns, supplier heatmaps, and the functional toolkits executives need to act this year. Those granular datasets and playbooks are intentionally not reproduced here; they are embedded in the report’s interactive model and appendices. For access to the complete dataset, scenario files, and tailored implementation support from PW Consulting’s industry team, please visit the report landing page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Wood Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com