

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thick Film Resistors Market Eyes USD 773.27M by 2032 at 4.86% CAGR

Thick Film Resistors Market 2026: Strategic Preview for Executive Decision-Making
Introduction — Why thick film resistors matter now
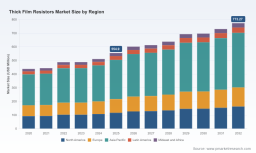
As power density, electrification and connectivity demands accelerate across automotive, industrial and telecom ecosystems, thick film resistors have moved from a mature commodity into a strategic component class. Our market model, anchored on a 2025 base year, shows the global market expanding at a compound annual growth rate (CAGR) of 4.86% through a 2026–2032 forecast horizon. The market climbed steadily from the early-2020s and is projected to continue that trajectory, providing a stable but evolving opportunity set for component manufacturers, subsystem suppliers and OEMs pursuing cost, performance and supply resiliency trade-offs.
Thick Film Resistors Market
Strategic relevance for 2026 decisions
For executive teams planning capital allocation, product roadmaps, sourcing strategies or M&A activity in 2026, the thick film resistor landscape presents several immediate decision points:
Thick Film Resistors Market
- Procurement & pricing: Raw material shocks and tradeduty headwinds have materially changed margin dynamics, making short-term hedges and medium-term supplier diversification essential.
- Product positioning: Advances that blur the performance gap between thick and thin film resistors demand decisive portfolio choices—either to defend commodity volumes or to climb to higher-margin, higher-spec product segments.
- Manufacturing footprint: Tariff escalation and regional policy shifts have raised the value of nearshoring and multi-region capacity. Timing investments in 2026 will determine competitiveness through the next technology cycle.
- Partnering & M&A: A market where three firms account for a significant share and the top five increase concentration further points to selective consolidation and strategic partnerships as pathways to scale and capability.
What this research delivers — actionable content (high level)
The full PW Consulting study is structured to be operationally useful to commercial, engineering and corporate development teams. Key deliverables include:
Thick Film Resistors Market
- Market sizing and validated demand trajectories from 2020 through 2032, including a detailed base-year benchmarking (2025) and the 4.86% CAGR assumption that underpins scenario work.
- Scenario-driven revenue and margin models that let teams stress-test procurement, pass-through pricing and capacity plans under alternative raw-material and tariff paths.
- Supply chain heatmaps and risk matrices identifying single-source exposure, critical raw-material nodes, and tariff-exposed shipping lanes to prioritize mitigation investments.
- Commercial playbooks: go-to-market and pricing tactics for defending commodity chip volume versus pursuing differentiated, automotive-grade and power-electronics segments.
- Technical comparators and qualification roadmaps to fast-track portfolio upgrades (for example, meeting automotive AEC-Q standards or power dissipation targets) without prolonging time-to-revenue.
- Interactive Excel workbooks and dashboards for scenario simulation, supplier scorecards and M&A screens to move from analysis to board-ready recommendations within weeks.
To preserve commercial value, this preview intentionally refrains from publishing core segmented figures in full — the detailed split by product, region and application is available in the complete report.
Competitive landscape — implications for 2026
The thick film resistor industry features a mix of diversified electronic component majors and specialist precision houses. Notable players profiled in our research include Bourns, Vishay, Panasonic, KOA, ROHM, TE Connectivity, Yageo and Caddock. Our competitive assessment focuses on capability vectors that matter in 2026: power handling, precision, automotive-grade qualification, scale and geographic footprint.
- Bourns, Inc.: Recent launches targeting high-heat power applications signal a deliberate push into motor drives and battery-system markets. For competitors and OEMs, this highlights an opportunity to develop higher-value thermal-management co-designs or to secure supply partnerships where compact power dissipation is a system differentiator.
- Vishay Intertechnology: Continued investment in automotive-precision thick film series reinforces the trend of thick-film solutions moving into safety- and reliability-critical vehicle systems. OEMs should expect heightened competition on qualification speed and price-performance trade-offs.
- Panasonic Holdings: With product introductions that bring thick film tolerances closer to thin-film levels, the technological bar is rising. This is a strategic signal for incumbents to either accelerate R&D or to reposition offerings around cost, lead times and integration services.
- KOA Corporation / KOA Speer: Known for surge-resistant and automotive-focused families, KOA’s positioning underlines the premium customer willingness to pay for ruggedization in electrified powertrains and industrial drives.
- ROHM and TE Connectivity: Both firms show breadth in power and shunt solutions for current sensing—critical where accuracy under thermal stress is non-negotiable. Collaborations with semiconductor and module suppliers will become a differentiator.
- Yageo Corporation: Capacity expansions aligned to 5G and industrial demand point to acceleration risk and opportunity—new volume wins can compress lead times and drive scale economies for those expanding early.
- Caddock Electronics: As a precision and high-reliability supplier, Caddock demonstrates the viability of a specialist route where stringent specs and long lifecycle programs command margins and stickiness.
Market concentration metrics in our model indicate meaningful scale advantages: the top three players account for a significant share while the top five increase industry concentration further. That dynamic is creating a bifurcating market — a scale-based channel for commodity volumes and a higher-margin specialist channel focused on differentiated capabilities.
Market dynamics shaping near-term action
Several market forces are accelerating the need for decisive 2026 action:
- Raw-material volatility: Precious-metal inputs such as ruthenium and silver experienced pronounced price swings that materially increased paste and component costs, squeezing margins and prompting rapid price adjustments across the value chain.
- Trade and tariff complexity: Escalating duties and policy measures have raised landed costs and extended qualification lead times for cross-border sourcing — a core reason to revisit geographic supply strategies this year.
- Rising compliance and labor expense: Precision manufacturing costs have increased due to both higher input prices and the need to meet automotive and industrial certifications, shifting the calculus on where and how to compete.
- Technology convergence: Product innovations are eroding historic performance boundaries between thick and thin film technologies, creating both substitution risk and product-upgrade opportunities.
For managers, these dynamics translate into practical choices: institute raw-material hedges and long-term supply contracts; re-evaluate sourcing footprints and supplier qualification timelines; prioritize product platforms that capture higher margin and stickier OEM relationships; and accelerate engineering investments where thick-film advantages align with system-level performance needs.
Scenario planning — tactical timelines for 2026
We recommend a three-horizon decision framework for 2026-facing programs:
- 0–12 months (stabilize): Lock in hedges and contingent supply agreements, update pricing clauses to reflect material pass-through, and run targeted cost-to-serve analyses for at-risk OEM customers.
- 12–36 months (adapt): Begin capacity reallocation or nearshoring pilots, accelerate qualification programs for automotive and power segments, and pursue selective co-development deals with module or motor OEMs.
- 36+ months (scale): Pursue M&A or greenfield investments to secure upstream paste capacity or to broaden product portfolios into adjacent sensing and power-resistor technologies.
Each horizon is modeled under our base-case CAGR assumption as well as upside and downside variants that stress raw-material and tariff scenarios. These scenario models are included in the full report and are calibrated to client-ready templates.
Concluding guidance — where to focus in 2026
For executives, the core strategic choice is whether to compete on scale, specialist performance, or integrated solutions. The market’s steady growth profile (anchored by the 4.86% CAGR) creates room for both plays, but the near-term volatility in inputs and trade policy compresses the window to act. Decisions made in 2026 — about hedging, qualification cadence, and footprint — will materially affect competitive positioning through the next growth cycle.
PW Consulting’s full Thick Film Resistors Market report provides the granular segmentation, pricing matrices, supplier scorecards and scenario simulations needed to convert this strategic viewpoint into executable plans. For teams preparing board-level recommendations, the full dataset and playbooks accelerate execution while preserving optionality under uncertainty.
Next step
Access the complete study to obtain the detailed segmentation, interactive models and supplier benchmarking that underpin the strategic recommendations summarized here. The full report contains the operational detail required to move from strategic intent to 90-day action plans and multi-year capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Thick Film Resistors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com