

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Super Absorbent Pet Pad Market Hits USD 668M in 2025

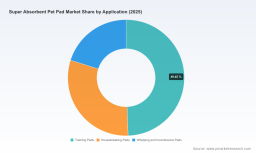
Super Absorbent Pet Pad Market: Strategic Outlook for 2026 — A PW Consulting Preview
Introduction
As PW Consulting’s senior strategy team, we prepared this executive preview to orient senior leaders, investors, and product-line owners to the strategic levers that will matter in 2026 for the Super Absorbent Pet Pad market. This narrative synthesizes our diagnostic work across market sizing, supplier economics, regulatory shifts, and competitive positioning. It intentionally surfaces the evidence-based judgments and decision frameworks that clients will need to act quickly — while preserving the proprietary, granular segmentation and scenario outputs that form the core of our paid analysis.
Super Absorbent Pet Pad Market
Market Snapshot: What the Macro Picture Shows
Using 2025 as the base year and a historical series beginning in 2020, PW Consulting’s topline model shows a steady expansion of the global Super Absorbent Pet Pad market through our forecast horizon to 2032. From a mid‑single‑hundred million USD industry base in 2020, the market rose materially by 2025 and is projected to continue expanding under our central scenario. Our forecast period spans 2026–2032 and embeds a compound annual growth rate (CAGR) of 3.6% from the base year through the forecast window.
Super Absorbent Pet Pad Market
To translate that into perspective: the market has matured beyond its early rapid‑growth phase and is now characterized by moderate, resilient growth driven by premiumization, channel shifts to e‑commerce, and product differentiation (odor control, leak protection, and sustainability claims). That growth profile creates a different strategic playbook than a high‑growth market: efficiency, margin protection, and selective innovation become the priority levers for 2026.
Super Absorbent Pet Pad Market
What the Full Report Delivers (Practical, Transaction-Grade Outputs)
- Dynamic market sizing and a reconciled forecast model (2020–2032) with downloadable scenario inputs so financial teams can re-run sensitivities under alternate SAP price and demand-shock assumptions.
- Actionable segmentation framework across product types, applications, and channels — with proprietary elasticities and unit‑price ladders for prioritizing SKUs.
- Supplier and input-cost benchmarking, including a componentized bill‑of‑materials that isolates the share and volatility of super absorbent polymer (SAP) in unit economics.
- Competitive heat maps and capability diagnostics for OEM/ODM players and private labels, including go‑to‑market scorecards and recommended partnership archetypes.
- Regulatory and standards playbook: implementation timelines and retailer compliance triggers tied to ASTM standardization efforts and voluntary certification pathways.
- Investment and M&A decision support: valuation multiples observed across recent transactions, integration risks, and potential synergies for horizontal consolidation or backward integration into SAP supply.
- Operational playbooks for production scale-up, QC, and logistics optimization under raw-material stress scenarios.
Key Market Dynamics and Strategic Implications for 2026
Below we summarize the dynamics that will materially influence near‑term decisions and the strategic options companies should prioritize in 2026.
- Input-cost concentration around SAP: Our industry engagement and cost modeling show that SAP is the single largest raw material contributor in pad manufacturing. That concentration means SAP price moves have outsized impacts on margins and retail pricing. Firms that can lock favorable long‑term supply, qualify alternative chemistries, or vertically integrate will gain a durable advantage in pricing flexibility.
- Sustainability as a double-edged sword: Degradable SAP alternatives are materially more expensive on a unit basis (industry participants reference 2–5x higher unit cost in developer conversations). While these materials open routes to premium positioning and retail shelf eligibility in sustainability programs, adoption will be constrained where price elasticity is acute. A staged product-release strategy and targeted premium channels work better than across‑the‑board reformulation in 2026.
- Standards and retailer pressure: The establishment of an ASTM subcommittee focused on pet products is accelerating voluntary standardization. Major retailers are already signaling they will favor suppliers who can demonstrate compliance. For 2026, compliance readiness will be a non‑negotiable for supply to tier‑one retail and institutional customers; proactive certification is a market access cost, not an optional marketing exercise.
- Channel bifurcation and private label dynamics: E‑commerce and private‑label programs continue to exert price pressure while creating volume opportunities. National retailers and platforms are increasingly optimizing assortments toward products that balance absorption performance with predictable cost structures. Brands that can differentiate on performance (odor control, quick‑dry, leak barriers) and simultaneously defend margins through private‑label manufacturing partnerships will capture both volume and margin.
- Quality and third‑party testing as a trust signal: Independent lab testing is becoming a buyer expectation — not just a marketing claim. Recent third‑party testing programs highlight performance variance across products; suppliers that invest in verified performance will unlock premium positioning and retailer shelf support.
Competitive Landscape — Who Matters and Why
The market exhibits moderate concentration at the top, with a small number of large suppliers commanding meaningful share while a broad set of specialized OEM/ODM firms serve differentiated product niches. That structure creates two viable strategic archetypes for 2026: scale‑driven cost leadership and specialist premiumation.
- ElinTree (China) — A specialist OEM/ODM with a focus on configurable absorbency ranges, odor control, and eco‑friendly material options. Certifications and quality systems position ElinTree as a reliable partner for branded manufacturers seeking customization and export compliance.
- Hangzhou Haoyue Personal Care — A legacy player with deep manufacturing experience. Its long production pedigree supports complex OEM contracts and consistent unit economics for larger private‑label programs.
- Tianjin Yiyi Hygiene Products — A high‑volume manufacturer with a strong export footprint, particularly in the U.S. market. Their scale and OEM capabilities make them an attractive partner for retailers and fast‑scaling private labels.
- Amazon Basics (United States) — A private‑label incumbent emphasizing performance at value price points. Represents the channel leverage private labels have over shelf assortment and the importance of manufacturing partnerships.
- Glad for Pets (United States) — A retail brand that pairs activated carbon odor control with mass retail reach; demonstrates the value of trusted consumer brands in driving purchase preference despite a crowded SKUscape.
Recent market events — a March 2026 new product launch by a named brand at Global Pet Expo and independent lab testing conducted in January 2026 — crystallize two practical points: (1) product innovation remains a necessary signal in the market, and (2) verified performance testing increasingly separates credible claims from marketing noise.
Market Concentration and Strategic Options
Our concentration analysis shows the market is neither a pure commodity nor a closed oligopoly. With the largest three firms accounting for a significant but not dominant share and the top five increasing that footprint further, scale matters for procurement and SAP exposure mitigation. Yet meaningful opportunity remains for nimble, quality-focused players to carve premium niches — particularly where they can pair validated performance with sustainability credentials and retailer endorsements.
2026 Playbook: Prioritized Actions for Executive Teams
- Hedge and secure SAP supply: Negotiate multi‑year contracts with volume bands and optionality clauses; evaluate co‑development or equity partnerships with SAP producers.
- Segment your innovation: Reserve high-cost degradable SAP formulations for targeted premium SKUs and sustainability pilots; defend core value SKUs with incremental performance improvements that do not materially raise cost.
- Certify early for ASTM-aligned standards: Invest in testing and documentation now to avoid downstream delisting from major retailers as voluntary standards crystallize into procurement requirements.
- Optimize channel mix: Use private‑label manufacturing as a margin and volume play while protecting your branded premium positions with demonstrable, third‑party validated features.
- Scenario-test price pass-through: Update pricing models to incorporate SAP cost swings and consumer elasticity thresholds, and model breakpoints at which premium features can be introduced without jeopardizing volume.
- Pursue targeted M&A or JV activity: Look for bolt‑on capabilities in odor control technologies, sustainable SAP developers, or last‑mile logistics to shorten time to market and strengthen margin capture.
How to Use PW Consulting’s Full Study
The complete PW Consulting report provides the proprietary models, SKU‑level demand curves, and supplier scorecards referenced above. It contains interactive spreadsheets for CFOs, an operations module for plant managers to run capacity stress tests under raw‑material shocks, and a retailer readiness checklist aligned to evolving ASTM guidance. If your 2026 planning cycle involves CAPEX allocation, product roadmap prioritization, or M&A screening in this category, the report was designed to be used as the central decision support artifact.
Conclusion — Why This Matters in 2026
For 2026, the Super Absorbent Pet Pad market offers stable growth, but strategic advantage will accrue to companies that treat SAP not just as an input but as a strategic asset. An integrated approach — combining supplier hedging, staged sustainability adoption, verified performance positioning, and proactive standards compliance — will separate winners from the pack. PW Consulting’s full report equips decision makers with the quantitative, operational, and regulatory tools to execute that approach; this preview highlights the direction and the core risks so your leadership team can prioritize the right near‑term actions.
To unlock the full dataset, scenario models, and supplier scorecards, refer to PW Consulting’s Super Absorbent Pet Pad Market study — the operational playbook you will want at your desk for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Super Absorbent Pet Pad Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com