

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital Photo Frame Market to Hit USD 235.6M by 2032 at 3.2% CAGR

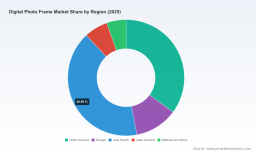
Digital Photo Frame Market — Strategic Preview for 2026 Decision-Making
As organizations and investors prepare strategy for 2026 and beyond, understanding the nuanced dynamics of the Digital Photo Frame (DPF) market has moved from a nice‑to‑have to a competitive imperative. Our PW Consulting market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes the commercial, technological and geopolitical forces shaping supplier economics, product roadmaps and commercialization models for the next growth cycle. This preview outlines the report’s strategic value, the macro trajectory, the competitive topology and the actionable themes leaders should prioritise—while deliberately reserving detailed subsegment figures to encourage direct access to the full analysis.
Digital Photo Frame Market
Why this study matters for 2026-level decisions
-
Portfolio prioritization: The DPF category is maturing—growth is steady rather than explosive—so executives must choose between incremental product innovation and adjacencies (services, subscription content, or enterprise deployments). Our research converts market shape and momentum into investment tradeoffs calibrated for 2026 budget cycles.
Digital Photo Frame Market -
Supply‑chain and sourcing strategy: Recent geopolitical and regulatory volatility has made sourcing decisions strategic. The report maps supplier concentration, margin sensitivity to logistics shocks, and feasible nearshore/onshore scenarios to help procurement and operations teams de‑risk rollouts and protect gross margins.
Digital Photo Frame Market -
M&A and partner screening: With a concentrated top tier of players and many viable regional OEMs, 2026 is a window for bolt‑on acquisitions and strategic alliances. Our due diligence frameworks reduce integration risk and highlight value-capture levers.
-
Commercial model decisions: The DPF market is evolving from one‑off hardware purchases to hybrid revenue models (hardware + cloud subscriptions + content licensing). The research quantifies the revenue implications of alternate go‑to‑market approaches so commercial leaders can model ARR and lifetime value tradeoffs.
Market snapshot (concise, data-driven)
On the macro level, the DPF market is in a low‑to‑mid growth phase. From a 2025 base (our reference year), the market is forecast to expand at a compound annual growth rate (CAGR) of approximately 3.2% across 2026–2032. That trajectory reflects a stable, consumer‑led category supplemented by steady commercial use cases—creating a forecasted expansion through the early 2030s that is predictable enough for disciplined capital allocation but modest enough to demand operational efficiency and differentiation.
Concentration is meaningful: the three largest vendors account for a dominant share of market value, and the top five even more so. That concentration shapes competitive dynamics, margins, channel leverage and price elasticity—factors we model in scenario detail in the full report.
Dynamics shaping the 2026 operating environment
-
Geopolitics and regulatory pressure: Ongoing trade tensions and cross‑border regulatory friction have pushed manufacturers to diversify assembly and reconsider component provenance. These forces accelerate product redesign cycles—especially around batteries and end‑of‑life handling—while compressing time‑to‑market for new display technologies.
-
Supply‑chain fragility and cost pass‑throughs: The sector remains sensitive to logistics disruption. Periods of heightened geopolitical risk have historically increased inventory carrying costs and insurance premiums materially, and these tail events are now embedded in many suppliers’ pricing models. Buyers and sellers must plan buffer capital and flexible logistics to avoid margin erosion.
-
Regulatory compliance and product development: Safety standards (battery, electronic waste) and consumer privacy regulation in key jurisdictions are pushing vendors toward safer batteries, more robust recyclability claims, and tighter data governance for cloud-enabled frames. These regulatory costs are non‑trivial and should be built into product cost‑of‑goods and roadmap timelines.
-
Labor and manufacturing footprint: Competitive OEMs in the region continue to underpin competitive pricing with local labour economics. Companies that can optimize labor mix across assembly, testing and packaging—combined with modular component sourcing—will retain an advantage in price‑sensitive channels.
Segmentation and opportunity pockets (strategic, not prescriptive)
The DPF market is widely segmented by product technology (LCD, LED, emerging OLED/e‑paper), and by end‑use across residential, commercial and institutional deployments. The full report contains a rigorous segmentation matrix and elasticity curves; here we outline the strategic implications without exposing granular split metrics:
-
Premium consumer vs. value hardware: There is durable demand for premium, connected frames that integrate app ecosystems and cloud sharing—driven by consumers who see these devices as lifestyle purchases. Conversely, a large value segment remains price sensitive and will pursue low‑cost, no‑frills offerings.
-
Enterprise and institutional adoption: Increasingly, DPFs are being repurposed for wayfinding, corporate communications and healthcare information delivery. These deployments favor ruggedization, remote provisioning and integration with third‑party content management systems—areas that incumbents and challengers can monetise through managed services.
-
Display innovation as a differentiator: Material shifts—OLED and e‑paper advances, anti‑glare coatings, and power management—are creating differentiation pathways. Firms that can balance cost, supply risk and unique user experiences will command higher ASPs and better retention on subscription layers.
Competitive landscape — focused profiles and tactical takeaways
The competitive topology includes a mix of digitally native premium brands, established consumer electronics labels and competent OEMs often operating behind private labels. Our study benchmarks product portfolios, channel strategies and R&D focus areas for the leading players.
-
Aura (U.S.) — Premium experience leadership: Aura has positioned itself around high‑end hardware, app‑centric user experience and aesthetic design. Its playbook reflects premium pricing, strong direct‑to‑consumer (DTC) presence and an emphasis on battery life and visual presentation features. For incumbents, Aura’s model shows how brand + ecosystem can insulate ASPs from commoditisation.
-
Nixplay (U.S.) — Cloud and voice integration: Nixplay combines cloud services with consumer hardware and has leaned into integrations (voice assistants, mixed media support). This shows the strategic value of platform thinking—where hardware drives recurrent cloud revenues and data‑driven upsell.
-
Aluratek (U.S.) — Feature breadth and calendar/utility focus: Recent launches (e.g., Smart WiFi Digital Calendar Photo Frames, April 2025) demonstrate a pragmatic approach of extending product utility—appealing to users who value hybrid functionality (photo + schedule + basic smart features).
-
Sungale (China) — Cost & scale: Sungale exemplifies OEM‑scale economics and aggressive cost‑to‑value positioning with a broad portfolio of cloud and plug‑n‑play frames. Suppliers operating from China continue to be central to global price dynamics and private‑label supply chains.
-
PhotoSpring, Kodak, Digital Foci — Niche plays and partnerships: Firms like PhotoSpring emphasize instant sharing and ease of setup; Kodak provides licensing muscle and brand recognition; Digital Foci focuses on both consumer and enterprise solutions. Each demonstrates alternative routes to market: UX differentiation, brand leverage, and B2B solutionisation respectively.
What the PW Consulting report delivers (practical components)
-
Market model with scenario sensitivity: We provide a base case and two alternate scenarios that stress test pricing, supply shocks and adoption shifts—suitable for financial planning and risk‑adjusted valuation.
-
Supplier scorecards and partner matrix: Comparative assessments of product portfolios, manufacturing risk, compliance readiness and partnership fit—ready to support procurement or M&A shortlisting.
-
Go‑to‑market playbooks: Channel strategies and launch plans for premium vs. value propositions, including marketing funnels, content strategies for cloud offerings and recommended sales incentives by channel.
-
Regulatory & sourcing checklist: Practical steps to match product roadmaps to emerging battery and e‑waste rules, plus a sourcing decision tree for nearshoring, split manufacturing and supplier dual‑sourcing.
-
IP and tech roadmap implications: Assessment of display technology adoption curves, component supply risks, and where to concentrate R&D to unlock ASP uplift or operational savings.
Strategic priorities for 2026 (recommended plays)
-
Choose a clear value capture model: Decide whether your organisation will pursue premium UX + subscription, low‑cost scale, or enterprise systems integration. Each requires different investments in product development, channel partnerships and customer support.
-
Invest in supply chain optionality now: Build at least one qualified alternative for critical components and plan phased nearshoring for high‑risk parts. Embedding supply‑chain flexibility into product cost models is a near‑term competitive advantage.
-
Monetize beyond hardware: Identify serviceable revenue streams (cloud storage, curated content, enterprise management) and pilot subscription bundles that can raise lifetime value without undermining initial sales conversion.
-
Prepare for regulatory lift: Integrate EOL (end‑of‑life) and battery compliance into product cost and warranty modelling to avoid late‑cycle remediation costs.
-
Pursue targeted M&A: Look for tuck‑ins that add cloud capability, regional distribution, or IP in energy management/display tech—acquisitions that accelerate margin expansion and reduce time‑to‑market.
Concluding note — the value of the full study
This preview outlines the strategic contours executives need to consider for 2026: a modestly growing global market with concentrated incumbency, meaningful supply chain and regulatory risk, and clear pathways to monetize product differentiation and services. PW Consulting’s full Digital Photo Frame Market report provides the quantitative backbone (detailed segmentation matrices, supplier rankings and scenario models) and the operational playbooks necessary to move from insight to execution. We purposefully refrain from publishing granular segment splits in this preview—those details, along with proprietary supplier assessments and deal frameworks, are available in the comprehensive study to support high‑confidence decisions.
For teams preparing strategic plans, procurement cycles and M&A pipelines in 2026, this research is designed as the actionable intelligence layer that reduces execution risk and accelerates value capture. Contact PW Consulting to access the complete report and the interactive market model.
For detailed analysis of this topic, please visit the official page: Digital Photo Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com