

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Facial Water Spray Market Set to Expand at a 6.98% CAGR Through 2032

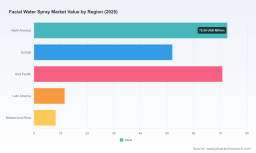
Facial Water Spray Market — Strategic Imperatives for 2026 Decision-Makers
As global beauty and personal care portfolios pivot toward lightweight, natural, and on-the-go hydration formats, facial water sprays have emerged from niche wellness counters to a mainstream, fast-growing category. PW Consulting’s latest market study (base year 2025; historical coverage 2020–2025; forecast horizon 2026–2032) quantifies this shift and translates it into actionable strategic options for executives planning 2026 investments and product roadmaps. At a compound annual growth rate (CAGR) of approximately 6.98% across the forecast window, the category demonstrates resilient expansion driven by product innovation, premiumization, and channel diversification.
Facial Water Spray Market
Why this study matters for 2026 strategy
-
Timing: 2026 is a pivotal planning year — consumers’ expectations around clean ingredients, micro-dosing packaging, and multifunctional formats have crystallized. Our study isolates the vectors of sustained demand versus transient hype so leadership teams can prioritize capital allocation with confidence.
Facial Water Spray Market -
Clarity on scale: The market’s base size in 2025 and its projected trajectory through 2032 provide a clear revenue envelope within which R&D, M&A, and route-to-market experiments should be evaluated. Scenario modeling in the report translates CAGR-driven growth into opportunity pools by strategic priority (e.g., premiumization, travel-size formats, ingredient-led skus).
Facial Water Spray Market -
Competitive context: With a moderate top-tier concentration and room for regional champions, the report equips mid-cap and incumbent players with differentiated escape routes — whether via brand extension, ingredient sourcing, or channel specialization.
Data-driven snapshot (high level)
Our analysis anchors on audited historicals (2020–2025) and a granular forecast (2026–2032). The category showed steady recovery and expansion post-2021 as consumers rebalanced skincare routines with convenience-led formats. Projected growth of roughly 7% CAGR across 2026–2032 reflects both volume expansion and meaningful premiumization: innovations in formulation (prebiotics, botanical actives, mineral fortification), packaging (recyclable and tamper-evident systems), and go-to-consumer models (travel retail, D2C subscriptions, and influencer-driven limited editions) are contributing to ASP increases alongside unit growth.
Importantly, market concentration metrics indicate a partially consolidated top tier (a meaningful share captured by leading heritage and dermatology-first brands), while the remaining share remains accessible to agile challengers and private labels. This structure favors strategic plays that combine brand credibility with channel agility.
What the PW Consulting report delivers (practical modules)
-
Market sizing and scenario modeling — base case, upside (premiumization-led), and downside (cost-pressure) scenarios for 2026–2032 with sensitivity to pricing, ingredient premiums, and packaging costs.
-
Demand drivers and consumer archetypes — segmentation by occasion, lifestyle, and ingredient preference; elasticity matrices for price and feature trade-offs targeted at urban Millennials and Gen Z.
-
Channel and route-to-market playbooks — decision frameworks for prioritizing travel retail, pharmacy/derm channels, e-commerce marketplaces, and branded D2C; converters and heuristics for channel margin and CAC comparisons.
-
Innovation and NPD pipeline mapping — ingredient roadmaps (thermal and mineral waters, botanical extracts, microbiome-friendly actives), formulation case studies, and IP/claim risk assessments.
-
Packaging and sustainability assessment — lifecycle cost models for recyclable vs. refillable formats, supplier scorecards, and trade-off analyses for tamper-resistance vs. consumer convenience.
-
Regulatory & compliance matrix — practical checklists for global market entry including mandatory labeling, pressurized container requirements, and U.S. import declarations to minimize customs and retail rejection risk.
-
Competitive benchmarking and M&A playbook — capability heatmaps across top players, valuation multipliers observed for recent transactions, and integration playbooks for thermal-spring sourced brands.
-
Retailer and partner negotiation templates — term sheets for co-branded launches, margin-sharing models for travel retail, and pilot KPIs for retail media investments.
Competitive landscape and strategic moves to watch
The competitive set mixes heritage thermal-spring specialists, prestige fashion houses, dermatology-first brands, and lifestyle incumbents. Leading companies continue to leverage provenance narratives, clinical credibility, and packaging innovation to defend and extend their positions.
-
Avène — continues to translate thermal spring credentials into skin microbiome-forward claims; recent launches (e.g., prebiotic-enriched mists) signal a strategy to occupy the sensitive-skin trust space while enabling premium price points.
-
La Roche-Posay — evolving packaging and mist technology demonstrates a dual play: product performance and sustainability. Enhanced dispersion tech and recyclable materials reduce usage friction and respond to retailer ESG screening.
-
Evian — partnering with regional skincare players to blend mineral water provenance with localized botanical extracts shows a modular co-branding approach that accelerates market entry while preserving core brand equity.
-
Clinique — experimentation with travel-size customizable scent kits highlights an omnichannel tactic: leveraging duty-free and online exclusives to boost trial and repeat purchase without diluting full-size positioning.
-
Prestige houses (e.g., DIOR, Vichy, Caudalie) — investing in organic claims, anti-aging narratives, and grapevine/mineral stories to justify premium AS RPs and to target specialty retail and high-margin e-commerce cohorts.
-
Regional premium and professional brands (e.g., Uriage, Origins, Shu Uemura) — maintain differentiation through source storytelling, botanical formulations, and salon/professional channel partnerships.
Collectively, recent industry actions (product launches with eco-packaging, prebiotic-enriched formulations, and co-branded regional partnerships) validate three enduring beats for 2026 strategic planning: (1) provenance + science narratives; (2) packaging that balances sustainability with regulatory tamper-resistance; (3) channel-first launches to capture trial and convert to higher-margin D2C relationships.
Regulatory and supply-side dynamics that will dictate execution
-
Labeling & import: Regulatory obligations such as mandatory English country-of-origin statements, ingredient declarations, and net quantity statements introduce operational frictions for cross-border launches. These are not mere checklist items — label iteration cycles impact time-to-shelf and cost of goods.
-
Container rules: Self-pressurized and liquid cosmetic containers are subject to specific declarations; brands must integrate tamper-resistant design early in the NPD process to avoid costly reworks and retailer non-compliance.
-
Raw material sourcing: Thermal and mineral spring waters remain the core input for many high-end sprays; botanical and functional inclusions (aloe, rose water, vitamin E, coconut derivatives) have premium price volatility and supplier concentration risks.
-
Pricing dynamics: Formulas containing natural or certified ingredients command price premiums. Our cost-to-margin models evaluate whether premiumization can offset higher procurement and sustainable packaging expenses across multiple launch scenarios.
Strategic options for 2026 — executable and measurable
-
Premiumization play: For brands with strong provenance, prioritize clinical claims, recyclable/smart packaging, and selective travel-retail exclusives. KPI: premium SKU ASP uplift and repeat purchase rate within 6–9 months.
-
Channel specialization: Deploy targeted D2C pilots to capture first-party data for personalization and subscription upsells; use marketplace and travel retail for reach. KPI: CAC payback <12 months for subscription cohorts.
-
Co-branding acceleration: Use modular co-development (local botanicals + core mineral water) to penetrate APAC and regional premium markets without full-fledge local ops. KPI: time-to-market and wholesale margin splits vs. in-house launches.
-
Cost leadership in mass segments: For players targeting mass channels, focus on reformulation for cost efficiency and tamper-resistant, lower-cost recyclable packaging; preserve a “clean” ingredient story. KPI: gross margin expansion while maintaining price parity.
-
M&A and licensing: Target thermal-source brands for portfolio depth or acquire formulation and packaging specialists to secure supply and accelerate sustainability goals. KPI: integration synergies within 12–18 months.
How PW Consulting’s deliverables accelerate decision-making
Our report is structured to move stakeholders from insight to action. Rather than a long list of numbers, it provides decision-makers with decision-ready tools: sensitivity models, prioritized investment heatmaps, retailer negotiation templates, regulatory checklists, and a 12–24 month NPD and commercialization roadmap tailored to common corporate constraints (cap-ex limits, supply chain lead times, regulatory filing cycles).
To preserve commercial value and to respect client confidentiality in high-stakes categories, the public summary intentionally omits granular regional and application-level splits. The full study contains the detailed segmentation, price-point ladders, and channel-level forecasts that product teams and M&A groups will require to finalize 2026 budgets and go-to-market schedules.
Next steps for leaders
-
Shortlist your strategic priority (premium growth, channel expansion, or cost optimization) for 2026 and request the tailored scenario pack from PW Consulting that maps the category’s revenue envelope to your chosen path.
-
Run a 90-day pilot: use our market-access checklist and sample retail terms to execute a controlled market test in one key channel; capture CAC, repeat rate, and supply resilience metrics to inform Q4 funding decisions.
-
Engage on M&A diligence: if inorganic expansion is on the table, our M&A playbook and valuation comparables will accelerate target screening and offer structuring.
PW Consulting’s Facial Water Spray Market study is designed to convert category momentum into durable business outcomes. For the granular segmentation data, channel-level forecasts, and the full suite of execution templates that will inform 2026 boardroom decisions, please consult the complete report on our website or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Facial Water Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com