

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Stereo Bluetooth Headsets Market Poised for 8.95% CAGR Through 2032

Stereo Bluetooth Headsets Market — Strategic Outlook & 2026 Decision Playbook
As organizations plan for a fast-evolving audio accessories landscape in 2026, actionable market intelligence that combines rigorous forecasting, competitive mapping, and operable playbooks becomes a strategic necessity. PW Consulting’s latest Stereo Bluetooth Headsets Market briefing (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) answers that need. The market we track reached approximately USD 1,980 Million in 2025 and is projected to grow at a compounded annual growth rate of 8.95% through the forecast window, roughly doubling in scale by the end of the period. This synthesis explains why that trajectory matters to executive decision-making in 2026 — and what practical moves should follow.
Stereo Bluetooth Headsets Market
Why 2026 Is a Pivotal Year
-
Product innovation is accelerating. Between 2023 and 2024 new product development in stereo Bluetooth headsets surged dramatically, with true wireless stereo (TWS) designs accounting for the majority of new launches. Advances such as Bluetooth 5.3+ integration, expanded active noise cancellation (ANC) features, touch-gesture controls, and embedded AI audio enhancements are shifting buyer expectations and raising baseline feature sets.
Stereo Bluetooth Headsets Market -
Supply-side fragility persists. Component shortages (notably lithium-ion cells, Bluetooth SoCs, and MEMS sensors) and logistics constraints have increased component costs and extended lead times—pressures that continue to shape sourcing, pricing, and inventory strategies.
Stereo Bluetooth Headsets Market -
Regulatory and geopolitical shifts are forcing reconfigurations of both product engineering and supply footprints. New European rules on common chargers and government manufacturing incentives in South Asia are examples of structural influences that will affect product design and where value chains are located.
Market Dynamics: What’s Driving Revenue and Margin Movements
-
Premiumization and feature-led differentiation: Consumers and enterprises increasingly pay for audio fidelity, ANC, spatial audio, and seamless multi-device integration. These features lift average selling prices and expand the premium segment.
-
TWS standardization: TWS architectures are now the dominant product architecture in new launches and premium SKUs, driving R&D focus and changing accessory and packaging ecosystems.
-
Cost inflation and lead-time risk: Industry data indicate component cost inflation in the low double digits and average shipping delays adding weeks to lead times, which compress gross margins unless offset by pricing power or cost mitigation programs.
-
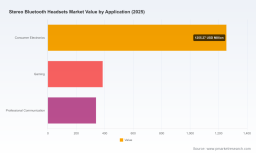
Channel and use-case diversification: Growth is coming from both classic consumer electronics and specialized pockets such as gaming and professional communications where reliability, latency, and microphone performance matter more than ever.
Competitive Landscape — Strategic Positions to Watch
-
Sony — Premium audio innovation: Sony’s product strategy centers on best-in-class ANC and immersive sound tuning. Their flagship stereo TWS products signal a continued focus on premium user experience and frequent firmware-driven feature upgrades to defend ASPs.
-
Apple — Ecosystem and user experience moat: Apple leverages deep integration across devices and services to maintain pricing power. Their audio roadmap emphasizes spatial audio and seamless device switching that sustain high-perceived value.
-
Bose — Brand-led ANC and consumer trust: Bose sits on brand equity in noise-cancellation performance and comfort, which helps preserve shelf space in premium retail and enterprise channels.
-
Samsung — Platform-driven differentiation: Samsung combines hardware innovation with mobile platform synergies and distribution reach across numerous markets to pursue share gains.
-
Jabra / Poly / Logitech — Enterprise and hybrid work plays: These vendors focus heavily on professional-grade headsets that emphasize microphone clarity, battery life, and unified communications certification — an important growth vector as hybrid work persists.
-
Sennheiser / JBL / Anker — From audiophile to value segments: These brands span the spectrum from high-fidelity niches to aggressive value propositions, using product breadth to capture multiple price bands.
Across the market, concentration remains modest: the top three and five firms do not dominate the space to the degree seen in some other consumer electronics categories. That fragmentation creates attractive windows for targeted consolidation, white-label partnerships, and niche differentiation plays.
What the Full Report Contains (Practical, Executable Assets)
PW Consulting’s full Stereo Bluetooth Headsets Market report delivers practitioner-focused tools designed for 2026 strategy cycles. Highlights include:
-
A calibrated market model (historical 2020–2025; base year 2025) and scenario-driven forecasts through 2032, enabling upside/downside planning for product, channel, and M&A initiatives.
-
Product innovation tracker mapping feature adoption curves (ANC, Bluetooth versions, AI audio, gesture controls), and time-to-market benchmarks for new launches.
-
Supply-chain heatmaps and supplier risk matrices that quantify exposure to critical components and logistics corridors, plus mitigations including supplier diversification and nearshoring.
-
Competitive scorecards and capability matrices for the leading vendors—assessing engineering depth, channel strength, service ecosystems, and IP positions.
-
Go-to-market playbooks tailored to distinct strategies: premium direct-to-consumer, enterprise UC partnerships, gaming-focused channel builds, and value-tier mass-market rollouts.
-
Pricing and margin sensitivity models that let commercial teams stress-test pricing responses to component cost inflation and promotional cadence.
-
M&A screening framework and integration checklist oriented to bolt-on audio brands, audio IP picks, and contract manufacturers that accelerate time-to-market.
To preserve the value of this briefing as a strategic “trailer,” the report intentionally withholds granular segment share tables and SKU-level revenue breakdowns from this summary; those detailed matrices are available in the downloadable dataset and appendices.
2026 Strategic Imperatives — How Leaders Should Act
-
Secure and rationalize supply chains now. Component price inflation and lead-time volatility are not one-off problems. Build multi-sourced procurement lanes for batteries, RF/SoC, and MEMS; invest in buffer inventory strategies; and prioritize suppliers with local assembly capabilities to mitigate logistics risk.
-
Design with regulatory foresight. European common-charging rules and ongoing reviews require product teams to align charging strategies, reduce accessory fragmentation, and plan SKUs that comply without sacrificing margin.
-
Differentiate through software and services. With hardware feature parity increasing, firms that layer firmware upgrades, personalized audio tuning, and subscription services will protect ASPs and create recurring revenue.
-
Segment route-to-market by use case. Gaming, professional communications, and premium consumer audio each require distinct product, channel, and support strategies. Avoid one-size-fits-all launches—focus instead on optimized SKUs and GTM plans per vertical.
-
Use manufacturing incentives to diversify footprint. Government programs in South Asia are attracting component suppliers and assembly investment; firms that move selected assembly closer to demand can reduce tariff and logistics exposure.
-
Prepare M&A and partnership playbooks. Moderate market concentration means strategic acquisitions can quickly deliver scale and capability (e.g., audio IP, UC certifications, or distribution networks).
Scenario Considerations You Must Model in 2026
-
Base scenario: Continued mid-to-high single-digit CAGR driven by premiumization and feature upgrades (consistent with our central 8.95% CAGR outlook for the stereo segment).
-
Supply-shock downside: Extended semiconductor or battery constraints that materially raise component costs beyond current estimates and compress sell-through during peak seasons.
-
Regulatory upside/downside: Faster imposition of cross-border interoperability standards (e.g., expanded ‘common charger’ categories) that raise short-term reengineering costs but reduce accessory fragmentation long-term.
-
Consolidation upside: Accelerated M&A and OEM consolidation that increases scale advantages for incumbents, raising barriers for small entrants focused on hardware-only differentiation.
Closing — What This Means for Your 2026 Plan
For executives building 2026 business plans, the core takeaway is straightforward: the stereo Bluetooth headset market is expanding at a pace that rewards early, disciplined investments in supply resilience, software-enabled differentiation, and use-case-specific route-to-market execution. PW Consulting’s report provides the quantitative forecasts, risk-adjusted scenarios, and go-to-market toolkits that leadership teams need to convert market growth into durable share gains and margin expansion.
To access the full dataset, company scorecards, and executable playbooks that underpin the forecasts summarized here, please download the full Stereo Bluetooth Headsets Market report. For bespoke strategy engagements — including M&A target screening, supply-chain redesign, or product roadmap optimization — PW Consulting’s industry practice stands ready to partner on rapid, high-impact implementations.
For detailed analysis of this topic, please visit the official page: Stereo Bluetooth Headsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com