

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Alumina Zirconia Oxide Abrasives Market to Reach USD 436.18M by 2032 at 5.2% CAGR

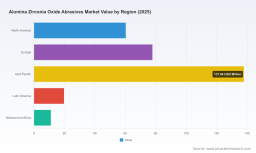
Alumina Zirconia Oxide Abrasives Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
As companies plan capital allocation, procurement strategies, and product roadmaps for 2026, clarity on the alumina zirconia oxide abrasives market is critical. PW Consulting’s new market research—anchored on a 2025 base year with a 2026–2032 forecast horizon—synthesizes historical dynamics (2020–2025) with forward-looking scenarios to help executives convert uncertainty into actionable choices. The global market has expanded steadily from the early 2020s and, under our central-case outlook, grows at a compound annual growth rate (CAGR) of 5.2% through the forecast window—moving from a mid-three‑hundred million USD base in 2025 toward a substantially larger market by 2032. This preview outlines the study’s strategic value for 2026 decisions while intentionally withholding granular segment tables to encourage full report access for transaction-level intelligence.
Alumina Zirconia Oxide Abrasives Market
Why this market matters in 2026
-
Material substitution is shifting demand composition. Alumina zirconia grades are gaining share across metalworking and bonded-abrasive applications where improved cut rates and life-cycle performance justify higher unit costs. That shift interacts with evolving manufacturing tolerances and surface-finish requirements—creating premiumization opportunities for suppliers able to demonstrate total cost-of-ownership advantages.
Alumina Zirconia Oxide Abrasives Market -
Supply-side structural constraints are re-shaping sourcing strategy. Global raw-material movements—illustrated by higher bauxite throughput and changing refinery footprints—are increasing exposure to upstream volatility. Our research highlights the linkages between bauxite and zirconia sourcing, substitution levers (e.g., silicon carbide), and their cost and performance trade-offs.
Alumina Zirconia Oxide Abrasives Market -
Market concentration amplifies competitive dynamics. The sector exhibits a high concentration among leading producers; our concentration metrics indicate that the top few firms command a dominant share of market supply. For buyers, that translates into negotiating asymmetries but also predictable innovation pipelines from incumbent R&D investments.
Key takeaways for 2026 decision-making
-
Procurement: shift from unit price to lifecycle cost metrics. Firms that revise procurement KPIs to prioritize grinding-life, downtime reduction, and disposal/recycling economics will unlock near-term margin expansion. Our modeling shows that modest premium on per-unit abrasion media can be offset by reduced cycle time and fewer wheel changes in many metalworking contexts.
-
Manufacturing & product development: prioritize performance demonstrators. OEMs and abrasive formulators should invest in in-field validation pilots that quantify per-batch productivity gains. Suppliers that couple materials science with application engineering (e.g., coated slurry optimizations, binder chemistry adjustments) will secure longer-term specification placements.
-
M&A and JV strategy: target capability and feedstock control. Given the market’s concentration and the criticality of raw-material access, acquisitions that secure upstream inputs, or that add differentiated grain technologies and customer applications expertise, will be accretive faster than greenfield capacity. Our diligence templates prioritize feedstock security, regulatory exposure, and process scalability.
-
Sustainability and regulation: incorporate material-circularity roadmaps. Leading players are already positioning recycled-content grades and lower-CO2 melt routes as procurement filters become common in large OEM supply chains. Regulatory signals—particularly in raw-material sourcing and energy-intensive production—will increasingly influence siting and contract terms.
Market trajectory and scenarios
Our baseline model—driven by historical volume and price dynamics from 2020–2025, and calibrated to macro-industrial demand scenarios—projects steady growth over 2026–2032 at a 5.2% CAGR. We present three scenario envelopes (conservative, base, and upside) that reflect permutations of raw-material shocks, capital expenditures by incumbents, and accelerated adoption of premium grains. Each scenario includes sensitivity analyses on price escalation, substitution rates, and productivity adoption curves to help firms stress-test strategic options.
Competitive landscape: what the preview reveals
-
Incumbent leadership and R&D intensity. Major global producers continue to invest in differentiated grain chemistries, premium grade rollouts, and sustainability claims. For example, a large European producer recently introduced a branded family of lower-carbon-content AZ grades as part of an explicit sustainability roadmap—an instructive case of product and positioning integration.
-
Regional production hubs and export dynamics. Asian manufacturing systems maintain cost and scale advantages for commodity-grade grains, while select European and North American players focus on premium bonded and finished abrasive systems. Trade show participation and targeted product launches in late 2025 underline an intensifying competition for specification placements across geographies.
-
Adjacency threat: engineered abrasives. Precision-shaped grains and engineered ceramic abrasives are competing across applications traditionally served by alumina zirconia. Some displacement is already visible in metalworking discs and specialty bonded tools, where longevity and predictable wear profiles outweigh raw-material cost differences.
Notable corporate activity (signal, not exhaustive)
-
Product innovation: A leading abrasives group launched a sustainability-focused premium AZ family in mid‑2025, emphasizing recycled inputs and lower embodied carbon for selected grades.
-
Market engagement: A major Chinese producer showcased its full alumina-zirconia portfolio at late‑2025 industry exhibitions, signalling an explicit push into precision grinding and finished-surface markets.
-
Competitive differentiation: Global industrial conglomerates continue to promote engineered grain technologies that target wear life and cut efficiency, challenging conventional alumina zirconia positioning.
Operational and supply-chain dynamics
Raw-material flows matter. In 2025, industry reporting pointed to elevated bauxite consumption and an increase in throughput compared to the prior year—factors that influence cost pass-throughs across the abrasive supply chain. Substitution levers (e.g., silicon carbide usage) exist but typically carry a premium; therefore, supply shocks to bauxite or zirconia streams can create both risks and arbitrage opportunities for integrated producers. In the United States, refinery capacity dynamics and higher import prices for crude dry bauxite and metallurgical grades underscore the need to model import-price scenarios and contingency sourcing strategies in procurement playbooks.
What the full report contains (high-level)
-
Market sizing and forecast model — Robust, auditable projections from 2020 through 2032 with scenario toggles for adoption rates, price paths, and substitution elasticity.
-
Supply-chain maps and cost stacks — End-to-end mapping from raw-material sourcing to finished bonded/coated products including energy and process levers.
-
Application and product segmentation — Demand drivers and growth vectors across product families (note: this preview omits the full segment-value tables to preserve subscription value).
-
Competitive benchmarking — Strategy matrices, technology roadmaps, and capability heatmaps for the leading suppliers and emergent challengers.
-
M&A and investment playbook — Deal screening criteria, valuation multipliers specific to abrasives, and integration risk checklists focused on feedstock and process scale.
-
Regulatory and sustainability matrix — Jurisdictional risk scoring, decarbonization levers, and compliance timelines that affect siting and capital planning.
-
Practical tools — Negotiation brief templates, pilot KPIs, and a supplier due-diligence checklist tailored to alumina-zirconia purchases.
How to use this intelligence in 90/180/360-day plans
-
First 90 days: Validate your exposure—map current bills of materials to abrasive types and suppliers; run immediate cost-of-ownership trials on high-volume SKUs.
-
Next 180 days: Execute supplier pilots that prioritize productivity metrics; begin conversations for longer-term supply agreements that lock in feedstock access and price bands.
-
360 days and beyond: Reassess your product portfolio and capital rhythm—consider bolt-on M&A or JV options to secure downstream specification control or upstream raw-material access.
Methodological note
The report is rooted in an auditable methodology: a blend of bottom‑up supply-side buildouts, top‑down demand calibration, customer channel interviews, and trade-data triangulation. Historical series cover 2020–2025 with a 2025 base year; forecasts run from 2026 through 2032. Sensitivity matrices for raw-material pricing, substitution rates, and policy shocks are included to stress-test strategic options.
Next steps — where this preview leads
This preview is intentionally selective: it demonstrates the strategic rigor and practical orientation of PW Consulting’s full study while omitting the granular segment and regional tables that many decision-makers need for transaction execution. If your 2026 strategic plan hinges on reliable segment-level demand curves, price-trajectory scenarios, supplier scorecards, or a downloadable financial model, the complete report and accompanying data pack provide those deliverables.
Contact PW Consulting to request the full market intelligence package, licensing options for the forecast model, and bespoke advisory workshops designed to convert these insights into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Alumina Zirconia Oxide Abrasives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com