

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Worldwide Oilseed Extraction Equipment Market to Expand at a 5.12% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Oilseed Extraction Equipment Market — Strategic Outlook for 2026 Decision-Makers
As food, feed, and industrial oils continue to underpin global commodity value chains, equipment that converts oilseeds into oil and meal remains a strategic asset for processors, OEMs, and investors. PW Consulting’s latest Worldwide Oilseed Extraction Equipment Market report (base year 2025, forecast period 2026–2032) delivers the granular intelligence teams need to align 2026 capital allocation, sourcing, and go-to-market choices with likely industry trajectories. At the macro level, the global equipment market reached approximately USD 5,250 million in 2025 and is projected to grow to about USD 7,447 million by 2032, reflecting a compound annual growth rate of 5.12% across the forecast window. This trajectory, and its non-linear year-to-year shape, creates both timing opportunities and execution risks for buyers and sellers alike.
Worldwide Brand Data Management Software Market
Why this report matters for 2026 decisions
-
Actionable planning horizon: The 2026–2032 forecast window is calibrated to the decision cycles most capital projects follow — from feasibility and engineering to commissioning and ramp-up — enabling CFOs and plant managers to synchronize procurement, financing, and construction schedules.
Ion Blower Market -
Investment-grade modelling: We combine technology-level performance assumptions, capex/opex templates, and scenario-driven demand pathways so teams can stress-test business cases against energy price swings, raw-material cost movements, and regulatory constraints.
Transparent Ultrasonic Couplant Market -
Vendor and capability benchmarking: Rather than theoretical supplier lists, the report provides operational criteria and decision matrices that differentiate competitors on throughput, energy intensity, automation readiness, and aftermarket reach — all central to 2026 supplier selection.
Report content — practical, operational, and implementable
-
Comprehensive market sizing and trend maps across 2020–2025 (historical) and 2026–2032 (forecast), built on blended demand-side and supply-side evidence streams.
-
Capital-expenditure playbooks: standardized cost models (plant-level CAPEX/OPEX), commissioning timelines, and productivity benchmarks that can be dropped into internal investment models.
-
Vendor scorecards and procurement templates: a repeatable RFP framework, technical checklists (mechanical press vs. solvent systems), and an evaluation matrix emphasizing energy, yield, and serviceability.
-
Raw-material sensitivity models: scenario analyses showing how variations in key inputs — including stainless steel pricing and energy costs — impact equipment total cost of ownership and payback intervals.
-
Regulatory and operational compliance guides: on-the-floor hygiene, temperature-control, and food-safety checklists tailored to modern oilseed processing lines.
-
Digital and energy-efficiency roadmaps: implementation sequencing for automation control systems, waste-heat recovery, and high-efficiency drive trains to drive yield and cost improvements.
-
M&A and alliance playbooks: target identification criteria and integration checklists for buyers seeking capability or footprint expansion.
Market dynamics shaping 2026 strategy
Several converging dynamics will dictate winning strategies in 2026. First, input-cost volatility — particularly for stainless steel and energy — is a near-term planning consideration. Our analysis incorporates prevailing stainless steel price benchmarks and their likely pass-through into equipment pricing, which can materially affect tender outcomes and margins on new builds.
Second, automation and digitalization have moved beyond efficiency experiments to become core differentiators. Control systems that optimize extraction throughput, reduce energy intensity, and stabilize yields now deliver quantifiable ROI in real projects; early adopters have reported improved uptime and consistent product quality that shortens payback periods.
Third, energy-saving technologies — smart temperature control, heat-recovery schemes, and high-efficiency transmissions — are no longer niche add-ons. They are central to compliance with tightening operational standards and to lowering life-cycle costs. The combination of regulatory pressure and carbon/energy cost exposure is prompting many processors to treat energy-efficiency investments as risk-mitigation measures rather than discretionary upgrades.
Finally, market concentration metrics matter. The industry shows a moderate degree of concentration among leading suppliers, which influences pricing power, aftermarket service availability, and the sourcing strategy of mid-tier processors. Our CR3 and CR5 concentration analysis provides a practical framework for evaluating bargaining dynamics and the feasibility of vendor consolidation strategies.
Competitive landscape — mapping capability to strategy
The report’s vendor analysis focuses on firms that define technological and commercial benchmarks in oilseed extraction equipment. Key themes from our competitive review include:
-
Heritage innovators: Firms with long engineering pedigrees remain important. Companies that invented or refined continuous mechanical pressing technologies retain advantages in proven reliability and a broad installed base — an asset when selling retrofit and aftermarket services.
-
Solvent-extraction specialists: Suppliers with deep solvent-extraction portfolios offer scale and process integration benefits for high-capacity facilities; their solution sets typically include advanced separation and reclamation systems that influence meal quality and environmental permitting.
-
Turnkey integrators: Vendors capable of delivering complete preparation-to-extraction lines and managing project delivery across geographies reduce interface risk for buyers but command premium pricing and require careful due diligence on delivery performance.
-
Regional value players: Cost-competitive manufacturers from high-volume, export-oriented markets continue to displace legacy suppliers in price-sensitive projects. Their playbooks emphasize modular designs, localized service partnerships, and rapid lead times.
Representative illustrative profiles in the report (not exhaustive) include companies with technological leadership in mechanical screw pressing and expeller designs, specialist solvent-extractionOEMs with comprehensive solvent handling lines, established turnkey plant builders with strong regional footprints, and suppliers that prioritize aftermarket service, spare parts, and digital monitoring packages. Recent industry activity — including major trade shows and multi-event participation by leading OEMs — is used as a near-term indicator of product launches and commercial priorities for 2026.
Practical recommendations for 2026 procurement and capital planning
-
Run a two-track CAPEX process: parallel-run “greenfield” vs. “brownfield retrofit” scenarios with distinct risk-adjusted returns. The report’s plant-level models let teams stress-test both approaches quickly.
-
Prioritize energy and automation features in RFPs. When lifecycle analysis shows a shorter payback for energy-saving options, financing structures should be adjusted to capture those long-term savings.
-
Hedge raw-material exposure: integrate stainless steel price sensitivity into procurement contracts and consider materials-substitution studies where food-grade requirements permit.
-
Use vendor scorecards beyond price: weigh service network density, spare-parts lead times, and digital remote-monitoring capabilities as decisive criteria. Aftermarket revenue and service continuity are where small equipment differentials translate to meaningful operational resilience.
-
Plan pilot projects for automation upgrades. A staged rollout approach reduces implementation risk and establishes performance baselines for broader rollouts across multi-plant portfolios.
How strategic leaders are using the report
We see four primary use cases from clients preparing 2026 budgets and strategic plans:
-
M&A diligence teams use the plant-level cost models to validate seller claims about throughput and energy intensity, and to size integration capex.
-
Procurement and engineering groups use the RFP templates and vendor matrices to shorten tender cycles and reduce specification ambiguity.
-
R&D and product strategy teams use sensitivity analyses (materials, energy, automation) to prioritize development roadmaps that respond to buyer economics.
-
Investor relations and corporate strategy functions use the market forecast and concentration analysis to construct plausible upside scenarios tied to market share shifts and aftermarket monetization.
What’s not in this release — and how to get it
To preserve the strategic value of this publication and follow the “trailer” principle, this article summarizes the report’s depth, tools, and high-level market trajectory but purposely omits the granular segment tables, regional and application-level percentage splits, and the full vendor scorecard matrices. These datasets and downloadable models are available on the report landing page and are provided as part of the licensed report package. Purchasing clients receive editable plant-level cost models, full RFP templates, and a bespoke 1:1 analyst briefing to translate benchmark findings into executable plans for 2026.
Next steps for decision-makers
If your 2026 capital and procurement calendar includes oilseed processing projects, the time to act is now. Use the report to shorten procurement cycles, de-risk delivery schedules, and secure the technology features that protect margins over the asset life. For tailored briefings or to arrange a demo of the report’s plant-level models and vendor scorecards, contact PW Consulting’s industry team. The full report contains the evidence base and operational tools that will convert high-level forecasts into secure, investable strategies for the coming planning year.
For detailed analysis of this topic, please visit the official page: Worldwide Oilseed Extraction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Antibody Fragments Market Set to Reach USD 22,798 Million by 2032, Driven by a 9.6% CAGR
By pmarketresearch, 2026-08-12
Worldwide Antibody Fragments Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting — Executive Brief
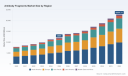
PW Consulting today releases the official executive summary of our Worldwide Antibody Fragments Market report, a practitioner-oriented intelligence product designed to inform and de-risk corporate strategy in 2026. The antibody fragments sector — spanning Fab, scFv and single-domain (VHH/nanobody) formats — is moving from niche innovation to scaled commercial relevance. Our market modeling shows the industry reaching a base-year market size of approximately USD 12,001 million in 2025 with a projected compound annual growth rate (CAGR) of 9.6% across the 2026–2032 forecast window, driving to a multi‑billion dollar market at the end of the period. This trajectory creates a distinct set of near-term tactical choices for drug developers, CDMOs, investors and payers.
Irrigation Supervisory Controller Market
Why this report matters for 2026 planning
- Actionable foresight: The report translates raw growth into decision-ready hypotheses — where to allocate R&D dollars, when to hedge manufacturing risk, and how to structure partnerships to preserve upside while limiting capital intensity.
- Risk-to-reward clarity: Antibody fragments offer differentiated product attributes (improved tissue penetration, alternative half‑life engineering) but with unique manufacturing and economics that materially affect margin and pricing strategies. Our models quantify those trade-offs and show how small shifts in COGS or reimbursement rates change project-level IRR.
- Competitive posture: We map incumbent and emerging players across platform, clinical pipeline and manufacturing capabilities — providing a concise playbook for M&A, licensing, or white‑label supply decisions in 2026.
Key growth drivers and market dynamics
Demand is being pulled by multiple vectors. Therapeutic programs continue to dominate development activity, supported by diagnostics and an expanding R&D services market. Advances in single-domain technologies and strategic partnerships are accelerating clinical throughput and industrialization. At the same time, manufacturing complexity and reimbursement dynamics introduce critical decision points:
Worldwide Microwave Power Supply Market
- Manufacturing complexity: Unlike full monoclonal antibodies, many fragment formats lack an Fc domain and therefore cannot leverage Protein A affinity capture. This forces multi-step purification (for example ion exchange and hydrophobic interaction chromatography), which our sector analysis shows can raise downstream manufacturing costs by as much as 60% versus conventional mAbs in equivalent scale scenarios. That differential changes calculus for insourcing vs. outsourcing and for the selection of formats in cost-sensitive indications.
- Production platform trade-offs: Microbial expression systems (E. coli, Pichia pastoris) have become a competitive advantage for scFv and nanobody formats, delivering high yields in optimized processes (reported up to ~150 mg/L in fed‑batch runs in the highest‑performing cases). However, process scalability, product quality attributes and regulatory pathways still favor mammalian systems for certain complex constructs.
- Half-life engineering and economics: PEGylation, albumin-binding moieties, or Fc fusion strategies extend half-life but materially increase COGS — often doubling or tripling costs — and therefore require careful pricing and indication selection to preserve margins.
- Regulatory and reimbursement constraints: Fragment therapeutics are assessed under the same rigorous preclinical and clinical frameworks as other biologics. Payer acceptance hinges on demonstrable real-world benefit and, for many indications, cost-effectiveness versus established mAbs or small molecules.
What PW Consulting’s report contains — practical tools for 2026 action
This research is built to be used, not just read. Highlights of the operational content include:
Worldwide IT Spending in Automotive Market
- Methodology and transparent modeling: Full disclosure of assumptions, sensitivity analyses and scenario modules so executives can re-run forecasts with their internal inputs.
- Market sizing and growth decomposition: Top-down and bottom-up frameworks that reconcile historical uptake (2020–2025) with forecasted adoption curves (2026–2032), including scenario runs for accelerated clinical success or slower reimbursement uptake.
- Technology and pipeline atlas: A mapped view of clinical programs and platform maturity across Fab, scFv and VHH/nanobody formats, annotated with development risk and commercial opportunity scores.
- Manufacturing economics toolkit: A modular cost‑of‑goods model that contrasts microbial vs. mammalian production, purification pathways, and the incremental cost impact of half-life extension technologies.
- Commercial playbooks: Guidance on go-to-market, pricing strategy, tendering, and payer engagement tailored to fragments’ product profiles and indication-specific value propositions.
- Partnering and deal flow intelligence: A curated database of recent partnerships, platform licensing, and CDMO capacity investments — designed to accelerate diligence and term‑sheet drafting.
- 90‑day implementation plans: Fast-start checklists for business development, CMC due diligence, and regulatory engagement to translate strategy into pipeline progress within a quarter.
Competitive landscape — what to watch in 2026
The market is characterized by major pharmaceutical groups advancing proprietary programs alongside specialized biomanufacturers and service providers offering bespoke production and platform capabilities. Key dynamics include platform consolidation, selective vertical integration, and differentiated route-to-market strategies:
- Large integrated pharmas (e.g., long-standing biologics leaders) continue to deploy antibody fragment strategies as part of diversified portfolios. Leaders with early commercial fragment products have a visible advantage in regulatory know-how and channel access for ophthalmic, autoimmune and oncology indications.
- Platform champions — companies that have invested in dedicated single-domain or Fab platforms — are working to commercialize the technology’s advantages (tissue penetration, manufacturability at small scale) while scaling CMC support to match rising clinical loads.
- Specialist service providers and CMOs are gaining share by offering end‑to‑end custom production (from construct optimization to GMP supply) and by mastering the non-Protein A purification sequences that fragments require. These providers reduce time‑to-clinic risk but compete on capacity and regulatory track record.
Notable corporate positions and recent moves illustrate these trends. Established innovators have clinically proven fragment therapeutics — providing a commercial blueprint and real‑world data — while specialty platform owners continue to demonstrate technology differentiation. In 2025 and early 2026 we have tracked several meaningful developments: a major platform advance by a leader in nanobody technologies, an expansion of partnerships by a prolific discovery partner, and a peer-reviewed industrialization review that consolidates decades of VHH production learnings. These signals indicate momentum across both proprietary pipeline and service-provider ecosystems.
Portfolio and partnering implications for executives
- Portfolio prioritization: Use our decision matrix to compare incremental revenue potential against incremental COGS and development risk. Fragments provide attractive clinical differentiation for tissue‑targeted and CNS applications, but only certain indications sustain premium pricing sufficient to cover higher COGS from complex purification or half-life engineering.
- Manufacturing strategy: For companies with multiple fragment programs, a hybrid approach — contracting early clinical supply to niche CDMOs and evaluating in‑house scale only for proven late‑stage assets — often minimizes capital burden while preserving strategic optionality.
- M&A and alliances: Buyers should look for targets with proven platform scalability or CDMOs with validated fragment workflows. Sellers should package clinical datasets, validated CMC routes, and payer‑level health economic models to maximize valuation.
- Regulatory and payer engagement: Early and active dialogue with regulatory bodies and payers will improve labeling outcomes and reimbursement positioning; value dossiers must explicitly address fragment-specific benefits and COGS implications of half‑life extension.
Market structure and concentration — what it means
The market shows a meaningful degree of concentration among leading players, creating advantages for incumbents with established clinical assets and manufacturing networks. For challengers, there is space to succeed via platform differentiation, superior CDMO service, or targeted indication strategies where fragment attributes deliver unambiguous clinical value.
Concluding guidance — five tactical moves for 2026
- Run a format-selection stress test on your pipeline: quantify net present value under alternative manufacturing and reimbursement scenarios.
- Secure flexible CMO capacity for first‑in‑human and Phase II supply; defer heavy capital expenditure until clinical inflection points are achieved.
- Negotiate option‑style partnerships with platform owners to manage upside while limiting near‑term cash outlays.
- Invest in payer evidence generation early for high-cost half‑life extension strategies; neutralize COGS objections with clear real‑world benefit plans.
- Monitor platform industrialization milestones and partnership announcements: these are leading indicators of where scale will materialize and margins can normalize.
Next steps — access the full intelligence
PW Consulting’s full report includes the detailed segmentation, company scorecards, financial models and a downloadable scenario tool that underpins the analyses summarized here. This press brief follows the “trailer” principle: it outlines the strategic narrative and modeling framework while reserving granular segment-level data, regional splits and firm-level revenue breakdowns for the complete report. For immediate access to the full dataset, methodologies and proprietary company dossiers to inform 2026 decisions, please visit the PW Consulting report page or contact our industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dal Mill Machine Market Set to Expand at a 6.12% CAGR Through 2032, New Report Says
By pmarketresearch, 2026-08-12
Worldwide Dal Mill Machine Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market study on the Worldwide Dal Mill Machine Market (base year 2025; forecast horizon 2026–2032) is designed as a decision intelligence tool for equipment OEMs, mill operators, private equity, and policy teams planning capital allocation in 2026. The global installed‑value of dal mill machinery rose from roughly USD 386 million in 2020 to USD 520 million in 2025, and our forward model points to continued expansion to the high‑seven‑hundreds by 2032 under a mid‑cycle compound annual growth rate of 6.12% across the forecast window. This trajectory reflects a mix of demand elasticity from pulse production growth, accelerating automation, and rising compliance and input‑cost pressures that will determine winners over the next investment cycle.
Worldwide Supply Chain Cost-To-Serve Analytics Software Market
Why 2026 Is an Inflection Year
Several converging forces make 2026 a pivotal year for strategic positioning in the dal mill equipment ecosystem:
Worldwide Coconut Soap Market
- Demand Momentum: Rising pulse production in major producing countries has created structural demand for capacity modernization and new processing lines. Processors are increasingly choosing automation to secure yield and consistency.
- Regulatory Tightening: Food safety mandates—most notably HACCP requirements phased in recently for dal processors—are elevating minimum technology thresholds for new installations and retrofits.
- Cost Pressures: Fabrication input prices and skilled labor inflation are compressing gross margins on new machinery and shortening payback tolerance for buyers; supply‑chain volatility for steel has already increased equipment lead times and capex budgets.
- Technology Migration: Machine vision, AI‑assisted sorting, PLC integration and predictive maintenance are migrating from premium plants into mass adoption, shifting competition from hardware alone to systems and services.
- Trade & Policy Risk: Export controls and duties on pulses in key origin markets are changing the economics of vertical integration and domestic milling, prompting processors to re‑think sourcing and capacity location.
What the Report Delivers — Actionable, Not Academic
This study is structured to support 2026 capital and commercial decisions. It balances rigorous market quantification with operational playbooks and commercial roadmaps rather than purely descriptive analysis. Key deliverables include:
Vacuum Sealing Drainage Market
- Time‑series market sizing (2020–2025) and a forecast model (2026–2032) with scenario toggles to test commodity cycles, steel price shocks, and regulation timing.
- Investment decision templates: capex sizing, throughput break‑even calculators and sensitivity matrices that translate technical specifications into payback curves for different buyer archetypes.
- Technology adoption roadmap mapping: stages from semi‑automatic compact lines to fully automatic plants with AI sorting, including modular migration paths for mid‑tier processors.
- Compliance and risk checklist (HACCP readiness, traceability chain design, and vendor validation protocols) tailored to the operational realities of dal plants.
- Service and aftermarket strategies: spare parts stocking models, remote diagnostics adoption triggers, and bundled maintenance commercial models that drive recurring revenue.
- Primary‑research insights: vendor interviews, plant site assessments, and buyer surveys underpinning our demand assumptions and OEM competitive positioning.
Competitive Landscape — Focused Profiles and Strategic Implications
The dal mill machinery market remains fragmented: incumbent vendors retain strong local relationships while specialist OEMs push technological differentiation. The top few vendors collectively account for a modest slice of global revenues, leaving substantial addressable market for scale‑up and consolidation plays. Our report profiles leading equipment providers and draws implications for partners and investors.
- Milltec Machinery Pvt. Ltd. (Bengaluru) — Market leadership in full‑line automatic plants with integrated cleaning, grading, splitting and polishing units. Milltec’s showcase of an AI‑driven sorting module at a major AgriTech expo in late 2025 signals an aggressive pivot toward systems that combine hardware and software monetization.
- Pramick Engineering Consultants (Hyderabad) — A strong play in compact and semi‑automatic solutions for small and growing processors. Recent product introductions emphasize energy efficiency, which appeals where operating cost reduction is a purchase trigger.
- GBS Engineering Enterprises (Hyderabad) — Known for turnkey processing lines with a focus on yield‑maximizing polishing and gravity selection. Large project deliveries to exporters underline capabilities in scale implementation.
- Jay Khodiyar, Narnoli, Bharat Agritech, Masoor Industries, United Oil Mill Machinery — Each of these firms occupies niches ranging from small‑scale compact plants to specialized lentil and pulse processing equipment and PLC‑based integrated systems. Their competitive advantage lies in rapid customization, local service networks, and price competitiveness.
Strategic implication: OEMs that combine mechanical reliability with digital sorting, modular automation and robust service propositions will widen margins and lock in customers; purely price‑based plays risk margin erosion as input costs rise and buyers prefer HACCP‑ready, warranty‑backed solutions.
Market Dynamics: Headwinds, Tailwinds and Tipping Points
- Raw material cost volatility: Fabrication materials experienced notable inflation in recent cycles, increasing machine build costs and lead times. Procurement strategies and local supply diversification will be central to margin preservation.
- Labor and skills: Skilled operator wages in food processing have risen materially, accelerating the ROI argument for automation in mid‑ and high‑throughput plants.
- Regulatory compliance: Mandated HACCP compliance raises the minimum technical and documentation requirements for new buyers and existing plants undergoing upgrades.
- Policy shifts on exports: Export duties on unprocessed pulses in key origin geographies are reshaping the calculus for greenfield mills versus merchant trade, creating new domestic demand for milling equipment.
Actionable Strategic Playbook for 2026
Based on scenario testing and vendor/processor interviews, PW Consulting recommends the following priority actions for different stakeholders:
- For OEMs: Accelerate modular automation offerings that allow staged investments; bundle digital sorting and predictive maintenance services with hardware; formalize HACCP compliance certification and simplify buyer on‑boarding with pre‑qualified installation packages.
- For Processors & Cooperatives: Prioritize HACCP‑compliant retrofits on legacy lines to protect market access; evaluate hybrid acquisition models (capex + service) to smooth cashflow; use sensitivity tools to determine the optimal automation layer that shortens payback while preserving flexibility.
- For Private Equity & Strategic Investors: Target consolidation plays that combine regional OEMs with complementary after‑sales networks, or invest in software overlays (AI sorting, remote monitoring) that can be white‑labeled across multiple equipment brands.
- For Policymakers & Development Agencies: Support programs for SME millers to access certified retrofit financing and training programs to accelerate compliance and productivity gains.
Business Cases & Expected Outcomes
In the report we present archetypal case studies mapping different throughput classes to realistic payback profiles and operational KPIs. While exact results depend on site‑specific variables, our portfolio of sensitivity tests shows how automation and adherence to food‑safety norms materially increase processed yield, reduce rework and open export channels—improving unit economics even after accounting for higher capex triggered by material and compliance costs.
Methodology & Why This Matters
PW Consulting’s approach combines bottom‑up build‑up of installed base value, vendor shipment triangulation, plant‑level throughput modeling and buyer willingness‑to‑pay surveys. We run three forecast scenarios to stress‑test strategic plans against a range of commodity, regulatory and input cost trajectories. The result is a set of decision tools you can apply directly to vendor selection, capex phasing and M&A screening.
What We Intentionally Withhold — And Why
This briefing is a strategic preview: we have deliberately showcased high‑level market sizing and directional insights while withholding granular segment breakouts and detailed regional/application shares. That detailed segmentation and the underlying spreadsheets are provided in the full report and accompanying datasets. If you require exact split tables, plant‑level shipment forecasts, or the full vendor scorecard with scoring matrices, our full deliverable contains those assets and the model with adjustable assumptions for bespoke scenarios.
How To Use This Intelligence in 90 Days
- Run a 1–2 day decision workshop using our scenario matrix to align capex horizons and risk tolerance among procurement, operations and finance.
- Prioritize one HACCP‑compliant pilot retrofit or a compact automated line purchase for mid‑throughput needs to validate operational metrics and buyer payback assumptions.
- Open supplier discussions with at least two OEMs from different positioning tiers (price leader vs. systems integrator) to compare TCO and service commitments under a standardized RFP template we provide.
Next Steps — Accessing the Full Report
PW Consulting offers tailored briefings that walk executive teams through the model, the vendor scorecard, and the ROI calculators. For teams making 2026 capex or M&A decisions in the dal mill equipment space, the full report converts market insight into executable project roadmaps and procurement playbooks.
Contact our Worldwide Agritech Practice for a demonstration, licensing options, and a detailed excerpt targeted to your company’s role in the value chain. The full dataset includes the regional and application-level breakouts, plant‑level shipment forecasts and the vendor scoring matrices omitted from this preview.
For detailed analysis of this topic, please visit the official page: Worldwide Dal Mill Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Self‑Checkout in Retail Market Poised to Expand at a 13.01% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Self-Checkout in Retail: A Strategic Preview for 2026 Decision-Makers
As retailers enter 2026, self-checkout is no longer a pilot-phase novelty or a labor-cost stopgap — it is a strategic frontier that will reshape store economics, customer experience, and data governance for the next decade. PW Consulting’s latest market study uses 2025 as the analytical base year and projects the global self-checkout market to grow at a compound annual growth rate of 13.01% through 2032. The market, measured in USD millions, is forecast to expand from a mid-single-digit billion base in 2025 to roughly 13.7 billion by 2032. These headline dynamics create both opportunity and risk for retail leaders who must decide, now, how aggressively to deploy, which technologies to standardize on, and how to manage the attendant compliance and shrinkage challenges.
Worldwide Cold Air Intakes Market
Why 2026 Is a Make-or-Break Year for Retailers
Several converging forces turn 2026 into a pivot point. Persistent labor shortages and rising wage pressures are changing store labor economics; the U.S. legal environment simultaneously tightened on overtime and privacy thresholds in 2024–2025, increasing the regulatory cost of operating traditional staffed lanes. At the same time, technology advances — notably AI-driven vision systems and cloud-native checkout platforms — are materially improving transaction speed, accuracy, and remote manageability. Collectively these trends accelerate ROI on automation while raising new requirements around privacy, security, and in-store loss prevention.
Worldwide Automotive Retail Software Market
Executives evaluating self-checkout strategies must weigh three interacting vectors: (1) the capital and operating cost savings from labor substitution and throughput increases; (2) emergent revenue and experience gains from frictionless, loyalty-linked checkout; and (3) the compliance burden and potential shrinkage exposure introduced by camera, sensor, and computer-vision technologies. Our study quantifies the economic trade-offs and models pragmatic rollout approaches so leadership teams can move from hypothesis to executable plans in 2026.
Waveform Generator Market
What PW Consulting’s Report Delivers — Practical, Decision-Ready Content
This report is designed for executives and practitioners who need actionable guidance rather than academic theory. Core deliverables include:
- Market sizing and forecast framework that links macro demand drivers to store-level economics and capital planning horizons (2026–2032).
- Scenario-based ROI and TCO models that allow CFOs and store operations leads to simulate deployment mixes by store format, labor cost regimes, and shrink profiles.
- Vendor selection matrices and vendor-fit maps that translate functional requirements into procurement-ready scorecards.
- Implementation playbooks: phased rollouts, hybrid checkout models (staffed + assisted + fully self), store footprint optimization, and staff retraining templates.
- Compliance and privacy checklists aligned to recent U.S. state privacy laws and best practices for biometric/vision data governance.
- Security and shrink-mitigation toolkits: loss-prevention controls, audit sampling methods, and integration patterns with payment and loyalty platforms.
- Contract negotiation levers: SaaS vs. perpetual licensing, cloud-service SLAs, hardware refresh cadence, and managed-services options.
The report is intentionally practitioner-focused: each chapter ends with “Decision Points” that a retail leadership team can use to build a 90–180 day action plan. In line with our “trailer” approach, this overview demonstrates the depth of our analysis while preserving the full segmentation tables and vendor scorecards for subscribers who access the complete report.
Competitive Landscape: What Leading Vendors Signal About Next-Gen Checkout
The vendor ecosystem is mature but dynamic. A mix of global incumbent integrators, specialized hardware suppliers, and AI-native startups are shaping product evolution. Key strategic observations for procurement and strategy teams:
- NCR Voyix Corporation continues to leverage cloud-native architecture and modular hardware to offer highly adaptable deployments across store formats. Its recent next‑generation platform emphasizes real-time orchestration and remote patching — attributes that reduce on-site service costs and accelerate feature rollout.
- Diebold Nixdorf is advancing AI-driven shrink reduction and non-barcode recognition through its Vynamic Smart Vision suite. These capabilities speak directly to one of retailers’ primary concerns: reconciling frictionless checkout with loss prevention.
- Toshiba Global Commerce Solutions and Fujitsu remain prominent among large-format grocery and hypermarket deployments, with strong engineering depth around hybrid checkout models and contactless scanning. Fujitsu’s collaborations with local software ecosystems demonstrate the value of joint innovation in markets with specific regulatory or process needs.
- Hardware specialists and component suppliers — including Zebra, Honeywell, and Datalogic — continue to strengthen the platform’s reliability and throughput, while AI-first entrants (for example, Mashgin) are challenging barcode‑centric models with computer-vision approaches that promise reduced checkout time for high-velocity SKUs.
- Regional specialists and system integrators round out the landscape, providing installation, integration, and managed services that are often the decisive factor in multi-store rollouts.
Recent product activity underscores two market directions: convergence (hardware + cloud + AI) and modularization (smaller, tabletop form factors, and compact kiosks for convenience/QSR). For example, Partner Tech’s “Paula” tabletop AI kiosk and NCR Voyix’s modular cloud update illustrate how suppliers are broadening value propositions beyond raw terminal sales to include ongoing services and software monetization.
Regulatory and Operational Headwinds: What Risk Managers Must Know
Self-checkout deployments now live at the intersection of retail operations, cybersecurity, and privacy law. Since 2025, multiple U.S. states implemented new privacy requirements that change how retailers may collect, retain, and analyze camera and sensor data. At the same time, retail-sector privacy maturity lags behind global averages; the cost of a data breach remains material, with industry benchmarks indicating multi‑million-dollar incident averages. Those realities require integration of legal and security teams into procurement, and a shift toward privacy-by-design architectures.
Operationally, shrinkage and theft remain challenging. Some retailers have limited self-checkout in high-shrink locations, even as terminal volumes continue to rise globally. The key risk mitigation approaches we examine include camera analytics tuned for false-positive reduction, hybrid staffing models that pair assisted lanes with supervised self-checkout, and transaction-level risk scoring that triggers lightweight interventions rather than blanket denials.
Strategic Imperatives for 2026 Executive Agendas
Retail leaders should prioritize four strategic moves this year:
- Define a clear checkout portfolio strategy: decide which store formats get fully self, which require assisted models, and where to maintain traditional lanes. This decision should be driven by localized shrink, labor economics, and customer behavioral signals.
- Shift procurement from hardware-centric buying to platform-based contracting: emphasize software features, cloud operations, security SLAs, and managed services that reduce lifecycle risk and total cost of ownership.
- Operationalize privacy and security: adopt data-minimization standards, encryption and retention policies, and clear consent flows for vision- or biometric-enabled systems to align with evolving state laws.
- Invest in change management: staff redeployment, loss-prevention training, and SME centers of excellence that can iterate on checkout rulesets and monitor fraud/susceptibility metrics in near real time.
These imperatives align with the economic trajectory modeled in our forecast: as the market grows at a double-digit clip, first-mover advantages accrue to retailers who can standardize quickly, control risk, and capture the operational upside.
How PW Consulting Helps You Turn Forecasts into Executable Plans
PW Consulting combines market forecasting, vendor benchmarking, and implementation expertise into a single report that is intended to be both strategic and immediately practical. Subscribers receive downloadable TCO models, vendor RFP templates, and region‑agnostic rollout roadmaps that expedite procurement and pilot validation cycles. We also provide executive briefings and scenario workshops to stress-test leadership assumptions under different labor-cost and regulatory scenarios.
For readers seeking the full data set — including detailed segmentation, regional dynamics, and the complete vendor scorecards — the primary report contains those tables and raw models. Our public summary intentionally omits the granular split tables to preserve the commercial value of the full analysis and to encourage a structured engagement that aligns with each retailer’s unique context.
Next Steps for Retail Leaders
If 2026 is to be the year your chain moves from experimentation to scale, the critical work begins with aligning finance, operations, IT, and legal around a single, measurable rollout plan. PW Consulting’s Worldwide Self-Checkout in Retail Market study provides the market context, risk framework, and operational toolkits to turn that alignment into tangible store deployments. Contact PW Consulting to request the full dataset, schedule a tailored briefing, or access the vendor scorecards and procurement templates that will accelerate your program.
For detailed analysis of this topic, please visit the official page: Worldwide Self-Checkout in Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Medium Entropy Alloys Market to Reach USD 235.94 Million by 2032 at 9.5% CAGR — North America Commands ~45.5% Share
By pmarketresearch, 2026-08-12
Worldwide Medium Entropy Alloys Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest industry release — the Worldwide Medium Entropy Alloys Market report (base year 2025, forecast period 2026–2032) — reframes how executives should approach material strategy, product roadmaps, and M&A in 2026. Our findings show the market expanding robustly from an estimated USD 125.0 Million in 2025 to approximately USD 235.9 Million by 2032, driven by a sustained compound annual growth rate (CAGR) of roughly 9.5%. For leaders weighing capital allocation, sourcing commitments, or technology bets next year, this research translates market momentum into concrete decision levers without requiring you to be a metallurgist.
Worldwide Physical Security Software Market
Why 2026 Is a Pivotal Year
Medium entropy alloys (MEAs) are transitioning from laboratory promise to industrial relevance. As additive manufacturing, high-temperature engines, and electrified propulsion systems each raise the bar for performance-to-cost ratios, supply-side constraints and regulatory pressures are converging to create both risk and strategic opportunity. The 9.5% CAGR captured in our forecast is not merely an arithmetic projection — it reflects intersecting vectors: accelerating demand in performance-critical applications, increased industrialization of powder and wrought routes, and the maturation of computational alloy design that lowers time-to-market for new formulations.
Submarine Fiber Cable for Deep Sea Market
Topline Market Dynamics (What the Numbers Imply)
- Historical acceleration: The market expanded markedly through the first half of this decade, reaching USD 125.0 Million in 2025 after a period of compound growth that validates industrial adoption pathways.
- Near-term inflection: Our forecast shows a near-term uplift in 2026 activity as OEM prototype programs convert into low-volume production runs, supported by improved powder supply and qualification standards.
- Strategic runway to 2032: By 2032 the market reaches roughly USD 235.9 Million under our base-case assumptions — a scale that supports multiple specialist suppliers, vertically integrated producers, and targeted M&A plays.
Key Strategic Implications for 2026
For executives setting 2026 plans, the data converges on a handful of action areas where timely choices will compound advantage:
Worldwide LCD Panel Sealant Market
- Supply-chain hedging: Volatility in nickel, cobalt and chromium markets increases the premium on upstream visibility. Procurement teams should institute staged offtake and indexed pricing clauses now, not as an afterthought.
- Qualification-first roadmaps: OEMs and tier suppliers should prioritize a dual-track strategy — invest in qualification for one MEA family directly aligned with near-term product programs, while funding exploratory alloy design projects for mid-term performance leaps.
- Additive-manufacturing (AM) alignment: As powder suppliers scale, AM producers will find value in locked supply arrangements and collaborative qualification programs that bundle feedstock specs with process windows and post-processing recipes.
- M&A and partnership posture: Given the attractive growth and moderate market concentration among established alloy players and niche powder specialists, 2026 is well suited for bolt-on acquisitions that secure feedstock, IP, or customer access versus large transformational deals.
- Regulatory compliance as a differentiator: Environmental and materials safety standards are tightening. Companies that integrate recycled feedstock streams and transparent lifecycle accounting will access cost and reputational advantages.
Competitive Landscape — Strategic Profiles
The competitive map is a blend of traditional specialty alloy producers, computational design firms, and powder-focused new entrants. Our report evaluates each firm on four strategic axes: product breadth and qualification, alloy innovation and IP, manufacturing scale (powder and wrought), and channel access to high-value OEMs.
- Established alloy producers (e.g., Carpenter Technology Corporation, ATI Inc., Haynes International): These incumbents benefit from deep qualification experience in aerospace and energy verticals, existing supply-chain relationships, and manufacturing capabilities that ease the path from alloy discovery to certified use. Their advantage in 2026 will be how they convert R&D into repeatable production flows and commercial alloy families.
- Materials engineering and computational specialists (e.g., QuesTek Innovations): Firms that pair physics-based modeling with informed experimental validation shorten development cycles. Strategic buyers should view them as force multipliers rather than standalone threats — partnership can accelerate internal alloy programs and lower technical risk.
- Global materials groups (e.g., Sandvik AB, VDM Metals, Hitachi Metals/Proterial): These players combine global channel reach with the ability to scale alloy production. Their strategic playbooks in 2026 will likely emphasize integrated offers: alloy, powder, and post-processing services targeted at tier-one OEMs.
- Powder & AM specialists (e.g., Matexcel, MSE Supplies, Stanford Advanced Materials): These companies occupy a critical junction between research adoption and volume manufacturing. For industrial users, securing reliable powder supply is as important as the metal’s chemistry; thus, these suppliers are potential strategic partners or acquisition targets.
Supply Chain, Raw Materials & Sustainability
Material sourcing dynamics are a practical constraint on growth. MEAs commonly draw on nickel, cobalt, chromium and titanium feedstocks — commodities that have experienced price and geopolitical swings. Our sector analysis highlights how concentrated upstream production can amplify supply disruptions and introduces procurement strategies including multi-sourcing, recycled content usage, and indexed purchasing agreements.
Recycling is both a risk mitigation and an ESG lever: using recycled stainless and nickel scrap materially reduces CO2 footprint versus primary production routes, and scrap pricing presently sits within a range that makes circular strategies commercially meaningful in many programs. Incorporating scrap streams, however, demands robust inbound inspection and process controls to avoid chemistry drift — something our operational playbooks address in depth.
Regulatory & Standards Landscape
Environmental regulations and material safety standards are increasing compliance costs for manufacturers. For 2026, regulatory shifts will not only affect process emissions and waste handling but also qualification timelines for alloys in regulated sectors (aerospace, defense, energy). Early engagement with certification bodies and transparent material provenance reporting will shorten time-to-market and reduce rework risk.
What Our Report Provides — The Practitioner’s Toolkit
This release is designed as a strategic toolkit, not an abstract forecast. Highlights include:
- Market sizing and scenario-based forecasts (2026–2032) anchored to primary research and quantitative modeling;
- Decision-oriented chapters: procurement playbooks, qualification roadmaps, AM integration checklists, and a supplier negotiation guide;
- Competitive benchmarking with actionable intelligence on capabilities, commercialization strategies, and acquisition rationale for leading firms;
- Supply-chain risk maps and a raw-materials volatility model enabling procurement teams to stress-test sourcing strategies;
- Regulatory impact matrices and sustainability pathways illustrating practical steps to integrate recycled content while maintaining performance; and
- M&A and partnership heatmaps: where to partner, where to buy, and where to build given your balance-sheet and time-to-market imperatives.
How Executives Should Use This Report in 2026
We designed the report around three executive workflows:
- Strategic planning & capital allocation: Use our scenario outputs to stress-test investment cases and to set milestones for de-risking product launches over the next 12–24 months.
- Procurement & supplier strategy: Adopt the recommended staged sourcing and indexed contracting templates to mitigate raw-material risk while securing preferential capacity.
- Technology & partnership scouting: Apply our vendor and capability matrices to prioritize partners for computational alloy design, powder supply, or AM process qualification based on your target application’s safety and lifecycle requirements.
Final Takeaway — Where to Focus in 2026
Medium entropy alloys are moving beyond academic novelty into sectors where incremental performance gains have outsized business value. The market trajectory to 2032 underscores a strategic window: early entrants and well-structured partners can capture disproportionate value if they align procurement, qualification and commercialization activities now. Conversely, delayed action will increase exposure to raw-material volatility and elongate qualification timelines — two factors that compound cost and time risk.
PW Consulting’s report offers granular playbooks and vendor-grade intelligence required to act decisively in 2026. For practitioners who need the full data suite (regional and application splits, supplier scorecards, and the confidential M&A heatmap) we have reserved those elements for report subscribers and clients — precisely the level of detail that supports investment memos, procurement contracts, and R&D roadmaps.
Next Steps
To evaluate how these findings intersect with your portfolio or product plans, contact PW Consulting for a briefing or to obtain the full Worldwide Medium Entropy Alloys Market report. We offer tailored executive summaries and deep-dive workshops that align the research with your 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Medium Entropy Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Molding Compound Market Forecast to Reach USD 3,128.18 Million by 2032
By pmarketresearch, 2026-08-12
PW Consulting Releases Worldwide Phenolic Molding Compound Market — Strategic Insights to Guide 2026 Decisions
PW Consulting today publishes a forward-looking brief derived from our full Worldwide Phenolic Molding Compound (PMC) Market report. As an industry that bridges traditional thermoset chemistry and high-performance applications, the PMC market is returning to a pathway of steady expansion: our modeled market reached approximately USD 2.25 billion in 2025 and, under the baseline scenario, is projected to grow at a compound annual growth rate (CAGR) of 4.85% through 2032, reaching just over USD 3.1 billion by the end of the forecast horizon. This release highlights the report’s strategic utility for executive teams planning capital allocation, supply-chain resilience initiatives, product roadmaps, and M&A activity in 2026 — while reserving detailed segment-level datapoints for the full report.
Worldwide Hadoop Operation Service Market
Executive snapshot: why phenolic molding compounds matter in 2026
-
Resilience and steady expansion: After a near-term cyclical trough in 2024, demand dynamics in 2025 show recovery supported by industrial retooling and sustained requirements from electrical & electronics and automotive subsegments. The mid-single-digit CAGR we project reflects a market that is neither hyper-growth nor mature stagnation; rather, it rewards selective investment and operational agility.
Worldwide Hard Contact Lens Market -
Feedstock sensitivity: Phenolic resin production remains sensitive to upstream phenol and cumene dynamics. Regional feedstock price volatility is creating divergent margin pressures and arbitrage opportunities that will shape sourcing and localization decisions in 2026.
3D SLAM Autonomous Driving Solution Market -
Certification and reliability requirements: Continued emphasis on electrical safety and performance standards sustains demand for UL-certified PMCs and drives product specification complexity for OEMs and tier suppliers.
Market dynamics to watch (Q1–Q4 2026)
-
Regional feedstock variance: Phenol pricing shows meaningful regional dispersion entering 2026. In Northeast Asia phenol averaged around USD 1.01/kg in March 2026 (an increase of ~8.6% versus December 2025), reflecting firm regional resin demand and tighter cumene feedstock economics. Europe exhibited a softer track with phenol near USD 1.00/kg in March 2026 (roughly a 3.8% decline from December), influenced by softer local resin demand and competitive import flows. North America’s phenol market was comparatively stable at about USD 1.18/kg in March 2026, down marginally from December.
-
Certification as a differentiator: UL certification remains an active gating factor for many electrical applications, covering flame performance, HWI/HAI behavior and thermal indexing. Manufacturers that maintain or pursue these credentials will enjoy clearer access to higher-specification OEM programs.
-
Competitive moves: Leading compounders are combining capacity plays with product innovation. Recent examples include Sumitomo Bakelite’s capacity expansion in Nantong (commissioned in 2024) and a March 2026 new-series launch focused on high-adhesion phenolic resins targeted for advanced compound formulations — a reminder that scale and product breadth both matter.
What’s inside the full PW Consulting report (practical, actionable content)
-
Quantitative market model — top-down and bottom-up projections across a multi-scenario framework (baseline, downside, and accelerated-adoption cases) with downloadable model files and sensitivity knobs for raw-material and demand shocks.
-
Supply-demand mapping — manufacturing topology, regional capacity flows, typical lead times and cost components across the value chain (feedstock → resin → compound → molded part).
-
Price and margin stress-testing — scenario runs showing pass-through potential under several phenol and energy price trajectories.
-
Segmentation frameworks — demand by type and application with qualitative drivers and an overlay of regulatory and certification requirements. (Note: detailed numeric splits at the region/application/type level are available in the full dataset.)
-
Competitive benchmark and capability matrix — strategic profiles for global and regional players, mapped by technology, capacity footprint, product specs, and go-to-market channels.
-
Operational playbooks — supply-chain hedging templates, near-term capacity deployment checklists, and product-launch playbooks designed for both compounders and OEM material engineers.
-
M&A and partnership screening tool — a short-listing methodology, valuation heuristics tied to capacity and technology premium, and red-flag diagnostics for integration risk.
-
Risk register and mitigation measures — from raw-material shocks to regulatory shifts affecting flame retardant and electrical safety listings.
Strategic takeaways for 2026 corporate planners
-
Embed feedstock scenarios into every commercial decision: Given the observed regional phenol price dispersion and the sensitivity of margins to raw-material swings, procurement teams should run at least three phenol-price scenarios when evaluating multi-year supply agreements or localized capacity builds.
-
Prioritize certification roadmaps for electrical applications: UL and equivalent attestations continue to be entry requirements for high-margin, specification-driven programs. Investment in certification and test-lab partnerships unlocks premium OEM business.
-
Adopt a hybrid localization strategy: Use regional production to manage lead times and mitigate shipping-cost volatility where feedstock economics permit, and use centralized production plus inventory buffering for commodity-grade offerings.
-
Differentiate through formulation and value-added services: High-adhesion, heat-resistant, and filler-optimized compounds gain traction with EV, industrial, and aerospace specifications. Technical service capabilities that shorten qualification cycles are a commercial advantage.
-
Use M&A selectively to access technology gaps: The market remains moderately fragmented; transactions that secure capacity plus proprietary formulations or certification pipelines are likely to be value-accretive.
Competitive landscape — who matters and why
The PMC space blends multinational incumbents with regionally specialized compounders. Market concentration is modest: the top three players account for roughly one quarter of global market share, while the top five collectively approach around 39% — a structure that supports both scale-driven players and nimble specialists. Key company archetypes in the competitive set include:
-
Sumitomo Bakelite Co., Ltd. (Tokyo) — A vertically integrated player with global production footprint and a strong presence in glass-fiber-reinforced and filler-optimized compounds. Recent strategic moves include commissioning a Nantong plant (2024) to expand capacity and launching a high-adhesion phenolic resin line in March 2026, signaling continued investment in both scale and formulation innovation.
-
PLENCO (Plastics Engineering Company, USA) — A specialist in novolac and resol chemistries, delivering dimensional stability and thermal/electrical performance across compression, transfer, and injection molding processes.
-
Bakelite Synthetics (Bakelite, USA/global sites) — Focused on high-quality thermoset solutions with strong brand recognition among consumer, electrical and industrial customers.
-
Chang Chun Plastics (Taiwan) — Provider of customer-specific heat-hardening resin compounds for electrical and automotive applications with an emphasis on configurable formulations.
-
Resinoid Engineering (USA) — Known for custom compounding and high-temperature phenolic materials used in aftermarket and demanding industrial applications.
-
Shengquan Group (China) — A major resin supplier with scale advantages in phenolic resin production, enabling competitive raw-material positioning for compounders.
-
Kaihua Ruida (Zhejiang, China) — Manufacturer of UL-recognized phenolic molding compounds and Bakelite powders for appliance, construction and automotive end markets.
For OEMs and investors, the takeaway is clear: scale and product breadth remain valuable, but targeted technical differentiation and certification-readiness create defensible commercial corridors.
Raw-material and regulatory signals — immediate implications
-
Price transmission and margin management: Regional phenol price spreads in early 2026 are not merely academic — they drive margins on formulated compounds and influence decisions on where to site incremental compound capacity or buffer inventories.
-
Regulatory and standards continuity: The persistence of UL certification regimes for flame, HWI/HAI and RTI metrics means that redesign cycles for electrical components must account for test-, retest- and qualification windows when switching materials or suppliers.
How procurement, R&D, and corporate development teams should use this analysis in 2026
-
Procurement: Use the report’s live model to test multi-year off-take pricing and to design indexation clauses tied to phenol and energy inputs.
-
R&D and product engineering: Leverage the formulation benchmarking and certification matrix when prioritizing material swaps for thermal and electrical performance upgrades.
-
Corporate development: Apply the M&A screening tool and valuation heuristics to prioritize targets that provide immediate route-to-market in high-spec segments or that close key technical gaps.
-
Operations: Integrate supply-chain mapping and stress tests into contingency planning for feedstock shocks and logistics disruptions, especially for export-dependent facilities.
Next steps — where to access the full intelligence
This briefing is a strategic preview designed to surface the critical decisions facing leaders in the phenolic molding compound value chain in 2026. The full PW Consulting Worldwide Phenolic Molding Compound Market report contains the granular regional and application-level data, interactive market models, company profiles, proprietary scenario outputs and execution-ready playbooks referenced above. To obtain the full report, model files, and advisory support for applying these findings to your specific business case, please contact PW Consulting or visit our publications page to request access to the complete dataset and client-only briefing sessions.
PW Consulting remains available to support scenario workshops, supplier diligence, and post-acquisition integration planning informed by the report’s quantitative and qualitative findings.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Skin Care Products Tubes Market Poised to Reach USD 26,825.63 Million by 2032 on a 5.45% CAGR
By pmarketresearch, 2026-08-12
Worldwide Skin Care Products Tubes Market: Strategic Outlook for 2026
As companies finalize budgets and roadmaps for 2026, our latest PW Consulting market brief — the Worldwide Skin Care Products Tubes Market — delivers the actionable market architecture leaders need to convert uncertainty into advantage. Built on a rigorous 2020–2025 historical base and projecting through 2032, the study synthesizes macro trajectory, cost and regulatory shocks, competitor playbooks, and pragmatic go‑to‑market scenarios. The headline: the global tubes market is poised to expand at a mid-single‑digit compound annual growth rate (CAGR) of 5.45% and continues to scale in nominal terms, providing both margin recovery opportunities and structural disruption risks for suppliers, brand owners and investors alike.
Worldwide Embalming Fluid Market
Why this report matters for 2026 decisions
-
Timing and framing: 2026 is the inflection year when sustainability mandates, raw material volatility and shifting consumer preferences converge. Executives who lock in strategy early — balancing near‑term operational resilience with medium‑term circularity investments — will capture disproportionate share when the market re‑rates.
Spool Position Sensor Market -
Grounded forecasting: our base year is 2025, with a transparent forecast through 2032. The dataset gives CFOs and corporate strategists a defensible revenue run‑rate and scenario sensitivity to cost shocks and policy changes.
Wound Stator Shell for Electric Motors Market -
Decision focus: this is not a descriptive catalogue. The brief translates trends into decision levers — procurement hedging strategies, retrofit vs. replace product roadmaps, regional footprint choices and M&A playbooks — calibrated to real commercial constraints.
Core takeaways — high‑impact strategic signals
-
Resilience first: volatile resin markets and uneven tariff regimes are compressing unit economics in the near term. Our modelling shows that a combination of flexible sourcing, indexed contracts and selective pass‑through pricing preserves margins without sacrificing share.
-
Sustainability is now a hard constraint: regulatory timelines (for example, EU recycled content mandates) and escalating retailer requirements mean product teams must prioritize mono‑material designs and validated recycling pathways. Delaying technical validation risks market access and higher remediation costs after 2027.
-
Premiumization meets functionality: premium skincare continues to demand airless and high‑barrier systems. This opens a two‑track value creation path — premium converters and system integrators can extract higher ASPs, while low‑cost flexible suppliers must compete on efficiency and compliance.
-
Fragmented supplier base — opportunity for consolidation: the market displays modest concentration, with leading manufacturers holding a meaningful but not dominant share. This creates room for targeted M&A to acquire scale in strategic geographies or capabilities (e.g., airless systems, mono‑material tooling).
What’s in the PW Consulting report — a practitioner’s toolkit
-
Market sizing and validated forecast (2026–2032) with scenario overlays that test raw material spikes, tariff escalations and accelerated sustainability adoption.
-
Segment architecture and buyer archetypes: product families, material choices, application patterns and typical buyer negotiation logic — translated into playbooks for converters and brand procurement.
-
Supply chain and cost build‑up models: from resin and barrier films through conversion, cap/closure systems and finished goods logistics — including a sensitivity engine that quantifies margin impact under plausible HDPE and film price swings.
-
Regulatory and policy matrix: country‑level requirements, upcoming compliance milestones, and a prioritized list of certification or testing actions that materially affect time‑to‑market.
-
Competitive landscaping with deep profiles: operating models, R&D roadmaps, recent launches, manufacturing footprints and strategic intents for the leading suppliers in the space.
-
Deal and partnership playbooks: criteria and valuation heuristics for tuck‑ins, capability buys and JV structures tailored to converters, material suppliers and brand owners.
-
Commercial scorecards and procurement templates: negotiation levers, KPI dashboards and a supplier risk rubric to operationalize the study’s insights in 90‑day sprints.
Competitive landscape — who to watch
The skin care tubes ecosystem comprises global converters, specialty system providers and regional custom houses. Key players combine scale manufacturing with increasingly sophisticated sustainability offers and dispensing systems. The report examines the strategies and operational plays of market leaders, including:
-
Albéa Group (Gennevilliers, France): a global leader across laminated, plastic and aluminum tubes; notable for accelerating mono‑material tube innovations and recyclable snap‑top designs introduced in late 2024.
-
Silgan Holdings Inc. (Stamford, CT, USA): through its dispensing division, a major provider of plastic tubes and precision dispensing systems tailored to skincare applications.
-
AptarGroup Inc. (Crystal Lake, IL, USA): focused on airless and pump architectures for clean beauty brands — investing in trade‑show visibility and application engineering to capture premium segments.
-
Amcor plc (Zurich, Switzerland): a flexible packaging giant emphasizing recyclable, high‑barrier materials suitable for sensitive formulations.
-
Berry Global Group Inc. (Evansville, IN, USA): offers both rigid and flexible formats with an increasing emphasis on weight reduction and sustainability certification.
-
Huhtamäki Oyj (Espoo, Finland): known for laminate and mono‑material tube innovations aimed at recyclability and circularity.
-
Virospack S.A. (Barcelona, Spain): a specialty provider of premium airless systems tailored to high‑end skincare brands.
-
Intrapac International Pty Ltd (Keysborough, Australia): a regional custom supplier with capabilities to serve APAC formulas and rapid prototyping needs.
Each profile in the report includes capability matrices, recent product launches, capital intensity estimates and acquisition targets — information that informs realistic competitive moves in 2026 without relying on conjecture.
Recent developments and tactical implications
-
Product launches and system innovations: several leading suppliers intensified their activity in 2024–2025 with recyclable snap‑top tubes and new airless platforms. These moves accelerate the adoption of mono‑material solutions and force legacy packaging to justify its environmental credentials.
-
Sustainability certifications: select manufacturers secured third‑party verification in 2024, creating short‑term commercial leverage with global beauty brands seeking validated supplier partners.
-
Raw material and trade signals: European polymer prices and persistent tariff regimes in certain markets are altering landed costs. Brands and converters must model these inputs explicitly in pricing and sourcing decisions.
Market dynamics to monitor in 2026
-
Cost volatility: our scenario analysis models a range of HDPE cost pathways and shows that procurement agility (index‑linked contracts, regional sourcing hubs) materially outperforms static cost models in protecting gross margins.
-
Regulatory milestones: regulatory requirements for recycled content and packaging waste management will compress the window for compliance investments; early movers that validate mono‑material recycling pathways gain both cost and reputational advantage.
-
Commercial premiumization: airless and premium dispensing systems sustain higher average selling prices for converters that can deliver technical assurance; this segment will remain attractive for strategic investments.
-
Trade friction and reshoring: tariffs and logistics friction are prompting selective regionalization of capacity for sensitive markets — a strategic decision for companies weighing capex versus variable cost exposure.
How to use this briefing in 90–180 day plans
-
Procurement: implement a two‑lane sourcing approach — lock minimum volume coverage with diversified suppliers while piloting mono‑material alternatives with preferred converters.
-
R&D and product: prioritize rapid technical verification of recyclable tube formats for top SKUs and allocate a small, protected test budget to airless integrations for premium launches.
-
M&A and partnerships: screen targets for capability gaps — look for converters with proprietary airless systems, tooling capacity in strategic geographies, or validated recyclability claims.
-
Regulatory readiness: establish a compliance sprint team to map product SKUs against jurisdictional mandates and certification timelines; this reduces rework and market withdrawal risk.
Closing — the strategic edge for 2026
2026 is not a year to “wait and see.” It will be a year of crystallization: policy deadlines, cost pressures and consumer demand will force decisions that have multi‑year revenue and margin consequences. PW Consulting’s Worldwide Skin Care Products Tubes Market report gives executives the mixed quantitative and tactical intelligence required to make those decisions with conviction: validated market sizing, sensitivity testing, supplier scorecards and direct playbooks for procurement, R&D and M&A.
We deliberately present depth without disclosing every cell in the dataset here. For the full forecast tables, granular segmentation, company valuation heuristics and the downloadable financial model that you can plug into your 2026 planning process, please access the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care Products Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Rapid Expansion of Worldwide Foot Traffic & Customer Location Intelligence Market with 15.65% CAGR
By pmarketresearch, 2026-08-12
Worldwide Foot Traffic and Customer Location Intelligence Solution Market — Strategic Imperatives for 2026
PW Consulting is pleased to release an executive briefing drawn from our new market research, Worldwide Foot Traffic and Customer Location Intelligence Solution Market. As organizations plan budgets and strategy for 2026, this briefing highlights the commercial and operational levers that will determine winners and laggards in the era where physical places are instrumented, and location data becomes a strategic asset. The full report delivers the granular inputs, vendor scorecards, and datasets that enterprise leaders and investors need; this release serves as a high-fidelity preview of the report’s strategic value while reserving the proprietary segment-level details for subscribers.
Worldwide Anime Peripheral Market
Market trajectory and what it signals for 2026 decisions
The market for foot traffic and customer location intelligence has evolved from an emerging analytics niche into a mainstream technology stack. Our analysis shows the total addressable market growing materially during the early 2020s, with a pronounced acceleration into 2025 driven by renewed investments in physical retail analytics, smart building deployments, transportation optimization, and location-aware marketing. The market’s momentum continues: the forecast period beginning in 2026 assumes a robust compound annual growth rate (CAGR) of 15.65%, reflecting a combination of higher enterprise adoption, AI-driven analytics maturation, and new data fusion architectures that link mobile, sensor, and video sources.
Adaptable Accelerator Cards Market
For C-suite leaders planning 2026 spends, the message is straightforward: this is no longer an experimental line item. Location intelligence solutions will increasingly be interpreted as strategic infrastructure—analogous to CRM or ERP—because they directly inform site strategy, customer acquisition and retention, operational staffing, and property valuation. Firms that treat location intelligence as tactical will risk inefficient capital allocation and missed revenue uplift.
Electric 3 Wheel Forklift Truck Market
What the report provides (practical, operational content)
- Actionable vendor selection frameworks that prioritize data provenance, model explainability, update cadence, and API interoperability.
- Implementation blueprints for hybrid data architectures (edge sensors + centralized analytics), including reference hardware topologies, privacy-preserving ingestion pipelines, and integration patterns with POS, CRM, and digital ad stacks.
- ROI and TCO models tailored to common enterprise use cases—site selection, trade-area cannibalization analysis, marketing attribution, labor optimization, and asset-level valuation—enabling finance teams to stress-test investment cases.
- Data governance and compliance playbooks: practical approaches for data minimization, differential privacy, sovereign storage options, and contractual clauses to mitigate legal exposure in multi-jurisdiction deployments.
- Operational checklists and KPIs for pilot-to-scale transitions, including sample SLAs for data freshness and accuracy, sample RFP language, and vendor negotiation levers.
- Case studies and “war stories” from real-world deployments that surface common failure modes and the remediation steps that saved projects from under-delivering.
Technology realities and integration trade-offs
The ecosystem is technologically heterogeneous. Wi‑Fi and Bluetooth/BLE systems offer high-frequency, low-cost presence signals; GPS and satellite positioning provide coarse-grain outdoor traces; AI-based video analytics deliver higher-fidelity in-store behavioral insights; and infrared/thermal sensors enable anonymous counting in privacy-sensitive environments. The strategic choice is rarely binary. Instead, winning implementations are multi-modal: they fuse multiple sensor classes to raise signal-to-noise, compensate for coverage gaps, and provide layered attestations of the same event.
Key technical decisions for 2026 include where to place compute (edge vs. cloud), how to design resilient data pipelines, and how to implement privacy-preserving techniques without destroying business value. Increasingly important are data quality metrics—refresh intervals, dropout rates, and source lineage—because analytics outcomes are only as defensible as the inputs. Another emergent consideration is spectrum management for wireless sensors. Ongoing regulatory and standards discussions around spectrum sharing and AI-enabled spectrum utilization will influence hardware selection and deployment cadence in the coming 18–24 months.
Regulation and data sovereignty — design constraints that matter
Regulatory dynamics are no longer peripheral. Data sovereignty regimes are forcing providers and customers to rethink architectures, particularly where local laws mandate the storage or processing of raw location signals within national borders. At the same time, extraterritorial access regimes—such as provisions that permit access to data held by companies under certain jurisdictions—create compliance risks for multinational deployments. Enterprises must bake these considerations into procurement and legal documentation: contractual data residency guarantees, clear incident response processes, and the option to operate in “local-only” modes where required.
Competitive landscape: segmentation by capability and go-to-market
The market exhibits moderate concentration: a handful of vendors lead with broad platform capabilities while a larger group of specialists address vertical or technical niches. Market concentration metrics underscore this balance—there is leadership visibility, but also ample room for new entrants and strategic partnerships.
- Platform-first companies (example profiles): Firms that aggregate large-scale anonymized mobility footprints and expose analytics via SaaS APIs. They excel at cross-property comparisons, trend analysis, and site selection analytics.
- Mapping and GIS stalwarts: Companies with deep cartographic and spatial modeling expertise that bring strength in routing, spatial analytics, and enterprise GIS integrations—useful for municipal and infrastructure use cases.
- Sensor and in-store specialists: Vendors that supply people counters, camera-based analytics, and edge devices optimized for in-store conversion and queue management.
- Data suppliers and aggregators: Organizations that focus on raw mobility or POI datasets, enabling downstream analytics firms and internal data teams to build bespoke models.
Strategically, this stratification produces three repeatable vendor archetypes enterprises will encounter: (1) full-stack platforms that bundle data, analytics, and dashboards; (2) best-of-breed analytics vendors that prioritize model quality and APIs; and (3) hardware-oriented suppliers who increasingly pair sensors with software services. Our vendor benchmarking highlights not only capability differentials, but also differences in contract models, privacy practices, and service maturity.
Recent market signals and vendor moves (what to watch in early 2026)
- Thought leadership and market education activities are intensifying—vendors are investing in education to move buyers up the value curve (for example, recent webinars aimed at economic developers and retail real estate audiences).
- Strategic integrations between location analytics providers and commercial real estate platforms have emerged, signaling faster adoption among institutional investors and REITs that want asset-level consumer behavior inputs.
- Product enhancements focused on site selection, cannibalization modeling, and trade-area overlap demonstrate that vendors are migrating from descriptive metrics to predictive tools that drive capital allocation decisions.
Five strategic imperatives for enterprise leaders in 2026
- Adopt a hybrid data strategy: combine mobile, sensor, and video-derived signals to increase robustness and reduce single-source risk.
- Prioritize privacy and sovereignty in procurement: demand technical and contractual support for localized processing and demonstrable privacy-enhancing measures.
- Measure and operationalize: shift from vanity metrics (raw counts) to operational KPIs tied to revenue, cost, or asset valuation—define success metrics before vendor selection.
- Architect for modularity: prefer vendors that expose APIs and allow you to replace components without a forklift migration; this lowers switching costs as the market consolidates.
- Insist on clear SLAs and data lineage: accuracy, freshness, and provenance matter for high-stakes uses such as valuations or regulatory reporting.
Investment and partnership lens
For investors and strategic partners, the macro dynamics are compelling. The market’s expansion, combined with an ecosystem that mixes incumbents with nimble specialists, creates opportunities for both platform consolidation and vertical specialization plays. Key diligence areas are recurring revenue quality, customer retention on multi-year contracts, margin profiles across hardware/software/services bundles, and regulatory exposure across key operating geographies.
What the full PW Consulting report includes (and why you should read it)
The full report contains the detailed forecasts (covering 2026–2032), vendor profiles with capability matrices, use-case economic models, procurement templates, and the raw datasets that informed our market sizing and growth assumptions. It also provides a scenario analysis that maps regulatory and technology shocks to demand outcomes so decision makers can build contingency plans into 2026 budgets.
We intentionally keep this release a strategic preview. The core, segment-level insights and the proprietary dashboards that enable point-by-point comparison of vendors and use cases are available in the full report. Executives and investors who need to make procurement, partnership, or M&A decisions in 2026 should consult the report to access the detailed metrics and supplier scorecards that drive defensible choices.
PW Consulting’s Worldwide Foot Traffic and Customer Location Intelligence Solution Market research is built for leaders who must translate location signals into strategic advantage. To obtain the full report, vendor scorecards, and the interactive forecast models, please visit our website or contact the PW Consulting research desk for enterprise access and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com