

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medium Entropy Alloys Market to Reach USD 235.94 Million by 2032 at 9.5% CAGR — North America Commands ~45.5% Share

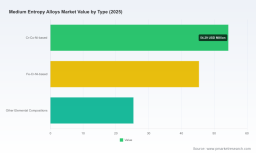
Worldwide Medium Entropy Alloys Market — Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest industry release — the Worldwide Medium Entropy Alloys Market report (base year 2025, forecast period 2026–2032) — reframes how executives should approach material strategy, product roadmaps, and M&A in 2026. Our findings show the market expanding robustly from an estimated USD 125.0 Million in 2025 to approximately USD 235.9 Million by 2032, driven by a sustained compound annual growth rate (CAGR) of roughly 9.5%. For leaders weighing capital allocation, sourcing commitments, or technology bets next year, this research translates market momentum into concrete decision levers without requiring you to be a metallurgist.
Worldwide Physical Security Software Market
Why 2026 Is a Pivotal Year
Medium entropy alloys (MEAs) are transitioning from laboratory promise to industrial relevance. As additive manufacturing, high-temperature engines, and electrified propulsion systems each raise the bar for performance-to-cost ratios, supply-side constraints and regulatory pressures are converging to create both risk and strategic opportunity. The 9.5% CAGR captured in our forecast is not merely an arithmetic projection — it reflects intersecting vectors: accelerating demand in performance-critical applications, increased industrialization of powder and wrought routes, and the maturation of computational alloy design that lowers time-to-market for new formulations.
Submarine Fiber Cable for Deep Sea Market
Topline Market Dynamics (What the Numbers Imply)
- Historical acceleration: The market expanded markedly through the first half of this decade, reaching USD 125.0 Million in 2025 after a period of compound growth that validates industrial adoption pathways.
- Near-term inflection: Our forecast shows a near-term uplift in 2026 activity as OEM prototype programs convert into low-volume production runs, supported by improved powder supply and qualification standards.
- Strategic runway to 2032: By 2032 the market reaches roughly USD 235.9 Million under our base-case assumptions — a scale that supports multiple specialist suppliers, vertically integrated producers, and targeted M&A plays.
Key Strategic Implications for 2026
For executives setting 2026 plans, the data converges on a handful of action areas where timely choices will compound advantage:
Worldwide LCD Panel Sealant Market
- Supply-chain hedging: Volatility in nickel, cobalt and chromium markets increases the premium on upstream visibility. Procurement teams should institute staged offtake and indexed pricing clauses now, not as an afterthought.
- Qualification-first roadmaps: OEMs and tier suppliers should prioritize a dual-track strategy — invest in qualification for one MEA family directly aligned with near-term product programs, while funding exploratory alloy design projects for mid-term performance leaps.
- Additive-manufacturing (AM) alignment: As powder suppliers scale, AM producers will find value in locked supply arrangements and collaborative qualification programs that bundle feedstock specs with process windows and post-processing recipes.
- M&A and partnership posture: Given the attractive growth and moderate market concentration among established alloy players and niche powder specialists, 2026 is well suited for bolt-on acquisitions that secure feedstock, IP, or customer access versus large transformational deals.
- Regulatory compliance as a differentiator: Environmental and materials safety standards are tightening. Companies that integrate recycled feedstock streams and transparent lifecycle accounting will access cost and reputational advantages.
Competitive Landscape — Strategic Profiles
The competitive map is a blend of traditional specialty alloy producers, computational design firms, and powder-focused new entrants. Our report evaluates each firm on four strategic axes: product breadth and qualification, alloy innovation and IP, manufacturing scale (powder and wrought), and channel access to high-value OEMs.
- Established alloy producers (e.g., Carpenter Technology Corporation, ATI Inc., Haynes International): These incumbents benefit from deep qualification experience in aerospace and energy verticals, existing supply-chain relationships, and manufacturing capabilities that ease the path from alloy discovery to certified use. Their advantage in 2026 will be how they convert R&D into repeatable production flows and commercial alloy families.
- Materials engineering and computational specialists (e.g., QuesTek Innovations): Firms that pair physics-based modeling with informed experimental validation shorten development cycles. Strategic buyers should view them as force multipliers rather than standalone threats — partnership can accelerate internal alloy programs and lower technical risk.
- Global materials groups (e.g., Sandvik AB, VDM Metals, Hitachi Metals/Proterial): These players combine global channel reach with the ability to scale alloy production. Their strategic playbooks in 2026 will likely emphasize integrated offers: alloy, powder, and post-processing services targeted at tier-one OEMs.
- Powder & AM specialists (e.g., Matexcel, MSE Supplies, Stanford Advanced Materials): These companies occupy a critical junction between research adoption and volume manufacturing. For industrial users, securing reliable powder supply is as important as the metal’s chemistry; thus, these suppliers are potential strategic partners or acquisition targets.
Supply Chain, Raw Materials & Sustainability
Material sourcing dynamics are a practical constraint on growth. MEAs commonly draw on nickel, cobalt, chromium and titanium feedstocks — commodities that have experienced price and geopolitical swings. Our sector analysis highlights how concentrated upstream production can amplify supply disruptions and introduces procurement strategies including multi-sourcing, recycled content usage, and indexed purchasing agreements.
Recycling is both a risk mitigation and an ESG lever: using recycled stainless and nickel scrap materially reduces CO2 footprint versus primary production routes, and scrap pricing presently sits within a range that makes circular strategies commercially meaningful in many programs. Incorporating scrap streams, however, demands robust inbound inspection and process controls to avoid chemistry drift — something our operational playbooks address in depth.
Regulatory & Standards Landscape
Environmental regulations and material safety standards are increasing compliance costs for manufacturers. For 2026, regulatory shifts will not only affect process emissions and waste handling but also qualification timelines for alloys in regulated sectors (aerospace, defense, energy). Early engagement with certification bodies and transparent material provenance reporting will shorten time-to-market and reduce rework risk.
What Our Report Provides — The Practitioner’s Toolkit
This release is designed as a strategic toolkit, not an abstract forecast. Highlights include:
- Market sizing and scenario-based forecasts (2026–2032) anchored to primary research and quantitative modeling;
- Decision-oriented chapters: procurement playbooks, qualification roadmaps, AM integration checklists, and a supplier negotiation guide;
- Competitive benchmarking with actionable intelligence on capabilities, commercialization strategies, and acquisition rationale for leading firms;
- Supply-chain risk maps and a raw-materials volatility model enabling procurement teams to stress-test sourcing strategies;
- Regulatory impact matrices and sustainability pathways illustrating practical steps to integrate recycled content while maintaining performance; and
- M&A and partnership heatmaps: where to partner, where to buy, and where to build given your balance-sheet and time-to-market imperatives.
How Executives Should Use This Report in 2026
We designed the report around three executive workflows:
- Strategic planning & capital allocation: Use our scenario outputs to stress-test investment cases and to set milestones for de-risking product launches over the next 12–24 months.
- Procurement & supplier strategy: Adopt the recommended staged sourcing and indexed contracting templates to mitigate raw-material risk while securing preferential capacity.
- Technology & partnership scouting: Apply our vendor and capability matrices to prioritize partners for computational alloy design, powder supply, or AM process qualification based on your target application’s safety and lifecycle requirements.
Final Takeaway — Where to Focus in 2026
Medium entropy alloys are moving beyond academic novelty into sectors where incremental performance gains have outsized business value. The market trajectory to 2032 underscores a strategic window: early entrants and well-structured partners can capture disproportionate value if they align procurement, qualification and commercialization activities now. Conversely, delayed action will increase exposure to raw-material volatility and elongate qualification timelines — two factors that compound cost and time risk.
PW Consulting’s report offers granular playbooks and vendor-grade intelligence required to act decisively in 2026. For practitioners who need the full data suite (regional and application splits, supplier scorecards, and the confidential M&A heatmap) we have reserved those elements for report subscribers and clients — precisely the level of detail that supports investment memos, procurement contracts, and R&D roadmaps.
Next Steps
To evaluate how these findings intersect with your portfolio or product plans, contact PW Consulting for a briefing or to obtain the full Worldwide Medium Entropy Alloys Market report. We offer tailored executive summaries and deep-dive workshops that align the research with your 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Worldwide Medium Entropy Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com