

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Self‑Checkout in Retail Market Poised to Expand at a 13.01% CAGR Through 2032

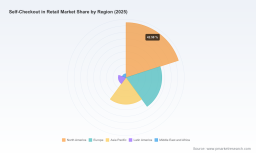
Worldwide Self-Checkout in Retail: A Strategic Preview for 2026 Decision-Makers
As retailers enter 2026, self-checkout is no longer a pilot-phase novelty or a labor-cost stopgap — it is a strategic frontier that will reshape store economics, customer experience, and data governance for the next decade. PW Consulting’s latest market study uses 2025 as the analytical base year and projects the global self-checkout market to grow at a compound annual growth rate of 13.01% through 2032. The market, measured in USD millions, is forecast to expand from a mid-single-digit billion base in 2025 to roughly 13.7 billion by 2032. These headline dynamics create both opportunity and risk for retail leaders who must decide, now, how aggressively to deploy, which technologies to standardize on, and how to manage the attendant compliance and shrinkage challenges.
Worldwide Cold Air Intakes Market
Why 2026 Is a Make-or-Break Year for Retailers
Several converging forces turn 2026 into a pivot point. Persistent labor shortages and rising wage pressures are changing store labor economics; the U.S. legal environment simultaneously tightened on overtime and privacy thresholds in 2024–2025, increasing the regulatory cost of operating traditional staffed lanes. At the same time, technology advances — notably AI-driven vision systems and cloud-native checkout platforms — are materially improving transaction speed, accuracy, and remote manageability. Collectively these trends accelerate ROI on automation while raising new requirements around privacy, security, and in-store loss prevention.
Worldwide Automotive Retail Software Market
Executives evaluating self-checkout strategies must weigh three interacting vectors: (1) the capital and operating cost savings from labor substitution and throughput increases; (2) emergent revenue and experience gains from frictionless, loyalty-linked checkout; and (3) the compliance burden and potential shrinkage exposure introduced by camera, sensor, and computer-vision technologies. Our study quantifies the economic trade-offs and models pragmatic rollout approaches so leadership teams can move from hypothesis to executable plans in 2026.
Waveform Generator Market
What PW Consulting’s Report Delivers — Practical, Decision-Ready Content
This report is designed for executives and practitioners who need actionable guidance rather than academic theory. Core deliverables include:
- Market sizing and forecast framework that links macro demand drivers to store-level economics and capital planning horizons (2026–2032).
- Scenario-based ROI and TCO models that allow CFOs and store operations leads to simulate deployment mixes by store format, labor cost regimes, and shrink profiles.
- Vendor selection matrices and vendor-fit maps that translate functional requirements into procurement-ready scorecards.
- Implementation playbooks: phased rollouts, hybrid checkout models (staffed + assisted + fully self), store footprint optimization, and staff retraining templates.
- Compliance and privacy checklists aligned to recent U.S. state privacy laws and best practices for biometric/vision data governance.
- Security and shrink-mitigation toolkits: loss-prevention controls, audit sampling methods, and integration patterns with payment and loyalty platforms.
- Contract negotiation levers: SaaS vs. perpetual licensing, cloud-service SLAs, hardware refresh cadence, and managed-services options.
The report is intentionally practitioner-focused: each chapter ends with “Decision Points” that a retail leadership team can use to build a 90–180 day action plan. In line with our “trailer” approach, this overview demonstrates the depth of our analysis while preserving the full segmentation tables and vendor scorecards for subscribers who access the complete report.
Competitive Landscape: What Leading Vendors Signal About Next-Gen Checkout
The vendor ecosystem is mature but dynamic. A mix of global incumbent integrators, specialized hardware suppliers, and AI-native startups are shaping product evolution. Key strategic observations for procurement and strategy teams:
- NCR Voyix Corporation continues to leverage cloud-native architecture and modular hardware to offer highly adaptable deployments across store formats. Its recent next‑generation platform emphasizes real-time orchestration and remote patching — attributes that reduce on-site service costs and accelerate feature rollout.
- Diebold Nixdorf is advancing AI-driven shrink reduction and non-barcode recognition through its Vynamic Smart Vision suite. These capabilities speak directly to one of retailers’ primary concerns: reconciling frictionless checkout with loss prevention.
- Toshiba Global Commerce Solutions and Fujitsu remain prominent among large-format grocery and hypermarket deployments, with strong engineering depth around hybrid checkout models and contactless scanning. Fujitsu’s collaborations with local software ecosystems demonstrate the value of joint innovation in markets with specific regulatory or process needs.
- Hardware specialists and component suppliers — including Zebra, Honeywell, and Datalogic — continue to strengthen the platform’s reliability and throughput, while AI-first entrants (for example, Mashgin) are challenging barcode‑centric models with computer-vision approaches that promise reduced checkout time for high-velocity SKUs.
- Regional specialists and system integrators round out the landscape, providing installation, integration, and managed services that are often the decisive factor in multi-store rollouts.
Recent product activity underscores two market directions: convergence (hardware + cloud + AI) and modularization (smaller, tabletop form factors, and compact kiosks for convenience/QSR). For example, Partner Tech’s “Paula” tabletop AI kiosk and NCR Voyix’s modular cloud update illustrate how suppliers are broadening value propositions beyond raw terminal sales to include ongoing services and software monetization.
Regulatory and Operational Headwinds: What Risk Managers Must Know
Self-checkout deployments now live at the intersection of retail operations, cybersecurity, and privacy law. Since 2025, multiple U.S. states implemented new privacy requirements that change how retailers may collect, retain, and analyze camera and sensor data. At the same time, retail-sector privacy maturity lags behind global averages; the cost of a data breach remains material, with industry benchmarks indicating multi‑million-dollar incident averages. Those realities require integration of legal and security teams into procurement, and a shift toward privacy-by-design architectures.
Operationally, shrinkage and theft remain challenging. Some retailers have limited self-checkout in high-shrink locations, even as terminal volumes continue to rise globally. The key risk mitigation approaches we examine include camera analytics tuned for false-positive reduction, hybrid staffing models that pair assisted lanes with supervised self-checkout, and transaction-level risk scoring that triggers lightweight interventions rather than blanket denials.
Strategic Imperatives for 2026 Executive Agendas
Retail leaders should prioritize four strategic moves this year:
- Define a clear checkout portfolio strategy: decide which store formats get fully self, which require assisted models, and where to maintain traditional lanes. This decision should be driven by localized shrink, labor economics, and customer behavioral signals.
- Shift procurement from hardware-centric buying to platform-based contracting: emphasize software features, cloud operations, security SLAs, and managed services that reduce lifecycle risk and total cost of ownership.
- Operationalize privacy and security: adopt data-minimization standards, encryption and retention policies, and clear consent flows for vision- or biometric-enabled systems to align with evolving state laws.
- Invest in change management: staff redeployment, loss-prevention training, and SME centers of excellence that can iterate on checkout rulesets and monitor fraud/susceptibility metrics in near real time.
These imperatives align with the economic trajectory modeled in our forecast: as the market grows at a double-digit clip, first-mover advantages accrue to retailers who can standardize quickly, control risk, and capture the operational upside.
How PW Consulting Helps You Turn Forecasts into Executable Plans
PW Consulting combines market forecasting, vendor benchmarking, and implementation expertise into a single report that is intended to be both strategic and immediately practical. Subscribers receive downloadable TCO models, vendor RFP templates, and region‑agnostic rollout roadmaps that expedite procurement and pilot validation cycles. We also provide executive briefings and scenario workshops to stress-test leadership assumptions under different labor-cost and regulatory scenarios.
For readers seeking the full data set — including detailed segmentation, regional dynamics, and the complete vendor scorecards — the primary report contains those tables and raw models. Our public summary intentionally omits the granular split tables to preserve the commercial value of the full analysis and to encourage a structured engagement that aligns with each retailer’s unique context.
Next Steps for Retail Leaders
If 2026 is to be the year your chain moves from experimentation to scale, the critical work begins with aligning finance, operations, IT, and legal around a single, measurable rollout plan. PW Consulting’s Worldwide Self-Checkout in Retail Market study provides the market context, risk framework, and operational toolkits to turn that alignment into tangible store deployments. Contact PW Consulting to request the full dataset, schedule a tailored briefing, or access the vendor scorecards and procurement templates that will accelerate your program.
For detailed analysis of this topic, please visit the official page: Worldwide Self-Checkout in Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com