

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Phenolic Molding Compound Market Forecast to Reach USD 3,128.18 Million by 2032

PW Consulting Releases Worldwide Phenolic Molding Compound Market — Strategic Insights to Guide 2026 Decisions
PW Consulting today publishes a forward-looking brief derived from our full Worldwide Phenolic Molding Compound (PMC) Market report. As an industry that bridges traditional thermoset chemistry and high-performance applications, the PMC market is returning to a pathway of steady expansion: our modeled market reached approximately USD 2.25 billion in 2025 and, under the baseline scenario, is projected to grow at a compound annual growth rate (CAGR) of 4.85% through 2032, reaching just over USD 3.1 billion by the end of the forecast horizon. This release highlights the report’s strategic utility for executive teams planning capital allocation, supply-chain resilience initiatives, product roadmaps, and M&A activity in 2026 — while reserving detailed segment-level datapoints for the full report.
Worldwide Hadoop Operation Service Market
Executive snapshot: why phenolic molding compounds matter in 2026
-
Resilience and steady expansion: After a near-term cyclical trough in 2024, demand dynamics in 2025 show recovery supported by industrial retooling and sustained requirements from electrical & electronics and automotive subsegments. The mid-single-digit CAGR we project reflects a market that is neither hyper-growth nor mature stagnation; rather, it rewards selective investment and operational agility.
Worldwide Hard Contact Lens Market -
Feedstock sensitivity: Phenolic resin production remains sensitive to upstream phenol and cumene dynamics. Regional feedstock price volatility is creating divergent margin pressures and arbitrage opportunities that will shape sourcing and localization decisions in 2026.
3D SLAM Autonomous Driving Solution Market -
Certification and reliability requirements: Continued emphasis on electrical safety and performance standards sustains demand for UL-certified PMCs and drives product specification complexity for OEMs and tier suppliers.
Market dynamics to watch (Q1–Q4 2026)
-
Regional feedstock variance: Phenol pricing shows meaningful regional dispersion entering 2026. In Northeast Asia phenol averaged around USD 1.01/kg in March 2026 (an increase of ~8.6% versus December 2025), reflecting firm regional resin demand and tighter cumene feedstock economics. Europe exhibited a softer track with phenol near USD 1.00/kg in March 2026 (roughly a 3.8% decline from December), influenced by softer local resin demand and competitive import flows. North America’s phenol market was comparatively stable at about USD 1.18/kg in March 2026, down marginally from December.
-
Certification as a differentiator: UL certification remains an active gating factor for many electrical applications, covering flame performance, HWI/HAI behavior and thermal indexing. Manufacturers that maintain or pursue these credentials will enjoy clearer access to higher-specification OEM programs.
-
Competitive moves: Leading compounders are combining capacity plays with product innovation. Recent examples include Sumitomo Bakelite’s capacity expansion in Nantong (commissioned in 2024) and a March 2026 new-series launch focused on high-adhesion phenolic resins targeted for advanced compound formulations — a reminder that scale and product breadth both matter.
What’s inside the full PW Consulting report (practical, actionable content)
-
Quantitative market model — top-down and bottom-up projections across a multi-scenario framework (baseline, downside, and accelerated-adoption cases) with downloadable model files and sensitivity knobs for raw-material and demand shocks.
-
Supply-demand mapping — manufacturing topology, regional capacity flows, typical lead times and cost components across the value chain (feedstock → resin → compound → molded part).
-
Price and margin stress-testing — scenario runs showing pass-through potential under several phenol and energy price trajectories.
-
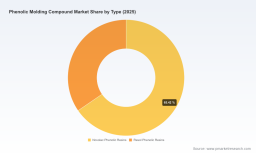
Segmentation frameworks — demand by type and application with qualitative drivers and an overlay of regulatory and certification requirements. (Note: detailed numeric splits at the region/application/type level are available in the full dataset.)
-
Competitive benchmark and capability matrix — strategic profiles for global and regional players, mapped by technology, capacity footprint, product specs, and go-to-market channels.
-
Operational playbooks — supply-chain hedging templates, near-term capacity deployment checklists, and product-launch playbooks designed for both compounders and OEM material engineers.
-
M&A and partnership screening tool — a short-listing methodology, valuation heuristics tied to capacity and technology premium, and red-flag diagnostics for integration risk.
-
Risk register and mitigation measures — from raw-material shocks to regulatory shifts affecting flame retardant and electrical safety listings.
Strategic takeaways for 2026 corporate planners
-
Embed feedstock scenarios into every commercial decision: Given the observed regional phenol price dispersion and the sensitivity of margins to raw-material swings, procurement teams should run at least three phenol-price scenarios when evaluating multi-year supply agreements or localized capacity builds.
-
Prioritize certification roadmaps for electrical applications: UL and equivalent attestations continue to be entry requirements for high-margin, specification-driven programs. Investment in certification and test-lab partnerships unlocks premium OEM business.
-
Adopt a hybrid localization strategy: Use regional production to manage lead times and mitigate shipping-cost volatility where feedstock economics permit, and use centralized production plus inventory buffering for commodity-grade offerings.
-
Differentiate through formulation and value-added services: High-adhesion, heat-resistant, and filler-optimized compounds gain traction with EV, industrial, and aerospace specifications. Technical service capabilities that shorten qualification cycles are a commercial advantage.
-
Use M&A selectively to access technology gaps: The market remains moderately fragmented; transactions that secure capacity plus proprietary formulations or certification pipelines are likely to be value-accretive.
Competitive landscape — who matters and why
The PMC space blends multinational incumbents with regionally specialized compounders. Market concentration is modest: the top three players account for roughly one quarter of global market share, while the top five collectively approach around 39% — a structure that supports both scale-driven players and nimble specialists. Key company archetypes in the competitive set include:
-
Sumitomo Bakelite Co., Ltd. (Tokyo) — A vertically integrated player with global production footprint and a strong presence in glass-fiber-reinforced and filler-optimized compounds. Recent strategic moves include commissioning a Nantong plant (2024) to expand capacity and launching a high-adhesion phenolic resin line in March 2026, signaling continued investment in both scale and formulation innovation.
-
PLENCO (Plastics Engineering Company, USA) — A specialist in novolac and resol chemistries, delivering dimensional stability and thermal/electrical performance across compression, transfer, and injection molding processes.
-
Bakelite Synthetics (Bakelite, USA/global sites) — Focused on high-quality thermoset solutions with strong brand recognition among consumer, electrical and industrial customers.
-
Chang Chun Plastics (Taiwan) — Provider of customer-specific heat-hardening resin compounds for electrical and automotive applications with an emphasis on configurable formulations.
-
Resinoid Engineering (USA) — Known for custom compounding and high-temperature phenolic materials used in aftermarket and demanding industrial applications.
-
Shengquan Group (China) — A major resin supplier with scale advantages in phenolic resin production, enabling competitive raw-material positioning for compounders.
-
Kaihua Ruida (Zhejiang, China) — Manufacturer of UL-recognized phenolic molding compounds and Bakelite powders for appliance, construction and automotive end markets.
For OEMs and investors, the takeaway is clear: scale and product breadth remain valuable, but targeted technical differentiation and certification-readiness create defensible commercial corridors.
Raw-material and regulatory signals — immediate implications
-
Price transmission and margin management: Regional phenol price spreads in early 2026 are not merely academic — they drive margins on formulated compounds and influence decisions on where to site incremental compound capacity or buffer inventories.
-
Regulatory and standards continuity: The persistence of UL certification regimes for flame, HWI/HAI and RTI metrics means that redesign cycles for electrical components must account for test-, retest- and qualification windows when switching materials or suppliers.
How procurement, R&D, and corporate development teams should use this analysis in 2026
-
Procurement: Use the report’s live model to test multi-year off-take pricing and to design indexation clauses tied to phenol and energy inputs.
-
R&D and product engineering: Leverage the formulation benchmarking and certification matrix when prioritizing material swaps for thermal and electrical performance upgrades.
-
Corporate development: Apply the M&A screening tool and valuation heuristics to prioritize targets that provide immediate route-to-market in high-spec segments or that close key technical gaps.
-
Operations: Integrate supply-chain mapping and stress tests into contingency planning for feedstock shocks and logistics disruptions, especially for export-dependent facilities.
Next steps — where to access the full intelligence
This briefing is a strategic preview designed to surface the critical decisions facing leaders in the phenolic molding compound value chain in 2026. The full PW Consulting Worldwide Phenolic Molding Compound Market report contains the granular regional and application-level data, interactive market models, company profiles, proprietary scenario outputs and execution-ready playbooks referenced above. To obtain the full report, model files, and advisory support for applying these findings to your specific business case, please contact PW Consulting or visit our publications page to request access to the complete dataset and client-only briefing sessions.
PW Consulting remains available to support scenario workshops, supplier diligence, and post-acquisition integration planning informed by the report’s quantitative and qualitative findings.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com