

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Skin Care Products Tubes Market Poised to Reach USD 26,825.63 Million by 2032 on a 5.45% CAGR

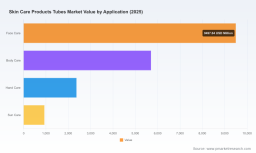
Worldwide Skin Care Products Tubes Market: Strategic Outlook for 2026
As companies finalize budgets and roadmaps for 2026, our latest PW Consulting market brief — the Worldwide Skin Care Products Tubes Market — delivers the actionable market architecture leaders need to convert uncertainty into advantage. Built on a rigorous 2020–2025 historical base and projecting through 2032, the study synthesizes macro trajectory, cost and regulatory shocks, competitor playbooks, and pragmatic go‑to‑market scenarios. The headline: the global tubes market is poised to expand at a mid-single‑digit compound annual growth rate (CAGR) of 5.45% and continues to scale in nominal terms, providing both margin recovery opportunities and structural disruption risks for suppliers, brand owners and investors alike.
Worldwide Embalming Fluid Market
Why this report matters for 2026 decisions
-
Timing and framing: 2026 is the inflection year when sustainability mandates, raw material volatility and shifting consumer preferences converge. Executives who lock in strategy early — balancing near‑term operational resilience with medium‑term circularity investments — will capture disproportionate share when the market re‑rates.
Spool Position Sensor Market -
Grounded forecasting: our base year is 2025, with a transparent forecast through 2032. The dataset gives CFOs and corporate strategists a defensible revenue run‑rate and scenario sensitivity to cost shocks and policy changes.
Wound Stator Shell for Electric Motors Market -
Decision focus: this is not a descriptive catalogue. The brief translates trends into decision levers — procurement hedging strategies, retrofit vs. replace product roadmaps, regional footprint choices and M&A playbooks — calibrated to real commercial constraints.
Core takeaways — high‑impact strategic signals
-
Resilience first: volatile resin markets and uneven tariff regimes are compressing unit economics in the near term. Our modelling shows that a combination of flexible sourcing, indexed contracts and selective pass‑through pricing preserves margins without sacrificing share.
-
Sustainability is now a hard constraint: regulatory timelines (for example, EU recycled content mandates) and escalating retailer requirements mean product teams must prioritize mono‑material designs and validated recycling pathways. Delaying technical validation risks market access and higher remediation costs after 2027.
-
Premiumization meets functionality: premium skincare continues to demand airless and high‑barrier systems. This opens a two‑track value creation path — premium converters and system integrators can extract higher ASPs, while low‑cost flexible suppliers must compete on efficiency and compliance.
-
Fragmented supplier base — opportunity for consolidation: the market displays modest concentration, with leading manufacturers holding a meaningful but not dominant share. This creates room for targeted M&A to acquire scale in strategic geographies or capabilities (e.g., airless systems, mono‑material tooling).
What’s in the PW Consulting report — a practitioner’s toolkit
-
Market sizing and validated forecast (2026–2032) with scenario overlays that test raw material spikes, tariff escalations and accelerated sustainability adoption.
-
Segment architecture and buyer archetypes: product families, material choices, application patterns and typical buyer negotiation logic — translated into playbooks for converters and brand procurement.
-
Supply chain and cost build‑up models: from resin and barrier films through conversion, cap/closure systems and finished goods logistics — including a sensitivity engine that quantifies margin impact under plausible HDPE and film price swings.
-
Regulatory and policy matrix: country‑level requirements, upcoming compliance milestones, and a prioritized list of certification or testing actions that materially affect time‑to‑market.
-
Competitive landscaping with deep profiles: operating models, R&D roadmaps, recent launches, manufacturing footprints and strategic intents for the leading suppliers in the space.
-
Deal and partnership playbooks: criteria and valuation heuristics for tuck‑ins, capability buys and JV structures tailored to converters, material suppliers and brand owners.
-
Commercial scorecards and procurement templates: negotiation levers, KPI dashboards and a supplier risk rubric to operationalize the study’s insights in 90‑day sprints.
Competitive landscape — who to watch
The skin care tubes ecosystem comprises global converters, specialty system providers and regional custom houses. Key players combine scale manufacturing with increasingly sophisticated sustainability offers and dispensing systems. The report examines the strategies and operational plays of market leaders, including:
-
Albéa Group (Gennevilliers, France): a global leader across laminated, plastic and aluminum tubes; notable for accelerating mono‑material tube innovations and recyclable snap‑top designs introduced in late 2024.
-
Silgan Holdings Inc. (Stamford, CT, USA): through its dispensing division, a major provider of plastic tubes and precision dispensing systems tailored to skincare applications.
-
AptarGroup Inc. (Crystal Lake, IL, USA): focused on airless and pump architectures for clean beauty brands — investing in trade‑show visibility and application engineering to capture premium segments.
-
Amcor plc (Zurich, Switzerland): a flexible packaging giant emphasizing recyclable, high‑barrier materials suitable for sensitive formulations.
-
Berry Global Group Inc. (Evansville, IN, USA): offers both rigid and flexible formats with an increasing emphasis on weight reduction and sustainability certification.
-
Huhtamäki Oyj (Espoo, Finland): known for laminate and mono‑material tube innovations aimed at recyclability and circularity.
-
Virospack S.A. (Barcelona, Spain): a specialty provider of premium airless systems tailored to high‑end skincare brands.
-
Intrapac International Pty Ltd (Keysborough, Australia): a regional custom supplier with capabilities to serve APAC formulas and rapid prototyping needs.
Each profile in the report includes capability matrices, recent product launches, capital intensity estimates and acquisition targets — information that informs realistic competitive moves in 2026 without relying on conjecture.
Recent developments and tactical implications
-
Product launches and system innovations: several leading suppliers intensified their activity in 2024–2025 with recyclable snap‑top tubes and new airless platforms. These moves accelerate the adoption of mono‑material solutions and force legacy packaging to justify its environmental credentials.
-
Sustainability certifications: select manufacturers secured third‑party verification in 2024, creating short‑term commercial leverage with global beauty brands seeking validated supplier partners.
-
Raw material and trade signals: European polymer prices and persistent tariff regimes in certain markets are altering landed costs. Brands and converters must model these inputs explicitly in pricing and sourcing decisions.
Market dynamics to monitor in 2026
-
Cost volatility: our scenario analysis models a range of HDPE cost pathways and shows that procurement agility (index‑linked contracts, regional sourcing hubs) materially outperforms static cost models in protecting gross margins.
-
Regulatory milestones: regulatory requirements for recycled content and packaging waste management will compress the window for compliance investments; early movers that validate mono‑material recycling pathways gain both cost and reputational advantage.
-
Commercial premiumization: airless and premium dispensing systems sustain higher average selling prices for converters that can deliver technical assurance; this segment will remain attractive for strategic investments.
-
Trade friction and reshoring: tariffs and logistics friction are prompting selective regionalization of capacity for sensitive markets — a strategic decision for companies weighing capex versus variable cost exposure.
How to use this briefing in 90–180 day plans
-
Procurement: implement a two‑lane sourcing approach — lock minimum volume coverage with diversified suppliers while piloting mono‑material alternatives with preferred converters.
-
R&D and product: prioritize rapid technical verification of recyclable tube formats for top SKUs and allocate a small, protected test budget to airless integrations for premium launches.
-
M&A and partnerships: screen targets for capability gaps — look for converters with proprietary airless systems, tooling capacity in strategic geographies, or validated recyclability claims.
-
Regulatory readiness: establish a compliance sprint team to map product SKUs against jurisdictional mandates and certification timelines; this reduces rework and market withdrawal risk.
Closing — the strategic edge for 2026
2026 is not a year to “wait and see.” It will be a year of crystallization: policy deadlines, cost pressures and consumer demand will force decisions that have multi‑year revenue and margin consequences. PW Consulting’s Worldwide Skin Care Products Tubes Market report gives executives the mixed quantitative and tactical intelligence required to make those decisions with conviction: validated market sizing, sensitivity testing, supplier scorecards and direct playbooks for procurement, R&D and M&A.
We deliberately present depth without disclosing every cell in the dataset here. For the full forecast tables, granular segmentation, company valuation heuristics and the downloadable financial model that you can plug into your 2026 planning process, please access the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care Products Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com