

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Antibody Fragments Market Set to Reach USD 22,798 Million by 2032, Driven by a 9.6% CAGR

Worldwide Antibody Fragments Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting — Executive Brief
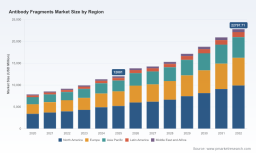
PW Consulting today releases the official executive summary of our Worldwide Antibody Fragments Market report, a practitioner-oriented intelligence product designed to inform and de-risk corporate strategy in 2026. The antibody fragments sector — spanning Fab, scFv and single-domain (VHH/nanobody) formats — is moving from niche innovation to scaled commercial relevance. Our market modeling shows the industry reaching a base-year market size of approximately USD 12,001 million in 2025 with a projected compound annual growth rate (CAGR) of 9.6% across the 2026–2032 forecast window, driving to a multi‑billion dollar market at the end of the period. This trajectory creates a distinct set of near-term tactical choices for drug developers, CDMOs, investors and payers.
Irrigation Supervisory Controller Market
Why this report matters for 2026 planning
- Actionable foresight: The report translates raw growth into decision-ready hypotheses — where to allocate R&D dollars, when to hedge manufacturing risk, and how to structure partnerships to preserve upside while limiting capital intensity.
- Risk-to-reward clarity: Antibody fragments offer differentiated product attributes (improved tissue penetration, alternative half‑life engineering) but with unique manufacturing and economics that materially affect margin and pricing strategies. Our models quantify those trade-offs and show how small shifts in COGS or reimbursement rates change project-level IRR.
- Competitive posture: We map incumbent and emerging players across platform, clinical pipeline and manufacturing capabilities — providing a concise playbook for M&A, licensing, or white‑label supply decisions in 2026.
Key growth drivers and market dynamics
Demand is being pulled by multiple vectors. Therapeutic programs continue to dominate development activity, supported by diagnostics and an expanding R&D services market. Advances in single-domain technologies and strategic partnerships are accelerating clinical throughput and industrialization. At the same time, manufacturing complexity and reimbursement dynamics introduce critical decision points:
Worldwide Microwave Power Supply Market
- Manufacturing complexity: Unlike full monoclonal antibodies, many fragment formats lack an Fc domain and therefore cannot leverage Protein A affinity capture. This forces multi-step purification (for example ion exchange and hydrophobic interaction chromatography), which our sector analysis shows can raise downstream manufacturing costs by as much as 60% versus conventional mAbs in equivalent scale scenarios. That differential changes calculus for insourcing vs. outsourcing and for the selection of formats in cost-sensitive indications.
- Production platform trade-offs: Microbial expression systems (E. coli, Pichia pastoris) have become a competitive advantage for scFv and nanobody formats, delivering high yields in optimized processes (reported up to ~150 mg/L in fed‑batch runs in the highest‑performing cases). However, process scalability, product quality attributes and regulatory pathways still favor mammalian systems for certain complex constructs.
- Half-life engineering and economics: PEGylation, albumin-binding moieties, or Fc fusion strategies extend half-life but materially increase COGS — often doubling or tripling costs — and therefore require careful pricing and indication selection to preserve margins.
- Regulatory and reimbursement constraints: Fragment therapeutics are assessed under the same rigorous preclinical and clinical frameworks as other biologics. Payer acceptance hinges on demonstrable real-world benefit and, for many indications, cost-effectiveness versus established mAbs or small molecules.
What PW Consulting’s report contains — practical tools for 2026 action
This research is built to be used, not just read. Highlights of the operational content include:
Worldwide IT Spending in Automotive Market
- Methodology and transparent modeling: Full disclosure of assumptions, sensitivity analyses and scenario modules so executives can re-run forecasts with their internal inputs.
- Market sizing and growth decomposition: Top-down and bottom-up frameworks that reconcile historical uptake (2020–2025) with forecasted adoption curves (2026–2032), including scenario runs for accelerated clinical success or slower reimbursement uptake.
- Technology and pipeline atlas: A mapped view of clinical programs and platform maturity across Fab, scFv and VHH/nanobody formats, annotated with development risk and commercial opportunity scores.
- Manufacturing economics toolkit: A modular cost‑of‑goods model that contrasts microbial vs. mammalian production, purification pathways, and the incremental cost impact of half-life extension technologies.
- Commercial playbooks: Guidance on go-to-market, pricing strategy, tendering, and payer engagement tailored to fragments’ product profiles and indication-specific value propositions.
- Partnering and deal flow intelligence: A curated database of recent partnerships, platform licensing, and CDMO capacity investments — designed to accelerate diligence and term‑sheet drafting.
- 90‑day implementation plans: Fast-start checklists for business development, CMC due diligence, and regulatory engagement to translate strategy into pipeline progress within a quarter.
Competitive landscape — what to watch in 2026
The market is characterized by major pharmaceutical groups advancing proprietary programs alongside specialized biomanufacturers and service providers offering bespoke production and platform capabilities. Key dynamics include platform consolidation, selective vertical integration, and differentiated route-to-market strategies:
- Large integrated pharmas (e.g., long-standing biologics leaders) continue to deploy antibody fragment strategies as part of diversified portfolios. Leaders with early commercial fragment products have a visible advantage in regulatory know-how and channel access for ophthalmic, autoimmune and oncology indications.
- Platform champions — companies that have invested in dedicated single-domain or Fab platforms — are working to commercialize the technology’s advantages (tissue penetration, manufacturability at small scale) while scaling CMC support to match rising clinical loads.
- Specialist service providers and CMOs are gaining share by offering end‑to‑end custom production (from construct optimization to GMP supply) and by mastering the non-Protein A purification sequences that fragments require. These providers reduce time‑to-clinic risk but compete on capacity and regulatory track record.
Notable corporate positions and recent moves illustrate these trends. Established innovators have clinically proven fragment therapeutics — providing a commercial blueprint and real‑world data — while specialty platform owners continue to demonstrate technology differentiation. In 2025 and early 2026 we have tracked several meaningful developments: a major platform advance by a leader in nanobody technologies, an expansion of partnerships by a prolific discovery partner, and a peer-reviewed industrialization review that consolidates decades of VHH production learnings. These signals indicate momentum across both proprietary pipeline and service-provider ecosystems.
Portfolio and partnering implications for executives
- Portfolio prioritization: Use our decision matrix to compare incremental revenue potential against incremental COGS and development risk. Fragments provide attractive clinical differentiation for tissue‑targeted and CNS applications, but only certain indications sustain premium pricing sufficient to cover higher COGS from complex purification or half-life engineering.
- Manufacturing strategy: For companies with multiple fragment programs, a hybrid approach — contracting early clinical supply to niche CDMOs and evaluating in‑house scale only for proven late‑stage assets — often minimizes capital burden while preserving strategic optionality.
- M&A and alliances: Buyers should look for targets with proven platform scalability or CDMOs with validated fragment workflows. Sellers should package clinical datasets, validated CMC routes, and payer‑level health economic models to maximize valuation.
- Regulatory and payer engagement: Early and active dialogue with regulatory bodies and payers will improve labeling outcomes and reimbursement positioning; value dossiers must explicitly address fragment-specific benefits and COGS implications of half‑life extension.
Market structure and concentration — what it means
The market shows a meaningful degree of concentration among leading players, creating advantages for incumbents with established clinical assets and manufacturing networks. For challengers, there is space to succeed via platform differentiation, superior CDMO service, or targeted indication strategies where fragment attributes deliver unambiguous clinical value.
Concluding guidance — five tactical moves for 2026
- Run a format-selection stress test on your pipeline: quantify net present value under alternative manufacturing and reimbursement scenarios.
- Secure flexible CMO capacity for first‑in‑human and Phase II supply; defer heavy capital expenditure until clinical inflection points are achieved.
- Negotiate option‑style partnerships with platform owners to manage upside while limiting near‑term cash outlays.
- Invest in payer evidence generation early for high-cost half‑life extension strategies; neutralize COGS objections with clear real‑world benefit plans.
- Monitor platform industrialization milestones and partnership announcements: these are leading indicators of where scale will materialize and margins can normalize.
Next steps — access the full intelligence
PW Consulting’s full report includes the detailed segmentation, company scorecards, financial models and a downloadable scenario tool that underpins the analyses summarized here. This press brief follows the “trailer” principle: it outlines the strategic narrative and modeling framework while reserving granular segment-level data, regional splits and firm-level revenue breakdowns for the complete report. For immediate access to the full dataset, methodologies and proprietary company dossiers to inform 2026 decisions, please visit the PW Consulting report page or contact our industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com