

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Worldwide CNS Stimulants Market Poised for a 6.25% CAGR Through 2032
By pmarketresearch, 2026-08-12
Strategic Preview: Worldwide CNS Stimulants Market — Preparing Pharma Leadership for 2026
PW Consulting’s latest market study on Worldwide Central Nervous System (CNS) Stimulants synthesizes market-scale dynamics, regulatory inflection points and competitive moves into an actionable roadmap for executive decision-making in 2026. Anchored on a 2025 base year and projecting through 2032, our model shows the global CNS stimulants market expanding at a compound annual growth rate (CAGR) of 6.25% (USD, revenue unit: Million). The market has grown from the mid‑2020s through 2025 and, under our base scenario, continues a steady expansion into 2032—driven by persistent ADHD demand, therapeutic diversification, and formulation-driven lifecycle management.
Worldwide Brassinolide Market
Why this report matters for 2026 strategy
-
Decisions in 2026 must account for a market that is simultaneously mature and dynamically reshaping: incumbent brand equity and extensive generic penetration coexist with product-level innovation (delivery systems, prodrugs, delayed‑release platforms) and renewed regulatory scrutiny. Our analysis translates these tensions into strategic imperatives for pipeline prioritization, manufacturing investments, and commercial go‑to‑market sequencing.
Worldwide Cryptocurrency Software Market -
Regulatory and supply constraints affecting Schedule II stimulants are not one‑off disruptions but structural variables that will influence capacity planning, contract manufacturing relationships and geographic launch priorities. The report quantifies the likely market impact of these variables under alternative regulatory and supply scenarios, enabling financial teams to stress‑test forecasts and procurement groups to prioritize resilience investments.
Worldwide Dental Fluoride Varnish Market -
For commercial leadership, the report benchmarks competitive positioning across originator, authorized‑generic and pure‑play generic players, and provides playbooks for formulary negotiations, specialty channel deployment and lifecycle extensions that maintain profitability in a pricing‑sensitive environment.
What the topline numbers tell you (and what they don’t)
PW Consulting’s market model provides year‑by‑year revenue projections from 2023 through 2032 (USD Million). It captures recent acceleration into 2025 and a projected continuance of growth into 2032 consistent with the 6.25% CAGR. These topline trajectories reflect demand persistence for core ADHD and narcolepsy indications, incremental uptake of new formulations and steady replacement/renewal cycles in chronic use populations.
As a “trailer” for our proprietary dataset, we surface the macro growth trajectory to inform board‑level resource allocation without publishing the granular regional, drug‑type and indication splits contained in the full report. Clients who need segment‑level revenue, market share tables, or the scenario outputs that translate quota shifts, label changes and supply interruptions into P&L impacts should consult the complete research pack.
Regulatory and supply dynamics shaping 2026 choices
-
Heightened regulatory focus. Recent regulatory actions have materially altered product risk/benefit communication: in mid‑2025, regulators mandated expanded pediatric warnings for extended‑release amphetamine and methylphenidate products. That label evolution directly affects pediatric prescribing patterns and the commercial case for pediatric label expansion programs. Teams must update clinical development and pharmacovigilance strategies to accommodate heightened safety surveillance and potential labeling constraints.
-
Controlled‑substance production quotas. Aggregate production quotas have been adjusted upward in response to manufacturer requests, reflecting underlying demand and supply negotiations with regulators. These quota dynamics become strategic levers—especially for originators and large generics—that can be used to smooth supply or to secure short‑term competitive advantage. Our scenario module maps quota outcomes to market availability and price volatility under multiple regulatory response assumptions.
-
Persistent API and finished‑product constraints. Global API concentration and downstream manufacturing bottlenecks continue to produce intermittent shortages, notably among immediate‑release amphetamine salts. The 2026 environment therefore favors companies with diversified sourcing, redundant manufacturing footprints, or long‑dated supply agreements. Manufacturers should prioritize capital allocation to strategic capacity, and payers/pharmacies should assess contingency protocols to avoid therapy disruption.
-
Quality assurance signals. Quality surveillance outcomes matter: publicly reported FDA quality testing in early 2026 confirmed acceptable results for certain extended‑release methylphenidate products from leading generics manufacturers. This kind of verification reduces short‑term market risk for specific suppliers and can influence procurement choices among health systems and group purchasing organizations.
Competitive landscape: reading the signal from established and emerging players
The CNS stimulants category is populated by a spectrum of players: multinational originators with branded franchises, large generic manufacturers with scale supply capabilities, and smaller firms focused on formulation innovation and niche delivery technologies. Our competitive assessment highlights several strategic archetypes present in the marketplace:
-
Originator franchises leveraging formulation differentiation: Major multinational companies continue to protect and extend branded assets through extended‑release platforms, prodrug approaches and time‑of‑day targeting. These plays are supported by strong regulatory and commercial infrastructures and permit premium pricing in managed markets with favorable reimbursement.
-
Scale generics and contract manufacturers: Large generic manufacturers and specialty producers remain the backbone of volume supply, particularly in mature markets. Their strategic focus is on manufacturing efficiency, portfolio breadth and rapid biosimilar‑style launch readiness when exclusivities expire. Manufacturing quality verification events in 2026 are a positive signal for these players’ market access.
-
Formulation specialists and delivery innovators: Smaller, agile companies are capturing value through novel delivery systems (liquid formulations, transdermal patches, delayed‑release evening dosing) and prodrug technologies that modify abuse potential and dosing cadence. These capabilities are attractive to payers when they reduce administration burden or improve adherence.
Beyond pure therapeutic competition, the category is shaped by shifting payer dynamics and regulatory engagement. Our competitor dossiers evaluate commercial strengths, manufacturing footprints, patent cliffs, partnership activity and clinical pipelines for the leading firms in the space. For clients considering collaborations, M&A or licensing, those dossiers create an actionable shortlist calibrated to 2026 market realities.
Strategic implications and playbook for 2026 decision‑makers
PW Consulting’s research distills market forces into a compact strategic playbook tailored for executive teams preparing budgets, capital plans and product roadmaps in 2026. Key recommendations include:
-
Adopt scenario‑based demand planning that integrates quota variability and label changes. Build a matrix of likely regulatory outcomes and tie these to procurement, manufacturing ramp‑up schedules and launch timing decisions.
-
Invest selectively in supply chain resilience: prioritize API diversification, capacity redundancy in finished‑dose production, and long‑term supply agreements with validated manufacturers to reduce exposure to episodic shortages.
-
Prioritize formulation differentiation that addresses payer and end‑user pain points: convenience, adherence, abuse‑deterrent/prodrug designs and pediatric suitability will command attention from formulary committees and prescribers.
-
Prepare reimbursement rationales mapped to evolving pricing paradigms. With pricing models and benchmarking pilot programs under discussion in major markets, companies must document value through real‑world evidence, pharmacoeconomic models and targeted outcomes studies.
-
Leverage regulatory intelligence as a competitive asset. Proactive engagement with regulators on labeling language, pediatric risk mitigation, and post‑marketing surveillance programs can reduce time‑to‑market and improve acceptance of new formulations.
-
Shape M&A and partnership strategies around asymmetric advantages: originators seeking manufacturing scale should prioritize targets with validated GMP facilities; smaller developers with differentiated delivery systems should seek partners offering payer access and commercialization infrastructure.
Report contents — practical deliverables you can use in 2026
The full PW Consulting report is designed for operational use by commercial, regulatory, R&D and M&A teams. Key deliverables include:
-
A transparent market model (2020–2032) with downloadable spreadsheets and scenario toggles for regulatory, supply and reimbursement shocks.
-
Region‑ and indication‑level forecasts (with sensitivity bands) and a methodology appendix describing data sources and assumptions.
-
Proprietary supplier risk heatmaps that identify API concentration, single‑site dependencies and likely shortage triggers.
-
Company profiles and comparative scorecards covering manufacturing quality, commercial reach, pipeline differentiation and likely post‑patent competition timing.
-
Actionable go‑to‑market playbooks for branded launches, authorized generics, and generic‑only market entry strategies.
-
Regulatory tracker and policy impact assessments, including quantified P&L impacts for plausible labeling and quota scenarios.
Conclusion — preparing to act, not just to observe
As the CNS stimulants market moves into 2026, executives face a landscape of predictable growth but compound uncertainty: regulatory tightening, quota mechanics, supply chain fragility and evolving reimbursement frameworks. PW Consulting’s study converts that complexity into a structured set of choices—prioritizing resilience, formulation innovation and payer‑facing evidence generation.
Our preview has revealed the macro growth path and the strategic contours leaders must consider. For stakeholders who require the granular segmentation, regional breakdowns, and the full suite of model outputs that drive transaction and operational decisions, the complete report provides the necessary depth and downloadable tools to act with confidence. PW Consulting stands ready to partner on bespoke scenario analysis, M&A diligence and implementation roadmaps tailored to your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Adult Ventricular Assist Device Market to Grow at a 5.81% CAGR from 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Adult Ventricular Assist Device Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market intelligence briefing frames the adult ventricular assist device (VAD) landscape at a pivotal inflection point. Our analysis projects continuing expansion from an estimated global market size of USD 1,845.5 Million in 2025 to roughly USD 1,941.1 Million in 2026, with a compound annual growth rate (CAGR) of 5.81% through our 2026–2032 forecast horizon and a 2032 market projection of approximately USD 2,742.1 Million. These headline metrics underscore steady, clinically driven growth against a backdrop of regulatory tightening, concentrated competition, and accelerating technology transitions — factors that will determine winners and losers in corporate strategies executed in 2026.
Worldwide Money Insurance Market
Key findings at a glance
-
Resilient market growth: The adult VAD market has expanded materially over the last half‑decade and, per our base case, will continue to grow at a mid‑single digit CAGR out to 2032. This growth is powered by broader adoption of destination therapy, incremental clinical evidence supporting newer centrifugal technologies, and incremental reimbursement alignment in developed markets.
Worldwide Tubing Connections Market -
High concentration, high stakes: Market concentration is pronounced — the top three companies control the overwhelming majority of market revenue, and the top five exceed 90%. This concentration compresses commoditization risk while magnifying the strategic impact of clinical data, recall risk, and regulatory approvals.
Worldwide Melaleuca Oil Market -
Clinical evidence moves markets: Long‑term trial results and real‑world registries are the single most influential determinant of device uptake and payer acceptance. Recent five‑year data for a leading centrifugal LVAD have materially reinforced its commercial position; conversely, device recalls and advisories have precipitated rapid share shifts and created white‑space opportunities for agile competitors.
-
Regulatory and reimbursement complexity: VADs remain Class III devices in the U.S., with PMA processes and evolving European MDR requirements shaping time‑to‑market and post‑market burdens. Simultaneously, recent updates to hospital billing codes and DRG payments in key markets are modifying provider economics and center‑level adoption incentives.
-
Adjacencies and alternatives: Total artificial hearts, percutaneous temporary devices, and improvements in heart failure medical therapy are creating nuanced competitive and complementary dynamics. For incumbent manufacturers the strategic question is whether to focus on incremental LVAD improvements, adjacent device platforms, or service‑led care pathways.
Why this report matters for 2026 strategic decisions
-
M&A screening and diligence: With a highly concentrated market and clear regulatory hurdles, valuation asymmetries will arise from differential clinical evidence and regulatory status. Our report provides a triage framework for identifying targets where regulatory runway, clinical data, or service economics can be de‑risked within a two‑year M&A horizon.
-
Product portfolio prioritization: R&D budgets must be triaged between incremental device improvements (e.g., hemocompatibility, energy efficiency), controller ecosystems, and adjacent platforms such as total artificial hearts. We map the clinical and commercial returns across these investment choices under multiple adoption scenarios.
-
Market access and reimbursement strategy: Payers and hospitals are tightening adoption criteria. Our payer models simulate the impact of specific DRG and CPT updates on provider margins and forecast likely shifts in center of excellence behavior — essential inputs when negotiating hospital contracts or piloting new reimbursement pathways.
-
Commercial strategy and channel design: The capital‑intensive, service‑heavy nature of VAD programs rewards sophisticated field playbooks. The report prescribes sales coverage models, training and servicing KPIs, and partnership archetypes (e.g., implant center alliances, leasing/consignment models) that improve conversion and lifetime value.
-
Clinical development planning: Trial design choices (endpoint selection, non‑inferiority margins, registry‑augmented approaches) materially shift time‑to‑label and market uptake. We provide protocol optimization checklists that reconcile regulatory expectations with real‑world adoption drivers.
Competitive dynamics — what to watch in 2026
-
Abbott Laboratories — execution through evidence: Abbott’s centrifugal LVAD platform remains a commercial anchor for organizations seeking durable destination therapy options. Recent multi‑year trial results showing meaningful survival and neurological outcomes have fortified its commercial position; for competitors, matching or exceeding that evidence is a prerequisite for displacement.
-
Medtronic — recall legacy and strategic choices: The recall and clinical advisory surrounding one of Medtronic’s centrifugal systems have constrained new implantations in several markets and reshaped the competitive field. Ongoing support obligations and liability considerations continue to influence hospital procurement decisions and present strategic openings for other manufacturers.
-
LivaNova — regional thrust and next‑generation centrifugal entrants: CE Mark progress and commercial launches across Europe illustrate a viable pathway to scale for newer centrifugal designs. For multinational players, timing and sequencing of regulatory clearances will dictate when and where to press advantage or defend ground.
-
Berlin Heart and Syncardia — niche and adjunct strategies: External pneumatic devices and total artificial heart platforms serve important clinical niches — specifically in biventricular failure or implant‑ineligible patients. These therapies underscore the importance of service, specialized training, and referral network stewardship rather than pure product competition.
-
Implication: consolidation and co‑opetition: Expect continued consolidation among devices, supply chain partners, and service providers. Strategic partnerships (manufacturing, digital health, consumables management) will be decisive for scaling programs and extracting service revenue beyond the implant.
Regulatory and reimbursement dynamics shaping 2026 strategies
-
Regulation: Adult VADs remain Class III devices under U.S. regulation and require PMA pathways, with the European MDR imposing rigorous Annex II conformity assessment and enhanced post‑market surveillance obligations.
-
Reimbursement: Recent payer actions — including an updated DRG for LVAD implants and changes to procedural coding that recognize new approaches — are already influencing hospital economics and may accelerate or decelerate regional adoption depending on pathway design.
-
Recall risk: Device advisories and class I recalls have immediate commercial fallout. Companies must pair device engineering plans with rapid-response clinical and communications playbooks to protect center relationships and minimize attrition.
What the full PW Consulting report delivers (practical components)
-
Demand forecasting package: Transparent top‑down and bottom‑up models with scenario sensitivity (base, upside, downside) covering 2026–2032 and incorporating epidemiology, center capacity, and payer dynamics.
-
Commercial playbooks: Market entry and expansion templates for incumbents, challengers, and new entrants — including sample KPIs, training curricula, and consumables pricing strategies.
-
Regulatory roadmap and time‑to‑market planning: Country‑level approval timelines, required clinical endpoints, and PMA/Notified Body considerations that materially affect launch sequencing and resource allocation.
-
Reimbursement impact models: Provider margin simulations under DRG and CPT updates to estimate adoption thresholds across hospital archetypes and payer mixes.
-
Competitive deep dives: Strategic profiles and recent development summaries for the leading players, with implications for partners, suppliers, and acquirers.
-
M&A and partnership screening tool: Valuation heuristics and a short list of candidate assets/categories prioritized for strategic buyers and private equity sponsors.
-
Operational readiness checklist: Manufacturing scale considerations, aftermarket service models, and supply chain vulnerabilities critical to sustaining growth in 2026 and beyond.
Methodology and credibility
Our findings are grounded in a blended research approach: primary interviews with clinical and procurement leaders at implant centers, detailed billing and claims analysis, device registry and trial outcome synthesis, and a proprietary forecasting engine that triangulates epidemiology, center capacity, and historical adoption curves from 2020–2025. We validate outputs through sensitivity testing and scenario analysis to reflect regulatory shocks, evidence inflection points, and reimbursement changes. To preserve tactical value for clients, this public summary is deliberately high‑level; the full report contains the supporting datasets, model logic, and payoff matrices used to generate our projections.
Next steps for executives and investors
-
Prioritize clinical evidence programs that target durable survival and neurological outcomes — these are the single biggest determinant of payer coverage and center preference.
-
Build dual pathways for growth: defend core centrifugal platforms while exploring adjacent service and total‑heart solutions that capture unmet clinical segments.
-
Stress‑test M&A opportunities against regulatory timelines and recall‑scenario contingencies — integration plans should explicitly cover post‑market surveillance and product liability drag.
-
Engage payers early with real‑world evidence frameworks and hospital pilots aligned to updated DRG/CPT mechanics to accelerate adoption at reference centers.
PW Consulting’s Worldwide Adult Ventricular Assist Device Market report is designed as an executable intelligence product for leadership teams setting 2026 priorities. To access the full dataset, segmentation detail, executable playbooks, and proprietary models referenced in this briefing — including the granular regional and application splits withheld here to preserve strategic value — visit the PW Consulting report landing page or contact our advisory team to arrange a briefing and demonstration.
For detailed analysis of this topic, please visit the official page: Worldwide Adult Ventricular Assist Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Integral Waterproofing Compound Market Set to Grow at a 5.28% CAGR Through 2032, PW Consulting Reports
By pmarketresearch, 2026-08-12
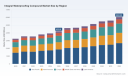
PW Consulting: Strategic Preview — Worldwide Integral Waterproofing Compound Market (2026 Outlook)
PW Consulting today publishes a strategic preview of our upcoming market research release on the Worldwide Integral Waterproofing Compound market. Built from a base year of 2025 and covering a forecast window through 2032, the study demonstrates that the sector is on a sustained growth path — with the global market sized at approximately USD 4,215.8 Million in 2025 and an expected near-term step to roughly USD 4,628.5 Million in 2026, driven by an average compound annual growth rate of 5.28% across the forecast period. For senior executives preparing budgets, product roadmaps and M&A pipelines in 2026, this research serves as a practical, decision-grade briefing: it translates macro momentum into the operational choices that will define winners and laggards in the coming planning cycle.
One-Arm Bandit Market
Why this report matters to 2026 decision-making
-
From procurement to product management, organizations need a clear line of sight on how demand and cost dynamics interact. Our modelling integrates recent volatility in key feedstocks and their pass-through to finished-product economics, enabling finance and commercial teams to build defensible price and margin scenarios into 2026 planning cycles.
Worldwide Anisotropic Conductive Film (ACF) Tape Market -
Regulatory and sustainability imperatives are shifting formulary priorities. The report maps how low-VOC and bio-based chemistries are moving from niche green credits to procurement preconditions in major infrastructure and commercial tenders — a shift that has direct implications for R&D allocation and go-to-market timing in 2026.
Wire Beam LiDAR Market -
Competitive positioning is fragmenting in ways that favor both scale and specialization. We provide a pragmatic playbook for players at every point on the value chain — raw material suppliers, admixture formulators, ready-mix partners, and contractors — to convert market signals into concrete near-term actions (product launches, distribution pivots, and targeted partnerships).
What the report contains — practical deliverables
-
Decision-ready market sizing and trend analysis calibrated to 2025 base values and extended through 2032, including sensitivity runs for cost and demand shocks relevant to 2026 budgeting cycles.
-
An operational segmentation framework that supports SKU-level portfolio prioritization, build-or-buy tradeoffs, and channel investment sequencing. (Note: this public summary intentionally omits the detailed segment tables and breakouts; the full dataset and downloadable models are included in the paid report.)
-
Supply-chain and cost models that quantify the impact of raw material volatility and energy cost shifts on margin profiles, with recommended hedging and contract structures tailored to admixture chemistries.
-
Competitive benchmarking and capability heat maps covering leading global and regional players, plus an M&A screening tool that ranks strategic targets against capability gaps and route-to-market objectives.
-
Implementation playbooks: pilot design templates, specification checklists for procurement teams, and KPIs for post-deployment performance validation in both ready-mix and in-situ concrete applications.
-
Regulatory and sustainability roadmaps explaining how green building programs and evolving low-emission standards will impact product acceptance and tender scoring in major markets.
Competitive landscape — synthesized insights for 2026 strategy
The market structure is neither a pure oligopoly nor highly atomized: our concentration metrics indicate a moderate level of aggregation among the largest players, leaving significant runway for specialized entrants and regional champions. The following high-level assessment of incumbent and emerging competitors is designed to support comparative strategy discussions; the report contains in-depth profiles, primary interview excerpts, and technology-readiness assessments.
-
Sika AG (Baar, Switzerland) — A leading global construction chemicals player with an extensive integral admixture portfolio and deep historic expertise. Sika’s strength lies in broad channel coverage and integrated systems sales; for 2026, their playbook is likely to emphasize bundle selling (admixtures + system warranties) and leveraging global R&D platforms to accelerate low-VOC variants.
-
Kryton International Inc. (Vancouver, Canada) — A specialist in crystalline technologies with differentiated claims around internal membrane functionality and self-healing performance. Kryton represents the archetype for technology-led premiumization, attractive to infrastructure projects requiring lifecycle performance assurances.
-
Xypex Chemical Corporation (Richmond, Canada) — Another crystalline-focused incumbent that emphasizes the integrality of treatment into the concrete matrix rather than surface membranes; Xypex’s strength is brand association with “spec-grade” durability, making it a frequent choice on projects where performance risk is price-insensitive.
-
The Euclid Chemical Company (Cleveland, USA) — With long-standing product lines in stearate-based and powdered internal repellents, Euclid exemplifies channel-facing product strategy, focusing on contractor ease-of-use and compatibility with U.S. ready-mix practices.
-
Anti-Hydro International (USA) — A heritage player with a century-long market presence; their value is in trust and tried-and-tested formulations, especially in renovation and masonry segments where specification inertia matters.
-
Pioneer Fibre / Pioneer (Hong Kong) — A regional system supplier with executional experience on major bridges and tunnels; represents the commercial case for coupling admixture capability with local construction services and project delivery teams across Asia.
-
Chem Concrete Pty Ltd (Australia) — Offers a patented hybrid admixture that blends densifiers, pore blockers and nano-scale treatments — an example of the disruptive NPI that can command premium pricing and long-term warranties where clients value lifecycle cost reductions.
-
BASF SE (Ludwigshafen, Germany) — Through its construction chemicals division, BASF brings scale R&D and a global distribution footprint. Its strength lies in enabling compatibility with supplementary cementitious materials and downstream co-marketing with complementary construction chemistries.
-
Mapei SpA (Milan, Italy) — A broad-based admixture house with product families tuned for European specifications; MAPEI is typically strong in high-spec commercial and renovation segments where product-system certification matters.
-
Fosroc International (Dubai, UAE) — A major regional player with solutions tailored for Middle East climates and construction practices; Fosroc’s route-to-market advantages stem from regional logistics, specification influence and contractor relationships.
-
Pidilite Industries Ltd. (Mumbai, India) — Represents the scale low-cost play in Asia, backed by deep distributor networks and local formulation expertise; Pidilite is a candidate for rapid share expansion where price sensitivity dominates.
-
Penetron International Ltd. (USA) — Known for crystalline systems focused on long-term durability; Penetron appeals to owners seeking single-source warranty propositions and is a frequent name on high-risk below-grade structures.
Industry dynamics that will dominate 2026 planning
-
Raw material volatility — Energy-driven shifts and chemical supply disruptions have periodically increased costs for critical inputs. Finance teams should embed stress-tests and raw-material passthrough clauses into long-term contracts to protect margin in 2026 forecasts.
-
Regulatory and green-building pressure — Low-VOC and bio-derived hydrophobic chemistries are moving from preferential scoring to procurement requirements in many institutional tenders. Product roadmaps that prioritize these chemistries will face less tender friction and higher specification uptake.
-
Channel and procurement evolution — Automated dosing at ready-mix plants and integration with supplementary cementitious materials are reshaping product form-preference. Manufacturers need manufacturing and logistics adaptations to capture growth where volumetric dosing is the norm.
-
Product premiumization vs. commoditization — The market bifurcates between low-cost hydrophobic powders and higher-value crystalline or hybrid systems. Strategy choices in 2026 should explicitly pick a lane — scale-volume or performance-premium — and align R&D, pricing and service models accordingly.
Recommended near-term actions for executives
-
Prioritize formulation investments that meet low-VOC requirements and certify to common green-building standards; this reduces tender friction and can justify price premiums.
-
Implement procurement frameworks that include raw-material indexation clauses and strategic supplier partnerships to reduce exposure to input-cost shocks.
-
Test premium hybrid admixtures on pilot infrastructure projects where lifecycle cost analysis can validate higher margin positioning and warranty commitments.
-
Expand technical services and specification support as a differentiator: warranty-backed systems and strong field support shorten sales cycles with institutional buyers.
-
Use the report’s M&A screening output to identify bolt-on targets that fill capability gaps (e.g., crystalline know-how, regional distribution, or complementary polymer chemistry).
Risk scenarios we modelled
-
Raw-material price shock: an input-cost spike that compresses margins for commodity players and accelerates consolidation.
-
Regulatory tightening: accelerated adoption of bio-derived agents that renders older solvent-based formulations commercially disadvantaged in major tenders.
-
Channel disruption: rapid automation of ready-mix plants, favoring liquid admixtures and penalizing powder-centric supply chains lacking packaging/logistics scale.
PW Consulting’s Worldwide Integral Waterproofing Compound Market report is intentionally structured to be a practical tool for the 2026 planning cycle: it offers not only directional market intelligence but also executable plans, contract language templates, and pilot ROI models. This preview demonstrates the report’s strategic value while preserving the granular segment and financial tables to encourage direct access to the full dataset.
To access the complete dataset, modelling templates, and company dossiers that underpin the recommendations above, please refer to the full PW Consulting report and dataset available through our client portal. PW Consulting’s advisors are available to present tailored briefings and to run enterprise-specific scenario workshops to operationalize the findings for your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Integral Waterproofing Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Inguinal Hernia Repair Mesh Market Valued at USD 4,801 Million in 2025 — Global Forecast to 2032
By pmarketresearch, 2026-08-12
PW Consulting Strategic Brief: Worldwide Inguinal Hernia Repair Mesh Market — Actionable Outlook for 2026 Decision Makers
Executive snapshot
Our Worldwide Inguinal Hernia Repair Mesh Market study (base year 2025; forecast 2026–2032) consolidates five years of historical performance and forward-looking scenario analysis to equip life‑science executives, strategy teams, and investors with the signals they need to act in 2026. The global market is sized at a multi‑billion dollar level in 2025 (USD, revenue basis) and is expected to grow at a compound annual growth rate (CAGR) of 4.8% through the 2026–2032 forecast window. By the end of that horizon the market reaches materially higher scale, driven by a mix of procedure volumes, technology adoption, and product innovation.
Thyristor Dimming Power Supply Market
This brief summarizes the strategic implications we extract from the full report: the economic drivers, regulatory inflection points, competitive positioning, and the go‑to‑market actions that will determine winners and laggards in 2026. In keeping with the “trailer” principle, we demonstrate analytical depth while reserving granular segment tables and region/application line items for the full report—available from our website for clients who require the underlying models and line-by-line forecasts.
Battery Operated Mobile Power Market
What the report delivers — practical components that CFOs and Heads of Product will use in 2026
- Robust market sizing and verified historical demand (2020–2025) plus baseline and alternative scenarios to 2032, enabling stress‑tested revenue planning.
- Scenario‑based financial models that translate procedure throughput, device mix, and pricing pressure into P&L and cash‑flow outcomes; model templates are client‑editable.
- Competitive landscaping and capability mapping: product portfolios, clinical positioning, regulatory status, litigation exposure, and IP/technology adjacencies for the leading players.
- Regulatory and reimbursement tracker with tactical recommendations for label strategy, submission sequencing, and payer evidence requirements in core markets.
- Supply‑chain risk assessment including raw material cost sensitivity, alternative sourcing options, and inventory/hedging playbooks to manage margin contraction.
- Commercial playbooks for hospitals, ambulatory surgical centers (ASCs), and high‑volume specialty practices—covering value‑based contracting, pricing tiers, and adoption levers.
- Deal‑making and partnership framework: prioritized M&A and alliance targets, integration checklists, and waterfall valuation scenarios that reflect market concentration dynamics.
Competitive landscape — who matters and why (high‑level view)
The market shows moderate concentration among a small group of established manufacturers, creating both competitive pressure and pockets of opportunity for differentiation. Our qualitative and quantitative assessment indicates leading incumbents maintain strong distribution, clinical relationships, and breadth of mesh technologies, from traditional polypropylene products to next‑generation bioresorbables and composite constructs.
Worldwide Phone Sanitizer Market
- Becton Dickinson (BD) — Demonstrates a dual strategy of established polypropylene solutions and higher‑value bioresorbable options. The company’s recent Phasix expansion and the January 2026 prophylactic indication milestone in Europe highlight a strategy that pairs product innovation with indication expansion to capture prevention and reinforcement segments.
- Medtronic (Covidien) — Focused on anatomical and laparoscopic‑optimized meshes, including self‑fixating technologies that target minimally invasive workflows. Their product design leverages procedure efficiency and OR time reduction to support adoption in centers performing laparoscopic TAPP/TEP approaches.
- Ethicon (Johnson & Johnson MedTech) — Maintains a strong position with a broad polypropylene portfolio and partially absorbable options that span both open and minimally invasive procedures; this provides pricing and clinical flexibility in hospital negotiations.
- B. Braun (Aesculap) — Competes on differentiated light‑weight meshes and clinician ergonomics, appealing to markets where surgeon preference and handling characteristics drive procurement.
- W. L. Gore & Associates — Offers ePTFE‑based and dual‑surface materials that are positioned around adhesion reduction and specific reconstructive use‑cases where tissue interaction matters most.
- Getinge (Atrium Medical) — A historic synthetic mesh supplier whose product legacy is accompanied by legal and reputational considerations; an important competitor in select markets and a reminder of litigation risk management.
Collectively, the top three and top five competitors account for a meaningful share of market revenue, which reinforces the importance of competitive intelligence and targeted differentiation. The full report includes proprietary heatmaps of R&D focus, go‑to‑market strength, and litigation/reputational exposure for each named company.
Regulatory, reimbursement, and raw‑material dynamics shaping 2026 decisions
- Regulatory: The U.S. FDA’s June 2025 draft guidance on standardized package labeling for hernia mesh devices introduces a new expectation for clinically relevant, consistent instructions and risk communication. Device sponsors should incorporate label harmonization into submission timelines and post‑market surveillance plans; early adoption can become a competitive differentiator in hospital purchasing committees.
- Reimbursement: Updated Medicare coding and payment rules effective January 1, 2026, alter the economics of hernia procedures in core markets. Manufacturers must align their value dossiers and pricing strategies to reflect the new national averages and coding pathways—especially when proposing higher‑priced composite or bioresorbable options.
- Raw materials: Medical‑grade polypropylene prices have risen substantially since 2021 (exceeding a 35% increase and reaching roughly $1,700 per metric tonne in 2024), exerting upward pressure on manufacturing costs. This dynamic necessitates margin protection strategies—contract renegotiation, formula optimization, and selective cost pass‑through tactics.
Strategic imperatives for 2026 — recommended actions
Companies should translate these market signals into a compact set of executable initiatives with defined owners and timelines. Our priority recommendations for 2026 are:
- Regulatory readiness and labeling playbook — Treat the FDA labeling guidance as a product launch enabler. Prepare harmonized global labels and accompanying clinician education packages to shorten adoption cycles in hospitals and ASCs.
- Portfolio prioritization — Run a rapid, economics‑based ranking of SKUs (clinical value × margin × addressable volume). De‑list or divest low‑margin, low‑share SKUs; reinvest in higher‑margin products supported by clear clinical outcomes evidence.
- Evidence‑to‑value investments — Target limited, pragmatic clinical studies (real‑world evidence and registry linkages) that close payer and surgeon evidence gaps—especially for prophylactic and bioresorbable propositions.
- Supply‑chain hedging and design substitutes — Lock multi‑year supply agreements, qualify alternate polymer sources, and accelerate development of lower‑polypropylene‑content constructs where clinically justified.
- Channel and contracting segmentation — Differentiate strategies across hospitals, ASCs, and high‑volume specialty clinics. For ASCs, emphasize procedure efficiency and bundled pricing; for hospitals, focus on value dossiers tied to long‑term outcomes and readmission reductions.
- M&A and partnerships — Pursue tuck‑ins that add differentiated materials or evidence capabilities; avoid targets with unmanaged litigation risk. Use our deal‑screening matrix to prioritize targets that accelerate time‑to‑market or broaden digital/clinical services.
- Commercial KPI dashboard — Implement a concise dashboard for 2026 with leading indicators (OR adoption rates, average selling price by channel, hospital conversion time, inventory days) tied to monthly review cadence between commercial and supply functions.
How PW Consulting supports 2026 execution
Our report is designed as both an analytical product and a practical toolset. For executive teams seeking immediate traction, we offer:
- Board‑level briefings that translate the 4.8% CAGR baseline and scenario outcomes into clear revenue and margin implications for 2026 planning cycles.
- Customized commercial playbooks by country cluster, including contract templates, pricing negotiation scripts, and hospital stakeholder maps.
- Due diligence packages for M&A that combine our financial model, litigation risk checklist, and integration‑ready commercial roadmaps.
- Supply‑chain stress tests and hedging strategies to isolate the impact of raw material price swings on gross margins and working capital.
We intentionally preserve the granular regional, product‑type, and end‑user line items within the full report to ensure clients receive the underlying data models and proprietary assumptions that support executive decisions. If you are planning budget allocations, product portfolio rationalization, or M&A activity in 2026, those detailed micro‑splits and scenario model files will materially shorten your runway from decision to execution.
Next steps
For companies preparing 2026 strategy cycles, the combination of a mid‑single‑digit growth baseline, evolving regulatory expectations, rising raw‑material input costs, and a moderately concentrated competitive set creates a narrow window to reposition. PW Consulting’s full Worldwide Inguinal Hernia Repair Mesh Market report contains the granular forecasts, sensitivity analyses, and executable playbooks required to make defensible, high‑velocity decisions.
Contact our advisory team to arrange a tailored briefing or to license the full dataset and model. Our clients use these deliverables to accelerate go‑to‑market decisions, de‑risk sourcing strategies, and prioritize clinical investments—so they can convert market signals into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Inguinal Hernia Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Elemental Fluorine Market to Grow at 6.18% CAGR from USD 928.5M in 2025 to USD 1.41B by 2032 as Asia‑Pacific Leads with USD 443.2M (Top 3 Hold 64.2%)
By pmarketresearch, 2026-08-12
Worldwide Elemental Fluorine Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest market research on the Worldwide Elemental Fluorine Market crystallizes why 2026 is a pivotal year for industrial players, capital allocators, and public-sector stakeholders. Grounded in a detailed five‑year historical analysis (2020–2025) and a rigorous forecast through 2032, the study synthesizes market-scale dynamics, regulatory pressure points, supply‑chain fragility, and competitive positioning into an actionable strategic playbook. The market base year is 2025 (USD, revenue unit: Million) and the forecast covers 2026–2032; compound annual growth is modeled at 6.18% across the outlook horizon.
Worldwide Receiving and Tracking Software Market
Why this report matters for 2026
-
Timing of critical choices: As companies finalize capital expenditure plans and long‑term supply agreements for the period 2026–2029, small differences in risk assessment will determine who secures low‑cost feedstock and who bears elevated transport and compliance premiums.
Robotics for K-12 Education Market -
Market momentum and volatility: After a trough and recovery cycle during 2020–2025, the market reached an elevated baseline in 2025 (USD 928.5 Million). Our scenario models show the market returning to steady expansion through 2032, with the base case projecting a market approaching the USD 1.4 billion range by the end of the forecast period—an outcome that materially changes capital allocation calculus for downstream users.
Porous Tantalum Market -
Concentration and bargaining power: The market exhibits pronounced concentration among a handful of suppliers. The top three firms account for a clear majority of supply and the top five extend that concentration materially, which has immediate implications for counterparty risk, negotiation leverage, and M&A rationale.
Market dynamics: supply, cost, and regulation
-
Feedstock pressure and cost pass‑through: Raw material availability and feedstock pricing remain the principal near‑term cost drivers for elemental fluorine producers. Tightness in fluorspar channels and periodic spikes in anhydrous hydrogen fluoride pricing have amplified margins for integrated suppliers while compressing margins for merchant specialists. These dynamics are decisive for producers that lack vertically integrated upstream feedstock.
-
Transportation and classification friction: Elemental fluorine’s hazardous classification imposes specialized transport protocols, which elevates logistics complexity and episodic freight premiums. Companies that have pre‑certified global logistics chains maintain differentiated delivery reliability—an important competitive moat for semiconductor and nuclear end users with low tolerance for interruption.
-
Regulatory tightening: Across major regulatory jurisdictions there is sustained scrutiny of fluorine‑related chemistry. Authorization regimes and persistent reviews of industrial uses create multi‑year compliance lead times. Firms that have mapped regulatory pathways and embedded compliance contingencies into product roadmaps will face lower program risk in 2026 and beyond.
-
Geopolitical concentration risk: Global fluorspar sourcing remains regionally concentrated. Export policy shifts and quota adjustments in primary producing nations create asymmetric supply shocks, which cascade into HF and F2 availability. Portfolio diversification of sourcing is therefore a second‑order strategic imperative for risk‑averse purchasers.
Competitive landscape — what the market structure means for strategy
-
Incumbents with integrated footprints: Established suppliers such as Air Products and Chemicals, Inc. and Solvay SA benefit from broad downstream customer footprints and, in several cases, vertically integrated feedstock access. Their scale delivers contract flexibility and prioritized capacity allocation for strategic customers.
-
Specialist producers: Players focused on dedicated elemental fluorine production—represented by regional champions—offer high‑purity grades and niche service models (e.g., cylinder management, on‑site delivery), making them indispensable to sensitive end markets such as uranium enrichment and advanced semiconductor etching.
-
High‑value differentiation: Japanese manufacturers and other technology‑oriented suppliers concentrate on ultra‑high purity and closed‑loop quality systems that command premium pricing in semiconductor and advanced materials applications. These firms derive much of their competitive advantage from intellectual property, process control, and tight customer partnerships.
-
Recent disruptions underscore fragility: Public episodes, including force majeure events at major fluorochemical facilities and capacity restarts at dedicated producers, have intermittently removed material supply from the market. These incidents amplified spot volatility and demonstrate why multi‑sourcing and buffer inventory strategies remain defensive necessities.
What our report delivers (practical, decision‑oriented contents)
-
Executive decision maps: Rapid‑read frameworks that translate market scenarios into prioritized actions for procurement, supply‑chain, and R&D leaders over 12–36 month timeframes.
-
Supply‑risk matrix and hedging playbook: Granular supplier risk scoring, contingency pathways (contractual and operational), and recommended inventory buffers calibrated to supplier concentration and transport constraints.
-
Regulatory navigation kit: Jurisdictional trackers, compliance timelines, and authorization templates that shorten review cycles for industrial uses, with sensitivity analysis for potential REACH‑style outcomes and transport rule changes.
-
CapEx and investment modeling: Scenario‑based NPV and IRR outputs for brownfield debottlenecking versus greenfield capacity, incorporating realistic feedstock and logistics cost trajectories under several commodity price regimes.
-
Go‑to‑market and partnership archetypes: Commercial models for incumbents and new entrants—ranging from toll‑manufacturing contracts to long‑term offtake agreements and technology licensing—mapped to buyer willingness to pay and service requirements.
-
Operational playbooks for purity‑sensitive buyers: Quality assurance protocols, cylinder management practices, and emergency substitution guidance when transitioning between grades or suppliers while protecting process yields.
Strategic recommendations for organizations preparing decisions in 2026
-
Prioritize resiliency over lowest‑cost sourcing: Given supplier concentration and episodic upstream disruption, firms whose procurement strategies emphasize resilience (multi‑tier sourcing, strategic inventory) will outperform purely price‑focused peers on continuity and total cost of ownership.
-
Lock in strategic partnerships with tier‑one suppliers: For semiconductor fabs and nuclear fuel processors where supply interruption is existential, negotiating priority allocation clauses and shared investment into capacity expansion are high‑leverage moves in 2026 discussions.
-
Invest in regulatory intelligence and compliance readiness: Anticipate multi‑year lead times for authorization processes; accelerating dossier preparation and early regulator engagement materially reduces commercialization risk for new uses or reformulated chemistries.
-
Model capex under multiple commodity regimes: When evaluating capacity addition, use conservative feedstock price scenarios and include logistics contingency costs; short payback projects and modular debottlenecks often dominate against large greenfield commitments in current market dynamics.
-
Consider strategic M&A or joint ventures to manage concentration risk: For buyers seeking to internalize supply security, carefully structured equity positions in production assets deliver both supply reliability and potential margin capture without full greenfield exposure.
Where the report is intentionally selective — the “trailer” principle
To respect client confidentiality and to preserve the analytical value of the proprietary dataset, this briefing deliberately omits detailed regional/applicational splits and line‑item supplier scorecards. The full report contains exhaustive segmentation models (regional, application, and grade breakdowns), raw supplier benchmarking tables, contract template libraries, and downloadable scenario spreadsheets that decision makers can use directly in procurement negotiations and capital planning. These assets are available on the report landing page.
How senior leaders should use the report in 2026 planning cycles
-
Procurement leaders: Use the supplier risk matrix and the recommended contract clauses to renegotiate terms before renewals come due in 2026–2027.
-
Corporate strategy teams: Incorporate the scenario‑based forecasts and capex models into the company’s three‑year strategic plan and capital allocation playbook.
-
R&D and product teams: Leverage the regulatory navigation kit to prioritize product reformulations that minimize exposure to high‑risk inputs while maintaining performance for demanding end uses.
-
Investors and advisors: Apply our valuation templates to stress‑test portfolio companies exposed to feedstock volatility and to identify defensive investments with outsized optionality in constrained markets.
Concluding perspective
The elemental fluorine market is entering a phase where scale, regulatory fluency, and supply‑chain design will differentiate winners from the rest. With a market that rebounded to a much higher baseline by 2025 and a compound annual growth trajectory of 6.18% through 2032 under our base case, choices made in 2026—about partnerships, capacity, and regulatory positioning—will determine multiyear outcomes. PW Consulting’s report is engineered to convert market intelligence into executable decisions: it surfaces the levers that matter and equips leaders with the tools to act, while retaining the detailed segmentation and supplier analytics behind a secure, subscriber‑level experience.
For access to the full dataset, supplier scorecards, and downloadable scenario models, visit our report landing page to obtain the complete Worldwide Elemental Fluorine Market study and the PW Consulting strategic toolkit for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Elemental Fluorine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biometric Signature Pads Market Forecast to Grow at a 7.15% CAGR Through 2032
By pmarketresearch, 2026-08-12
Biometric Signature Pads Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As enterprises accelerate digital-first customer journeys and regulators across major jurisdictions tighten the legal framework for electronic signatures, biometric signature pads are moving from niche utility to strategic infrastructure. PW Consulting’s latest market research — covering historical performance through 2025 and a forward-looking forecast to 2032 — distills the actionable intelligence procurement leaders, CISOs, and M&A teams will need to decide with conviction in 2026.
Octyl-phenolic Tackifying Resin Market
Headline market dynamics (what the numbers tell us)
By the close of our base year (2025) the biometric signature pads market reached a substantive, enterprise-grade scale (USD 480.0 Million). Our forecast for the 2026–2032 horizon uses a robust compound annual growth rate of 7.15%, projecting the market to nearly double in value by the end of the period. These headline figures reflect a sustained combination of demand-side adoption — driven by banking, government, healthcare, and retail digitalization programs — and supply-side evolution, including tighter security standards, richer sensor fusion, and more resilient product designs for high-throughput environments.
Worldwide Oral Ulcer Drug Market
Two structural observations underpin the forecast and should be central to 2026 strategy planning. First, the market exhibits a clear, mid-level concentration: the top three vendors control a meaningful share of industry revenue and the top five increase that share substantially. Second, regulatory alignment (notably EU eIDAS and related ISO standards) and supply-chain volatility (including evolving tariff structures for electronics components) are simultaneously creating entry barriers and differentiation opportunities for incumbents and new entrants alike.
Ropinirole Hydrochloride Tablets Market
Why this report matters for 2026 decision-makers
- Procurement timing and TCO optimization. Public- and private-sector buyers face a tradeoff between early adoption to capture operational efficiencies and the risk of short-lived product obsolescence as sensor and security capabilities iterate. Our scenario-based TCO models translate device selection, integration costs, and upgrade cycles into three procurement schedules — rapid refresh, phased deployment, and long-life buy — to help procurement teams justify capital plans to finance and IT governance boards.
- Regulatory compliance & legal defensibility. For organizations that must achieve qualified or advanced electronic signature status, device selection is not merely technical; it is legal. The report includes a regulatory matrix that maps device features (dynamic biometric capture, secure element, certified firmware) to compliance outcomes under the EU eIDAS framework and major national regimes, enabling legal and compliance teams to close the gap between product claims and demonstrable legal equivalence of signatures.
- Supply chain and cost-risk playbook. Given ongoing tariff pressures and component sourcing concentration, we provide a supplier risk scoring tool and contingency playbook that teams can implement to hedge against lead-time spikes, input-cost inflation, and single-source exposure.
- M&A and partnership screening. For corporate development and PE investors, the report identifies capability adjacencies (e.g., secure elements, identity orchestration, integration with e-signature platforms) that accelerate time-to-market and de-risk customer retention. Our M&A decision framework prioritizes targets by defensibility, integration complexity, and revenue synergy potential.
What’s in the PW Consulting report — practical, executable content
- Comprehensive market-size and trend model (historical 2020–2025 and forecast 2026–2032) with sensitivity scenarios tied to regulation, economic growth, and component pricing.
- Vendor due-diligence templates and a vendor scorecard that converts qualitative features (encryption approaches, biometric fidelity, integration SDK maturity) into an objective selection ranking.
- Integration playbooks for payments, EMR/EHR, and government identity systems — including recommended data flows, PII handling patterns, and APIs for common enterprise stacks.
- Regulatory compliance matrix mapping device characteristics to eIDAS and ISO/IEC standards, plus a checklist for qualifying devices under national signature regimes.
- Case studies and deployment blueprints from high-volume environments, highlighting best-practice device configuration, ergonomics for throughput, and long-term maintenance schedules that materially affect TCO.
- Channel and go-to-market playbooks for vendors: recommended pricing models, enterprise sales motions, and partner ecosystems that accelerate adoption in regulated verticals.
Competitive landscape — strategic positions and differentiation
The competitive environment combines long-standing hardware specialists with security-centric European players and software-integrated suppliers. Among the established names we analyzed in depth:
- Topaz Systems (Simi Valley, CA) — A broad product portfolio targeting regulated verticals, with solutions that blend LCD displays and biometric sensors. Their strength lies in vertical-specific integrations and a long track record in healthcare and finance deployments.
- Scriptel Corporation (Columbus, OH) — Known for robust, high-uptime designs and deep point-of-sale and healthcare integrations. Scriptel’s emphasis on durability and workflow optimization makes them a frequent choice in high-throughput environments.
- Wacom Co., Ltd. (Japan) — A leader on dynamic-capture fidelity, Wacom’s devices are optimized for high-resolution pressure- and motion-based biometric capture, which supports advanced verification flows and anti-spoofing measures.
- ePadLink (Interlink Electronics) — A software-hardware bundle approach, where device hardware is complemented by e-signature software offerings designed to simplify enterprise integration and legal workflows.
- StepOver GmbH (Germany) — A European security-first player, with recent product introductions targeted at regulatory-compliant deployments in the EU market. StepOver’s December 2025 launch of a new, ruggedized pad underscores the premium on eIDAS-ready devices in regulated environments.
- Euronovate Group (Switzerland/Italy) and Signotec GmbH (Germany) — Both emphasize high-security features (e.g., secure elements, multi-factor in-person signing), and are particularly focused on eIDAS compliance and enterprise audit trails.
Collectively, incumbents differentiate along three vectors: biometric fidelity and sensor fusion; security architecture (from firmware-to-element); and integration maturity (SDKs, enterprise connectors). For buyers, the win is in matching business-process requirements (compliance class, throughput, ergonomics) to vendor strengths — not chasing the newest sensor alone.
Regulation, standards and the device buying imperative
Regulatory alignment is a decisive factor. Biometric pads that capture dynamic signing metrics (pressure, velocity, timing) are demonstrably more defensible when assessed against ISO/IEC standards and eIDAS criteria for advanced electronic signatures. For organizations seeking qualified legal equivalence to handwritten signatures in the EU, device-level capabilities (secure firmware, certified cryptographic modules, tamper-evidence) must be part of procurement specifications. Our report includes a compliance gap analysis and vendor questionnaire that legal teams can use immediately.
Practical recommendations for 2026 strategy
- Start with use-case mapping, not vendor shopping. Prioritize the highest-value signing scenarios (e.g., high-replay risk contracts, regulated onboarding, high-volume transactional counters) and define required assurance levels before evaluating devices.
- Insist on field-validated integration artifacts. Demand reference architectures and SDKs for your core stacks (payments, EMR, identity platforms). Integration cost rather than device MSRP will often dominate TCO.
- Specify security primitives. Require secure elements, signed firmware, audit-ready logs, and cryptographic anchors in procurement RFPs where legal defensibility matters.
- Hedge supply-chain risk. Build alternate sourcing clauses and inventory buffers for high-throughput deployments; evaluate partnering with distributors that can offer cross-manufacturer fulfillment.
- Plan replacement cycles with upgrade pathways. Define clear lifecycle policies (firmware update processes, device decommissioning) to avoid legal and operational exposure as standards evolve.
- Use vendor scorecards and pilots. Run short, instrumented pilots with objective KPIs (capture accuracy, time per transaction, error rates, user satisfaction) and embed those results into purchase authorization thresholds.
How PW Consulting’s deliverables accelerate your 2026 decision-making
Our report is intentionally operational: beyond market tables and forecasts, it contains vendor scorecards, deployment blueprints, regulatory checklists, and cost models you can apply within weeks. For executives weighing procurement cycles, partnership strategies, or acquisition targets, the analysis reduces uncertainty by converting high-level trends into executable, measurable steps.
We adhere to a “signal-first” approach in this preview: we reveal enough strategic insight to prioritize decisions and scope pilots, while reserving the granular segmentation tables, downloadable financial models, and interactive vendor comparison dashboards for the full report package. Those detailed exhibits contain the exact regional and application splits, device-level revenue models, and scenario spreadsheets that are essential to vendor negotiation and capital planning.
Next steps — read the full findings
PW Consulting’s full Biometric Signature Pads Market Report provides the complete dataset, interactive models, and the downloadable vendor & compliance toolkits that procurement, legal, and corporate development teams will use to make binding 2026 decisions. To access the granular segmentation, company profiles, and the proprietary scoring templates that underpin our recommendations, please visit our report page or contact our industry practice for a briefing tailored to your organization’s priorities.
In an environment where legal standards, customer expectations, and supply-chain realities are converging, the right device choice is as much a strategic decision as a technical one. Use 2026 to move from transactional buys to architecture-led procurement that secures compliance, operational resilience, and long-term value capture.
For detailed analysis of this topic, please visit the official page: Biometric Signature Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Retort Cartons Market Set to Grow at 7.6% CAGR, Reaching USD 1,406.88 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Retort Cartons Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
As packaged-food value chains reset for post-pandemic growth and regulatory tightening, retort cartons are shifting from a niche innovation to a strategic packaging platform for shelf-stable food and pet categories. PW Consulting’s new market study — anchored on 2025 as the base year with a 2026–2032 forecast window — projects robust expansion at a compound annual growth rate (CAGR) of 7.6% during the forecast interval. In monetary terms, the global retort cartons market is forecast to grow from approximately USD 842.5 Million in 2025 to roughly USD 1,406.9 Million by 2032.
This briefing highlights the report’s decision-useful findings without disclosing the granular segment-level economics: our intent is to demonstrate the rigor of analysis while directing specialists to the full report for the proprietary breakdowns, scenario tables, and opportunity matrices that drive investment and procurement decisions.
Why this matters to corporate strategists in 2026
-
Portfolio reshaping: Food brands looking to reduce supply chain risk and improve sustainability indices are evaluating retort cartons as can-and-jar alternatives that deliver shelf-life parity with materially lower transport weight and potentially improved consumer convenience.
-
Regulatory preparedness: Extended Producer Responsibility (EPR) regimes and ambitious EU recyclability mandates (full recyclability targets toward 2030) are reshaping material choices and procurement specifications. Packaging decisions made in 2026 will determine compliance capital and operating trajectories through the end of the decade.
-
Margin protection vs. raw material volatility: Paperboard and barrier-film price movements have emerged as critical inputs to cost models. Early 2026 price adjustments announced by major paperboard suppliers sharpen the need for sensitivity testing in procurement and sourcing strategies.
Market trajectory — the high-level picture
Our top-line forecast establishes a clear growth runway: after an assessed market size of USD 842.5 Million in 2025, the market is expected to expand to roughly USD 925.6 Million in 2026 and accelerate over the subsequent years to reach approximately USD 1,406.9 Million by 2032. That growth equates to a 7.6% CAGR across the forecast period and reflects a confluence of product innovation, expanding converter capacity, and category adoption in both food and pet segments.
Importantly, market concentration remains high. The combined share of the three largest suppliers (CR3) exceeds 80%, and the top five (CR5) control close to 90% of value—evidence of structural entry barriers, technology specialization (sterilization-compatible laminates and forming/filling equipment), and long-term OEM–co-packer relationships. For market entrants and investors, this concentration profile signals both the scale premium required to compete and the potential for differentiated niche plays.
Key dynamics shaping the next wave of adoption
-
Regulatory drivers: EPR schemes in multiple US states and strengthened EU packaging rules are incentivizing higher fiber content, mono-material design where feasible, and documented end-of-life pathways. Companies that lock in compliant designs early will avoid costly redesigns and market access delays.
-
Material and technology evolution: Carton and pouch architectures continue to converge on high-barrier laminates that enable retort sterilization. Leading solutions combine renewable paperboard with engineered polymer and foil barriers to balance heat resistance and recyclability. For example, some carton architectures now incorporate multi-layer stacks integrating paper fiber, aluminum foil, and polypropylene layers to meet sterilization and shelf-life demands while increasing renewable and recycled content.
-
Supply-chain economics and price volatility: Paperboard suppliers announced price increases in early 2026; such moves amplify the importance of hedging strategies, long-term supplier contracts, and value-engineering of package designs to protect margins.
-
Converter and co-manufacturer capacity: New line installations and format-specific capacity (including micro-format production for premium pet and single-serve foods) are materially shifting where and how brands can scale. Co-manufacturers using specialized filling lines are becoming strategic partners for brand owners.
Competitive landscape — who matters and why
The retort carton market centers around a handful of global players combining materials know-how, equipment platforms, and customer ecosystem advantages. Our analysis profiles the major suppliers, their strategic positioning, and recent moves that matter to acquirers, licensees, and sourcing teams.
-
Tetra Pak (Pully, Switzerland) — A leader in carton-based retort formats, Tetra Pak’s Recart solution (including the R2 filling line and a range of small-format offerings) is positioned as a can-and-jar replacement for shelf-stable foods and pet categories. Its emphasis on high renewable paperboard content and integrated filling systems makes it a turnkey option for brands moving away from metal and glass.
-
Amcor (Zürich, Switzerland) — Amcor’s portfolio of high-barrier retort packaging spans carton-based and flexible structures, with recent product innovations including small-format retort bottles. The company’s R&D footprint and sustainability commitments make it a natural partner for multi-format rollouts.
-
SIG Combibloc (Neuhausen, Switzerland) — Focused on carton systems compatible with thermal processing, SIG is a core supplier for beverage and food brands requiring sterilization and extended shelf life.
-
Mondi (Weybridge, United Kingdom) — Mondi’s expansion into sustainable, retort-capable laminates and mono-material constructions reflects a push to meet regulatory recyclability tests while enabling thermal processing.
-
Huhtamaki (Espoo, Finland) — With an emphasis on fiber-based and mono-material retort options, Huhtamaki targets brands seeking recyclability without compromising sterilization performance.
-
Sonoco Products Company (Hartsville, USA) — A manufacturer of both carton and flexible retort formats, Sonoco’s material supply position makes it a significant actor in North American value chains.
-
ProAmpac (Cincinnati, USA) — Offers retortable flexible and carton solutions with a focus on high-barrier structures for ready meals and pet food, suitable for brands prioritizing format flexibility.
-
Constantia Flexibles (Vienna, Austria) — Specializes in retort laminates and has recently expanded mono-PP retort offerings that align with recyclability goals.
-
Coveris (Vienna, Austria) — Active in flexible and rigid retort formats, offering practical options for thermal-processed foods.
-
NaturPak Pet (Janesville, USA) — A co-manufacturer leveraging Recart technology to serve premium pet food with dedicated small-format capacity; recent capacity expansions underscore the commercial traction of small retort formats in pet care.
Recent strategic moves and tactical signals
-
2025-10 — NaturPak Pet confirmed expanded production using R2 lines with custom kits for small-format retort cartons, indicating strong demand in premium pet food micro-formats and growing co-manufacturer specialization.
-
2025-03 — Amcor launched an innovative 2oz retort bottle addressing low-acid, shelf-stable beverage formats—an example of product-level innovation unlocking new use cases for retort technologies.
-
2025-11 — Mondi broadened its food packaging portfolio with solutions crafted to meet emerging sustainability regulations, signaling supplier readiness to support brand compliance roadmaps.
-
2025-08 — Constantia Flexibles expanded its EcoVer mono-PP retort pouch range to combine heat resistance with improved recyclability—an indicator of materials-layer engineering responding to regulatory and collector-system constraints.
What our full report delivers — practical tools, not just forecasts
Clients tell us they need more than a number; they need executable roadmaps. The PW Consulting Worldwide Retort Cartons Market report provides:
-
Actionable scenario models (price, raw material shock, EPR stringency) with downloadable sensitivity tables that feed into corporate P&L and procurement dashboards.
-
An equipment and co-manufacturer mapping with line-capacity estimates, capital intensity profiles, and geography-aware lead times to support site selection and co-packing negotiations.
-
Regulatory impact matrices by jurisdiction (covering EPR, recyclability targets, labelling and reporting) aligned with compliance timelines to inform rollout sequencing.
-
Design-for-recycling playbooks and material substitution roadmaps that reconcile sterilization requirements with recyclability goals and cost constraints.
-
Commercial adoption models and consumer-perception testing summaries that quantify trade-offs between perceived sustainability, convenience, and price elasticity for retort formats in core categories.
-
Due-diligence templates and valuation heuristics for investors evaluating converter or format-specific M&A opportunities.
-
Case studies and implementation checklists from early adopters, covering manufacturing trial protocols, shelf-life validation, and go-to-market sequencing.
Practical recommendations for 2026 decision cycles
-
Prioritize pilots that capture the full supply chain cost-to-serve: packaging material, filling-line availability, logistics, and EPR cost exposure. Small-format pilots can reveal hidden unit-economics advantages or scale constraints.
-
Negotiate flexible contracts with material suppliers that include indexed pricing clauses and options for recycled-content substitutes to mitigate mid-cycle price shocks.
-
Integrate regulatory impact as a first-order input to product design: designs that minimize mixed-material laminates and increase fiber content can materially reduce compliance and end-of-life liabilities.
-
Leverage co-manufacturer partnerships for speed-to-market while maintaining control over specification and quality through targeted service-level agreements and performance KPIs.
-
For investors: focus on converter technologies and niche co-packers with demonstrated capability to scale small-format, retort-compatible lines—these assets can command premium multiples in a concentrated market.
Our disclosure policy — the trailer principle
In line with our “trailer” approach, this article surfaces the high-confidence, strategic conclusions and the proprietary frameworks that support them. To preserve the commercial value of the granular segmentation, geographic and application splits, and the detailed supplier scorecards that underpin our investment templates, those tables and model files are omitted here and reserved for the full report and licensed client deliverables.
Next steps
For teams preparing 2026 budgets and strategic roadmaps, the PW Consulting Worldwide Retort Cartons Market report is designed as an operational playbook: it translates market forecasts into supplier shortlists, capex implications, compliance timelines, and go-to-market pilots. To obtain the full report, proprietary worksheets, and an executive briefing tailored to your company’s role in the value chain, please contact PW Consulting or visit our report page for licensing and advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Retort Cartons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Metal Cutting Gas Market to Hit USD 4,850 Million in 2025, Poised for 5.4% CAGR Through 2026–2032 as Asia‑Pacific Leads with USD 2,127.3M
By pmarketresearch, 2026-08-12
Worldwide Metal Cutting Gas Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market intelligence on the Worldwide Metal Cutting Gas Market delivers a compact, strategy-first briefing intended to shape executive choices in 2026. Built on a rigorous historical base (2020–2025) and a forward-looking forecast window (2026–2032), the study models market dynamics that will matter to procurement heads, operations leaders, product strategists, and investors. Our core macro findings: the market stood at approximately USD 4,850 million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 5.4% across the 2026–2032 forecasting horizon, moving toward a multi‑billion USD endpoint by the early 2030s.
DC Secondary Power Distribution Unit (SPDU) Market
Why this report is a 2026 strategic must-have
-
Actionable topline trajectory: The moderate, consistent CAGR gives firms a planning baseline for procurement, inventory and capex decisions. Where many commodity markets are either highly volatile or flat, metal-cutting gases present a predictable secular growth that supports disciplined capacity planning and multi-year contracting.
Biofouling Management Service Market -
Concentration and competitive context: Market concentration is meaningful but not dominant—our concentration analysis shows the top three suppliers control a significant minority share while the top five consolidate a clear majority position. That structure leaves room for regional champions and technology-specialist entrants to pursue carve‑outs, partnerships and differentiated service models.
Household Copper Wire Market -
Integrated cost and regulation sensitivity: Our cost‑curve and scenario modules quantify how feedstock movements and regulatory actions alter unit economics for end-users and suppliers alike — information that is essential for hedging, pass‑through mechanisms, and contract design in 2026.
Macro forces shaping demand in 2026
Three categories of drivers dominate our strategic view for 2026: industrial production cycles, raw material and logistics cost evolution, and regulatory & trade-policy actions. Across the forecast window, growth in heavy fabrication, ship repair, and general infrastructure will continue to support demand for oxy-fuel and fuel‑gas blends, while the steady uptake of plasma and laser cutting influences gas mix and premium gas requirements.
-
Raw-material and price signals: Fuel and feedstock pricing is a first‑order input to gas economics. Recent regional data show upward pressure on acetylene pricing in Europe and a material increment in North America — changes that translate rapidly into operating cost variations for fabricators and repair yards. Our sensitivity analytics demonstrate the impact of a range of plausible price paths on supplier margins, contract pass‑through, and customer break‑even points for alternative cutting technologies.
-
Regulatory and trade dynamics: Policy developments in 2026 — including restructured import measures on finished metal products and ongoing U.S. emissions/hazardous material standards — will shift cost bases and compliance burdens across the supply chain. Transportation and hazardous‑materials oversight for compressed gases continues to tighten, raising the cost of logistics and safety compliance for both commodity and specialty gas distribution.
-
Technological composition: The adoption rate of high‑precision cutting methods (e.g., laser) and specialty fuel blends for efficiency gains is uneven regionally. The interplay between technology substitution and price volatility creates pockets of accelerated spend on premium gases versus destinations where the market retains oxy‑fuel dominance.
Practical contents you’ll find in the full report
PW Consulting’s full study is designed as a decision toolkit rather than a pure academic exercise. Highlights include:
-
Consolidated market model: A bottoms‑up market-sizing model with base-year calibration and scenario blades for demand under alternative macro and trade assumptions.
-
Supplier benchmarking: A strategic evaluation of global and regional suppliers (product breadth, channel models, asset footprint, technology capabilities, and commercial levers) that enables quick identification of likely alliance and acquisition targets.
-
Price and cost sensitivity matrices: Unit‑cost decomposition for prevalent gas types, transport and cylinder economics, and pass‑through timelines for corporate procurement playbooks.
-
Regulatory and logistics impact maps: Country‑level flags for compliance risk and logistics complexity, including hazardous‑materials transportation oversight and emissions frameworks critical to facilities planning.
-
Commercial playbooks: Negotiation pathways, contract templates for fixed vs. index-linked pricing, and inventory strategies tailored to different buyer archetypes (high-volume fabricators, shipyards, scattered contractor networks).
-
M&A and partnering scorecards: Prioritized target lists and valuation heuristics for buyers seeking inorganic growth or bolt‑on capabilities in specialty blends and equipment integrations.
Competitive landscape — who matters and why
The metal cutting gas market balances global, integrated industrial gas majors with regionally focused suppliers and equipment/consumables specialists. Understanding the strategic posture of these players is essential for competitive intelligence and partnership design.
-
Linde plc — a global leader with an expansive product portfolio and logistic reach. Linde’s end‑to‑end capabilities in industrial gases and mixtures make it a preferred supplier for large fabrication networks; its strength is breadth and systems integration across oxy‑fuel, plasma and laser applications.
-
Air Liquide S.A. — notable for technology-enabled solutions and R&D in specialty blends. Air Liquide’s solutions focus aligns well with manufacturers seeking efficiency or emissions performance gains through optimized gas formulations.
-
Air Products and Chemicals, Inc. — leverages proprietary gas formulations and project delivery capability, including branded propylene-based gases for cutting. Their commercial model favors integrated project and long-term supply agreements.
-
Messer SE & Co. KGaA — strong in Europe with growing international operations; Messer competes on tailored regional service models and European supply chain excellence.
-
TotalEnergies SE — oil & gas majors bring supply security on fuel gases and the capability to scale flowable LPG‑based products for industrial cutting at competitive cost points.
-
Indian Oil, Bharat Petroleum — Indian incumbents are significant in their home markets, supplying LPG‑derived cutting gases engineered for local manufacturing intensity and price sensitivity; these players also represent important partners for export-oriented fabricators in South Asia.
-
Regional and specialist players — Brothers Gas, NISSAN TANAKA CORPORATION, ESAB and others offer localized distribution, equipment integration, and consumables ecosystems that are often decisive in retrofit and maintenance categories.
Strategic implications for 2026 planning horizons
Executives should translate the report’s findings into concrete actions that balance near-term resilience and medium-term positioning:
-
Procurement optimization: Move from single-year spot buying toward blended contracts that combine fixed volumes with indexed tranches. Our playbook quantifies the breakpoints where index linkage outperforms fixed pricing under several realistic acetylene and LPG price paths.
-
Supply‑chain resilience: Prioritize dual‑sourcing and regional inventory buffers for hazardous‑material lines, particularly where transport regulation and safety upgrades materially increase movement costs.
-
Technology investment sequencing: Use supplier scorecards to determine where investing in plasma or laser conversion yields a favorable payback under your projected fuel price curve versus sticking with oxy‑fuel solutions.
-
M&A and partnership filters: For companies seeking consolidation or capability extension, target profiles include specialty‑blend formulating capability, cylinder and refill network assets, or equipment integration businesses that enhance margin capture.
-
Regulatory readiness: Build compliance roadmaps aligned with tightened hazardous materials transport oversight and sector emissions standards. This is a small but accelerating cost line that affects both distributors and end‑users.
Selected industry signals (what to watch in 2026)
-
Acetylene pricing: Recent regional observations signal rising input costs in Europe (price pressure tied to feedstock) and notable increases in North America. These moves materially affect oxy‑fuel economics and are a leading indicator for buyer negotiations and technology substitution rates.
-
Tariff and trade policy shifts: Changes to import measures on metal products can alter local fabrication economics and therefore regional gas demand. Supply planners should scenario‑test tariff adjustments in near‑term demand planning.
-
Transportation and safety regulation: Ongoing regulatory scrutiny of compressed gas logistics and hazardous material handling is likely to add compliance and capex requirements for distribution networks.
A final word on the release format
This briefing intentionally showcases the strategic depth and practical frameworks in PW Consulting’s Worldwide Metal Cutting Gas Market study while withholding granular regional and application‑level splits to preserve the executive value of the complete dataset. Subscribers to the full report receive the complete breakout tables, downloadable models, and supplier-level scorecards that underpin the recommendations summarized above.
For procurement directors, plant operations leads, strategy teams and investors preparing for 2026, the full report delivers the calibrated inputs and playbooks required to convert market intelligence into decisive actions. Contact PW Consulting’s research team to access the full dataset, models, and a tailored briefing for your organization’s decision timetable.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com