

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Elemental Fluorine Market to Grow at 6.18% CAGR from USD 928.5M in 2025 to USD 1.41B by 2032 as Asia‑Pacific Leads with USD 443.2M (Top 3 Hold 64.2%)

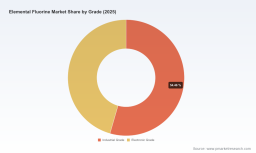
Worldwide Elemental Fluorine Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest market research on the Worldwide Elemental Fluorine Market crystallizes why 2026 is a pivotal year for industrial players, capital allocators, and public-sector stakeholders. Grounded in a detailed five‑year historical analysis (2020–2025) and a rigorous forecast through 2032, the study synthesizes market-scale dynamics, regulatory pressure points, supply‑chain fragility, and competitive positioning into an actionable strategic playbook. The market base year is 2025 (USD, revenue unit: Million) and the forecast covers 2026–2032; compound annual growth is modeled at 6.18% across the outlook horizon.
Worldwide Receiving and Tracking Software Market
Why this report matters for 2026
-
Timing of critical choices: As companies finalize capital expenditure plans and long‑term supply agreements for the period 2026–2029, small differences in risk assessment will determine who secures low‑cost feedstock and who bears elevated transport and compliance premiums.
Robotics for K-12 Education Market -
Market momentum and volatility: After a trough and recovery cycle during 2020–2025, the market reached an elevated baseline in 2025 (USD 928.5 Million). Our scenario models show the market returning to steady expansion through 2032, with the base case projecting a market approaching the USD 1.4 billion range by the end of the forecast period—an outcome that materially changes capital allocation calculus for downstream users.
Porous Tantalum Market -
Concentration and bargaining power: The market exhibits pronounced concentration among a handful of suppliers. The top three firms account for a clear majority of supply and the top five extend that concentration materially, which has immediate implications for counterparty risk, negotiation leverage, and M&A rationale.
Market dynamics: supply, cost, and regulation
-
Feedstock pressure and cost pass‑through: Raw material availability and feedstock pricing remain the principal near‑term cost drivers for elemental fluorine producers. Tightness in fluorspar channels and periodic spikes in anhydrous hydrogen fluoride pricing have amplified margins for integrated suppliers while compressing margins for merchant specialists. These dynamics are decisive for producers that lack vertically integrated upstream feedstock.
-
Transportation and classification friction: Elemental fluorine’s hazardous classification imposes specialized transport protocols, which elevates logistics complexity and episodic freight premiums. Companies that have pre‑certified global logistics chains maintain differentiated delivery reliability—an important competitive moat for semiconductor and nuclear end users with low tolerance for interruption.
-
Regulatory tightening: Across major regulatory jurisdictions there is sustained scrutiny of fluorine‑related chemistry. Authorization regimes and persistent reviews of industrial uses create multi‑year compliance lead times. Firms that have mapped regulatory pathways and embedded compliance contingencies into product roadmaps will face lower program risk in 2026 and beyond.
-
Geopolitical concentration risk: Global fluorspar sourcing remains regionally concentrated. Export policy shifts and quota adjustments in primary producing nations create asymmetric supply shocks, which cascade into HF and F2 availability. Portfolio diversification of sourcing is therefore a second‑order strategic imperative for risk‑averse purchasers.
Competitive landscape — what the market structure means for strategy
-
Incumbents with integrated footprints: Established suppliers such as Air Products and Chemicals, Inc. and Solvay SA benefit from broad downstream customer footprints and, in several cases, vertically integrated feedstock access. Their scale delivers contract flexibility and prioritized capacity allocation for strategic customers.
-
Specialist producers: Players focused on dedicated elemental fluorine production—represented by regional champions—offer high‑purity grades and niche service models (e.g., cylinder management, on‑site delivery), making them indispensable to sensitive end markets such as uranium enrichment and advanced semiconductor etching.
-
High‑value differentiation: Japanese manufacturers and other technology‑oriented suppliers concentrate on ultra‑high purity and closed‑loop quality systems that command premium pricing in semiconductor and advanced materials applications. These firms derive much of their competitive advantage from intellectual property, process control, and tight customer partnerships.
-
Recent disruptions underscore fragility: Public episodes, including force majeure events at major fluorochemical facilities and capacity restarts at dedicated producers, have intermittently removed material supply from the market. These incidents amplified spot volatility and demonstrate why multi‑sourcing and buffer inventory strategies remain defensive necessities.
What our report delivers (practical, decision‑oriented contents)
-
Executive decision maps: Rapid‑read frameworks that translate market scenarios into prioritized actions for procurement, supply‑chain, and R&D leaders over 12–36 month timeframes.
-
Supply‑risk matrix and hedging playbook: Granular supplier risk scoring, contingency pathways (contractual and operational), and recommended inventory buffers calibrated to supplier concentration and transport constraints.
-
Regulatory navigation kit: Jurisdictional trackers, compliance timelines, and authorization templates that shorten review cycles for industrial uses, with sensitivity analysis for potential REACH‑style outcomes and transport rule changes.
-
CapEx and investment modeling: Scenario‑based NPV and IRR outputs for brownfield debottlenecking versus greenfield capacity, incorporating realistic feedstock and logistics cost trajectories under several commodity price regimes.
-
Go‑to‑market and partnership archetypes: Commercial models for incumbents and new entrants—ranging from toll‑manufacturing contracts to long‑term offtake agreements and technology licensing—mapped to buyer willingness to pay and service requirements.
-
Operational playbooks for purity‑sensitive buyers: Quality assurance protocols, cylinder management practices, and emergency substitution guidance when transitioning between grades or suppliers while protecting process yields.
Strategic recommendations for organizations preparing decisions in 2026
-
Prioritize resiliency over lowest‑cost sourcing: Given supplier concentration and episodic upstream disruption, firms whose procurement strategies emphasize resilience (multi‑tier sourcing, strategic inventory) will outperform purely price‑focused peers on continuity and total cost of ownership.
-
Lock in strategic partnerships with tier‑one suppliers: For semiconductor fabs and nuclear fuel processors where supply interruption is existential, negotiating priority allocation clauses and shared investment into capacity expansion are high‑leverage moves in 2026 discussions.
-
Invest in regulatory intelligence and compliance readiness: Anticipate multi‑year lead times for authorization processes; accelerating dossier preparation and early regulator engagement materially reduces commercialization risk for new uses or reformulated chemistries.
-
Model capex under multiple commodity regimes: When evaluating capacity addition, use conservative feedstock price scenarios and include logistics contingency costs; short payback projects and modular debottlenecks often dominate against large greenfield commitments in current market dynamics.
-
Consider strategic M&A or joint ventures to manage concentration risk: For buyers seeking to internalize supply security, carefully structured equity positions in production assets deliver both supply reliability and potential margin capture without full greenfield exposure.
Where the report is intentionally selective — the “trailer” principle
To respect client confidentiality and to preserve the analytical value of the proprietary dataset, this briefing deliberately omits detailed regional/applicational splits and line‑item supplier scorecards. The full report contains exhaustive segmentation models (regional, application, and grade breakdowns), raw supplier benchmarking tables, contract template libraries, and downloadable scenario spreadsheets that decision makers can use directly in procurement negotiations and capital planning. These assets are available on the report landing page.
How senior leaders should use the report in 2026 planning cycles
-
Procurement leaders: Use the supplier risk matrix and the recommended contract clauses to renegotiate terms before renewals come due in 2026–2027.
-
Corporate strategy teams: Incorporate the scenario‑based forecasts and capex models into the company’s three‑year strategic plan and capital allocation playbook.
-
R&D and product teams: Leverage the regulatory navigation kit to prioritize product reformulations that minimize exposure to high‑risk inputs while maintaining performance for demanding end uses.
-
Investors and advisors: Apply our valuation templates to stress‑test portfolio companies exposed to feedstock volatility and to identify defensive investments with outsized optionality in constrained markets.
Concluding perspective
The elemental fluorine market is entering a phase where scale, regulatory fluency, and supply‑chain design will differentiate winners from the rest. With a market that rebounded to a much higher baseline by 2025 and a compound annual growth trajectory of 6.18% through 2032 under our base case, choices made in 2026—about partnerships, capacity, and regulatory positioning—will determine multiyear outcomes. PW Consulting’s report is engineered to convert market intelligence into executable decisions: it surfaces the levers that matter and equips leaders with the tools to act, while retaining the detailed segmentation and supplier analytics behind a secure, subscriber‑level experience.
For access to the full dataset, supplier scorecards, and downloadable scenario models, visit our report landing page to obtain the complete Worldwide Elemental Fluorine Market study and the PW Consulting strategic toolkit for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Elemental Fluorine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com