

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Metal Cutting Gas Market to Hit USD 4,850 Million in 2025, Poised for 5.4% CAGR Through 2026–2032 as Asia‑Pacific Leads with USD 2,127.3M

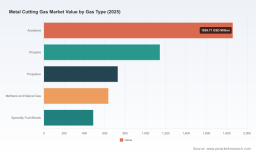
Worldwide Metal Cutting Gas Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market intelligence on the Worldwide Metal Cutting Gas Market delivers a compact, strategy-first briefing intended to shape executive choices in 2026. Built on a rigorous historical base (2020–2025) and a forward-looking forecast window (2026–2032), the study models market dynamics that will matter to procurement heads, operations leaders, product strategists, and investors. Our core macro findings: the market stood at approximately USD 4,850 million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 5.4% across the 2026–2032 forecasting horizon, moving toward a multi‑billion USD endpoint by the early 2030s.
DC Secondary Power Distribution Unit (SPDU) Market
Why this report is a 2026 strategic must-have
-
Actionable topline trajectory: The moderate, consistent CAGR gives firms a planning baseline for procurement, inventory and capex decisions. Where many commodity markets are either highly volatile or flat, metal-cutting gases present a predictable secular growth that supports disciplined capacity planning and multi-year contracting.
Biofouling Management Service Market -
Concentration and competitive context: Market concentration is meaningful but not dominant—our concentration analysis shows the top three suppliers control a significant minority share while the top five consolidate a clear majority position. That structure leaves room for regional champions and technology-specialist entrants to pursue carve‑outs, partnerships and differentiated service models.
Household Copper Wire Market -
Integrated cost and regulation sensitivity: Our cost‑curve and scenario modules quantify how feedstock movements and regulatory actions alter unit economics for end-users and suppliers alike — information that is essential for hedging, pass‑through mechanisms, and contract design in 2026.
Macro forces shaping demand in 2026
Three categories of drivers dominate our strategic view for 2026: industrial production cycles, raw material and logistics cost evolution, and regulatory & trade-policy actions. Across the forecast window, growth in heavy fabrication, ship repair, and general infrastructure will continue to support demand for oxy-fuel and fuel‑gas blends, while the steady uptake of plasma and laser cutting influences gas mix and premium gas requirements.
-
Raw-material and price signals: Fuel and feedstock pricing is a first‑order input to gas economics. Recent regional data show upward pressure on acetylene pricing in Europe and a material increment in North America — changes that translate rapidly into operating cost variations for fabricators and repair yards. Our sensitivity analytics demonstrate the impact of a range of plausible price paths on supplier margins, contract pass‑through, and customer break‑even points for alternative cutting technologies.
-
Regulatory and trade dynamics: Policy developments in 2026 — including restructured import measures on finished metal products and ongoing U.S. emissions/hazardous material standards — will shift cost bases and compliance burdens across the supply chain. Transportation and hazardous‑materials oversight for compressed gases continues to tighten, raising the cost of logistics and safety compliance for both commodity and specialty gas distribution.
-
Technological composition: The adoption rate of high‑precision cutting methods (e.g., laser) and specialty fuel blends for efficiency gains is uneven regionally. The interplay between technology substitution and price volatility creates pockets of accelerated spend on premium gases versus destinations where the market retains oxy‑fuel dominance.
Practical contents you’ll find in the full report
PW Consulting’s full study is designed as a decision toolkit rather than a pure academic exercise. Highlights include:
-
Consolidated market model: A bottoms‑up market-sizing model with base-year calibration and scenario blades for demand under alternative macro and trade assumptions.
-
Supplier benchmarking: A strategic evaluation of global and regional suppliers (product breadth, channel models, asset footprint, technology capabilities, and commercial levers) that enables quick identification of likely alliance and acquisition targets.
-
Price and cost sensitivity matrices: Unit‑cost decomposition for prevalent gas types, transport and cylinder economics, and pass‑through timelines for corporate procurement playbooks.
-
Regulatory and logistics impact maps: Country‑level flags for compliance risk and logistics complexity, including hazardous‑materials transportation oversight and emissions frameworks critical to facilities planning.
-
Commercial playbooks: Negotiation pathways, contract templates for fixed vs. index-linked pricing, and inventory strategies tailored to different buyer archetypes (high-volume fabricators, shipyards, scattered contractor networks).
-
M&A and partnering scorecards: Prioritized target lists and valuation heuristics for buyers seeking inorganic growth or bolt‑on capabilities in specialty blends and equipment integrations.
Competitive landscape — who matters and why
The metal cutting gas market balances global, integrated industrial gas majors with regionally focused suppliers and equipment/consumables specialists. Understanding the strategic posture of these players is essential for competitive intelligence and partnership design.
-
Linde plc — a global leader with an expansive product portfolio and logistic reach. Linde’s end‑to‑end capabilities in industrial gases and mixtures make it a preferred supplier for large fabrication networks; its strength is breadth and systems integration across oxy‑fuel, plasma and laser applications.
-
Air Liquide S.A. — notable for technology-enabled solutions and R&D in specialty blends. Air Liquide’s solutions focus aligns well with manufacturers seeking efficiency or emissions performance gains through optimized gas formulations.
-
Air Products and Chemicals, Inc. — leverages proprietary gas formulations and project delivery capability, including branded propylene-based gases for cutting. Their commercial model favors integrated project and long-term supply agreements.
-
Messer SE & Co. KGaA — strong in Europe with growing international operations; Messer competes on tailored regional service models and European supply chain excellence.
-
TotalEnergies SE — oil & gas majors bring supply security on fuel gases and the capability to scale flowable LPG‑based products for industrial cutting at competitive cost points.
-
Indian Oil, Bharat Petroleum — Indian incumbents are significant in their home markets, supplying LPG‑derived cutting gases engineered for local manufacturing intensity and price sensitivity; these players also represent important partners for export-oriented fabricators in South Asia.
-
Regional and specialist players — Brothers Gas, NISSAN TANAKA CORPORATION, ESAB and others offer localized distribution, equipment integration, and consumables ecosystems that are often decisive in retrofit and maintenance categories.
Strategic implications for 2026 planning horizons
Executives should translate the report’s findings into concrete actions that balance near-term resilience and medium-term positioning:
-
Procurement optimization: Move from single-year spot buying toward blended contracts that combine fixed volumes with indexed tranches. Our playbook quantifies the breakpoints where index linkage outperforms fixed pricing under several realistic acetylene and LPG price paths.
-
Supply‑chain resilience: Prioritize dual‑sourcing and regional inventory buffers for hazardous‑material lines, particularly where transport regulation and safety upgrades materially increase movement costs.
-
Technology investment sequencing: Use supplier scorecards to determine where investing in plasma or laser conversion yields a favorable payback under your projected fuel price curve versus sticking with oxy‑fuel solutions.
-
M&A and partnership filters: For companies seeking consolidation or capability extension, target profiles include specialty‑blend formulating capability, cylinder and refill network assets, or equipment integration businesses that enhance margin capture.
-
Regulatory readiness: Build compliance roadmaps aligned with tightened hazardous materials transport oversight and sector emissions standards. This is a small but accelerating cost line that affects both distributors and end‑users.
Selected industry signals (what to watch in 2026)
-
Acetylene pricing: Recent regional observations signal rising input costs in Europe (price pressure tied to feedstock) and notable increases in North America. These moves materially affect oxy‑fuel economics and are a leading indicator for buyer negotiations and technology substitution rates.
-
Tariff and trade policy shifts: Changes to import measures on metal products can alter local fabrication economics and therefore regional gas demand. Supply planners should scenario‑test tariff adjustments in near‑term demand planning.
-
Transportation and safety regulation: Ongoing regulatory scrutiny of compressed gas logistics and hazardous material handling is likely to add compliance and capex requirements for distribution networks.
A final word on the release format
This briefing intentionally showcases the strategic depth and practical frameworks in PW Consulting’s Worldwide Metal Cutting Gas Market study while withholding granular regional and application‑level splits to preserve the executive value of the complete dataset. Subscribers to the full report receive the complete breakout tables, downloadable models, and supplier-level scorecards that underpin the recommendations summarized above.
For procurement directors, plant operations leads, strategy teams and investors preparing for 2026, the full report delivers the calibrated inputs and playbooks required to convert market intelligence into decisive actions. Contact PW Consulting’s research team to access the full dataset, models, and a tailored briefing for your organization’s decision timetable.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com