

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Inguinal Hernia Repair Mesh Market Valued at USD 4,801 Million in 2025 — Global Forecast to 2032

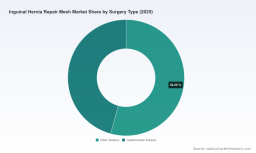
PW Consulting Strategic Brief: Worldwide Inguinal Hernia Repair Mesh Market — Actionable Outlook for 2026 Decision Makers
Executive snapshot
Our Worldwide Inguinal Hernia Repair Mesh Market study (base year 2025; forecast 2026–2032) consolidates five years of historical performance and forward-looking scenario analysis to equip life‑science executives, strategy teams, and investors with the signals they need to act in 2026. The global market is sized at a multi‑billion dollar level in 2025 (USD, revenue basis) and is expected to grow at a compound annual growth rate (CAGR) of 4.8% through the 2026–2032 forecast window. By the end of that horizon the market reaches materially higher scale, driven by a mix of procedure volumes, technology adoption, and product innovation.
Thyristor Dimming Power Supply Market
This brief summarizes the strategic implications we extract from the full report: the economic drivers, regulatory inflection points, competitive positioning, and the go‑to‑market actions that will determine winners and laggards in 2026. In keeping with the “trailer” principle, we demonstrate analytical depth while reserving granular segment tables and region/application line items for the full report—available from our website for clients who require the underlying models and line-by-line forecasts.
Battery Operated Mobile Power Market
What the report delivers — practical components that CFOs and Heads of Product will use in 2026
- Robust market sizing and verified historical demand (2020–2025) plus baseline and alternative scenarios to 2032, enabling stress‑tested revenue planning.
- Scenario‑based financial models that translate procedure throughput, device mix, and pricing pressure into P&L and cash‑flow outcomes; model templates are client‑editable.
- Competitive landscaping and capability mapping: product portfolios, clinical positioning, regulatory status, litigation exposure, and IP/technology adjacencies for the leading players.
- Regulatory and reimbursement tracker with tactical recommendations for label strategy, submission sequencing, and payer evidence requirements in core markets.
- Supply‑chain risk assessment including raw material cost sensitivity, alternative sourcing options, and inventory/hedging playbooks to manage margin contraction.
- Commercial playbooks for hospitals, ambulatory surgical centers (ASCs), and high‑volume specialty practices—covering value‑based contracting, pricing tiers, and adoption levers.
- Deal‑making and partnership framework: prioritized M&A and alliance targets, integration checklists, and waterfall valuation scenarios that reflect market concentration dynamics.
Competitive landscape — who matters and why (high‑level view)
The market shows moderate concentration among a small group of established manufacturers, creating both competitive pressure and pockets of opportunity for differentiation. Our qualitative and quantitative assessment indicates leading incumbents maintain strong distribution, clinical relationships, and breadth of mesh technologies, from traditional polypropylene products to next‑generation bioresorbables and composite constructs.
Worldwide Phone Sanitizer Market
- Becton Dickinson (BD) — Demonstrates a dual strategy of established polypropylene solutions and higher‑value bioresorbable options. The company’s recent Phasix expansion and the January 2026 prophylactic indication milestone in Europe highlight a strategy that pairs product innovation with indication expansion to capture prevention and reinforcement segments.
- Medtronic (Covidien) — Focused on anatomical and laparoscopic‑optimized meshes, including self‑fixating technologies that target minimally invasive workflows. Their product design leverages procedure efficiency and OR time reduction to support adoption in centers performing laparoscopic TAPP/TEP approaches.
- Ethicon (Johnson & Johnson MedTech) — Maintains a strong position with a broad polypropylene portfolio and partially absorbable options that span both open and minimally invasive procedures; this provides pricing and clinical flexibility in hospital negotiations.
- B. Braun (Aesculap) — Competes on differentiated light‑weight meshes and clinician ergonomics, appealing to markets where surgeon preference and handling characteristics drive procurement.
- W. L. Gore & Associates — Offers ePTFE‑based and dual‑surface materials that are positioned around adhesion reduction and specific reconstructive use‑cases where tissue interaction matters most.
- Getinge (Atrium Medical) — A historic synthetic mesh supplier whose product legacy is accompanied by legal and reputational considerations; an important competitor in select markets and a reminder of litigation risk management.
Collectively, the top three and top five competitors account for a meaningful share of market revenue, which reinforces the importance of competitive intelligence and targeted differentiation. The full report includes proprietary heatmaps of R&D focus, go‑to‑market strength, and litigation/reputational exposure for each named company.
Regulatory, reimbursement, and raw‑material dynamics shaping 2026 decisions
- Regulatory: The U.S. FDA’s June 2025 draft guidance on standardized package labeling for hernia mesh devices introduces a new expectation for clinically relevant, consistent instructions and risk communication. Device sponsors should incorporate label harmonization into submission timelines and post‑market surveillance plans; early adoption can become a competitive differentiator in hospital purchasing committees.
- Reimbursement: Updated Medicare coding and payment rules effective January 1, 2026, alter the economics of hernia procedures in core markets. Manufacturers must align their value dossiers and pricing strategies to reflect the new national averages and coding pathways—especially when proposing higher‑priced composite or bioresorbable options.
- Raw materials: Medical‑grade polypropylene prices have risen substantially since 2021 (exceeding a 35% increase and reaching roughly $1,700 per metric tonne in 2024), exerting upward pressure on manufacturing costs. This dynamic necessitates margin protection strategies—contract renegotiation, formula optimization, and selective cost pass‑through tactics.
Strategic imperatives for 2026 — recommended actions
Companies should translate these market signals into a compact set of executable initiatives with defined owners and timelines. Our priority recommendations for 2026 are:
- Regulatory readiness and labeling playbook — Treat the FDA labeling guidance as a product launch enabler. Prepare harmonized global labels and accompanying clinician education packages to shorten adoption cycles in hospitals and ASCs.
- Portfolio prioritization — Run a rapid, economics‑based ranking of SKUs (clinical value × margin × addressable volume). De‑list or divest low‑margin, low‑share SKUs; reinvest in higher‑margin products supported by clear clinical outcomes evidence.
- Evidence‑to‑value investments — Target limited, pragmatic clinical studies (real‑world evidence and registry linkages) that close payer and surgeon evidence gaps—especially for prophylactic and bioresorbable propositions.
- Supply‑chain hedging and design substitutes — Lock multi‑year supply agreements, qualify alternate polymer sources, and accelerate development of lower‑polypropylene‑content constructs where clinically justified.
- Channel and contracting segmentation — Differentiate strategies across hospitals, ASCs, and high‑volume specialty clinics. For ASCs, emphasize procedure efficiency and bundled pricing; for hospitals, focus on value dossiers tied to long‑term outcomes and readmission reductions.
- M&A and partnerships — Pursue tuck‑ins that add differentiated materials or evidence capabilities; avoid targets with unmanaged litigation risk. Use our deal‑screening matrix to prioritize targets that accelerate time‑to‑market or broaden digital/clinical services.
- Commercial KPI dashboard — Implement a concise dashboard for 2026 with leading indicators (OR adoption rates, average selling price by channel, hospital conversion time, inventory days) tied to monthly review cadence between commercial and supply functions.
How PW Consulting supports 2026 execution
Our report is designed as both an analytical product and a practical toolset. For executive teams seeking immediate traction, we offer:
- Board‑level briefings that translate the 4.8% CAGR baseline and scenario outcomes into clear revenue and margin implications for 2026 planning cycles.
- Customized commercial playbooks by country cluster, including contract templates, pricing negotiation scripts, and hospital stakeholder maps.
- Due diligence packages for M&A that combine our financial model, litigation risk checklist, and integration‑ready commercial roadmaps.
- Supply‑chain stress tests and hedging strategies to isolate the impact of raw material price swings on gross margins and working capital.
We intentionally preserve the granular regional, product‑type, and end‑user line items within the full report to ensure clients receive the underlying data models and proprietary assumptions that support executive decisions. If you are planning budget allocations, product portfolio rationalization, or M&A activity in 2026, those detailed micro‑splits and scenario model files will materially shorten your runway from decision to execution.
Next steps
For companies preparing 2026 strategy cycles, the combination of a mid‑single‑digit growth baseline, evolving regulatory expectations, rising raw‑material input costs, and a moderately concentrated competitive set creates a narrow window to reposition. PW Consulting’s full Worldwide Inguinal Hernia Repair Mesh Market report contains the granular forecasts, sensitivity analyses, and executable playbooks required to make defensible, high‑velocity decisions.
Contact our advisory team to arrange a tailored briefing or to license the full dataset and model. Our clients use these deliverables to accelerate go‑to‑market decisions, de‑risk sourcing strategies, and prioritize clinical investments—so they can convert market signals into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Inguinal Hernia Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com