

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Integral Waterproofing Compound Market Set to Grow at a 5.28% CAGR Through 2032, PW Consulting Reports

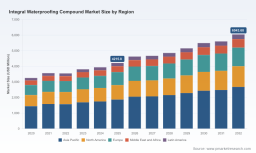
PW Consulting: Strategic Preview — Worldwide Integral Waterproofing Compound Market (2026 Outlook)
PW Consulting today publishes a strategic preview of our upcoming market research release on the Worldwide Integral Waterproofing Compound market. Built from a base year of 2025 and covering a forecast window through 2032, the study demonstrates that the sector is on a sustained growth path — with the global market sized at approximately USD 4,215.8 Million in 2025 and an expected near-term step to roughly USD 4,628.5 Million in 2026, driven by an average compound annual growth rate of 5.28% across the forecast period. For senior executives preparing budgets, product roadmaps and M&A pipelines in 2026, this research serves as a practical, decision-grade briefing: it translates macro momentum into the operational choices that will define winners and laggards in the coming planning cycle.
One-Arm Bandit Market
Why this report matters to 2026 decision-making
-
From procurement to product management, organizations need a clear line of sight on how demand and cost dynamics interact. Our modelling integrates recent volatility in key feedstocks and their pass-through to finished-product economics, enabling finance and commercial teams to build defensible price and margin scenarios into 2026 planning cycles.
Worldwide Anisotropic Conductive Film (ACF) Tape Market -
Regulatory and sustainability imperatives are shifting formulary priorities. The report maps how low-VOC and bio-based chemistries are moving from niche green credits to procurement preconditions in major infrastructure and commercial tenders — a shift that has direct implications for R&D allocation and go-to-market timing in 2026.
Wire Beam LiDAR Market -
Competitive positioning is fragmenting in ways that favor both scale and specialization. We provide a pragmatic playbook for players at every point on the value chain — raw material suppliers, admixture formulators, ready-mix partners, and contractors — to convert market signals into concrete near-term actions (product launches, distribution pivots, and targeted partnerships).
What the report contains — practical deliverables
-
Decision-ready market sizing and trend analysis calibrated to 2025 base values and extended through 2032, including sensitivity runs for cost and demand shocks relevant to 2026 budgeting cycles.
-
An operational segmentation framework that supports SKU-level portfolio prioritization, build-or-buy tradeoffs, and channel investment sequencing. (Note: this public summary intentionally omits the detailed segment tables and breakouts; the full dataset and downloadable models are included in the paid report.)
-
Supply-chain and cost models that quantify the impact of raw material volatility and energy cost shifts on margin profiles, with recommended hedging and contract structures tailored to admixture chemistries.
-
Competitive benchmarking and capability heat maps covering leading global and regional players, plus an M&A screening tool that ranks strategic targets against capability gaps and route-to-market objectives.
-
Implementation playbooks: pilot design templates, specification checklists for procurement teams, and KPIs for post-deployment performance validation in both ready-mix and in-situ concrete applications.
-
Regulatory and sustainability roadmaps explaining how green building programs and evolving low-emission standards will impact product acceptance and tender scoring in major markets.
Competitive landscape — synthesized insights for 2026 strategy
The market structure is neither a pure oligopoly nor highly atomized: our concentration metrics indicate a moderate level of aggregation among the largest players, leaving significant runway for specialized entrants and regional champions. The following high-level assessment of incumbent and emerging competitors is designed to support comparative strategy discussions; the report contains in-depth profiles, primary interview excerpts, and technology-readiness assessments.
-
Sika AG (Baar, Switzerland) — A leading global construction chemicals player with an extensive integral admixture portfolio and deep historic expertise. Sika’s strength lies in broad channel coverage and integrated systems sales; for 2026, their playbook is likely to emphasize bundle selling (admixtures + system warranties) and leveraging global R&D platforms to accelerate low-VOC variants.
-
Kryton International Inc. (Vancouver, Canada) — A specialist in crystalline technologies with differentiated claims around internal membrane functionality and self-healing performance. Kryton represents the archetype for technology-led premiumization, attractive to infrastructure projects requiring lifecycle performance assurances.
-
Xypex Chemical Corporation (Richmond, Canada) — Another crystalline-focused incumbent that emphasizes the integrality of treatment into the concrete matrix rather than surface membranes; Xypex’s strength is brand association with “spec-grade” durability, making it a frequent choice on projects where performance risk is price-insensitive.
-
The Euclid Chemical Company (Cleveland, USA) — With long-standing product lines in stearate-based and powdered internal repellents, Euclid exemplifies channel-facing product strategy, focusing on contractor ease-of-use and compatibility with U.S. ready-mix practices.
-
Anti-Hydro International (USA) — A heritage player with a century-long market presence; their value is in trust and tried-and-tested formulations, especially in renovation and masonry segments where specification inertia matters.
-
Pioneer Fibre / Pioneer (Hong Kong) — A regional system supplier with executional experience on major bridges and tunnels; represents the commercial case for coupling admixture capability with local construction services and project delivery teams across Asia.
-
Chem Concrete Pty Ltd (Australia) — Offers a patented hybrid admixture that blends densifiers, pore blockers and nano-scale treatments — an example of the disruptive NPI that can command premium pricing and long-term warranties where clients value lifecycle cost reductions.
-
BASF SE (Ludwigshafen, Germany) — Through its construction chemicals division, BASF brings scale R&D and a global distribution footprint. Its strength lies in enabling compatibility with supplementary cementitious materials and downstream co-marketing with complementary construction chemistries.
-
Mapei SpA (Milan, Italy) — A broad-based admixture house with product families tuned for European specifications; MAPEI is typically strong in high-spec commercial and renovation segments where product-system certification matters.
-
Fosroc International (Dubai, UAE) — A major regional player with solutions tailored for Middle East climates and construction practices; Fosroc’s route-to-market advantages stem from regional logistics, specification influence and contractor relationships.
-
Pidilite Industries Ltd. (Mumbai, India) — Represents the scale low-cost play in Asia, backed by deep distributor networks and local formulation expertise; Pidilite is a candidate for rapid share expansion where price sensitivity dominates.
-
Penetron International Ltd. (USA) — Known for crystalline systems focused on long-term durability; Penetron appeals to owners seeking single-source warranty propositions and is a frequent name on high-risk below-grade structures.
Industry dynamics that will dominate 2026 planning
-
Raw material volatility — Energy-driven shifts and chemical supply disruptions have periodically increased costs for critical inputs. Finance teams should embed stress-tests and raw-material passthrough clauses into long-term contracts to protect margin in 2026 forecasts.
-
Regulatory and green-building pressure — Low-VOC and bio-derived hydrophobic chemistries are moving from preferential scoring to procurement requirements in many institutional tenders. Product roadmaps that prioritize these chemistries will face less tender friction and higher specification uptake.
-
Channel and procurement evolution — Automated dosing at ready-mix plants and integration with supplementary cementitious materials are reshaping product form-preference. Manufacturers need manufacturing and logistics adaptations to capture growth where volumetric dosing is the norm.
-
Product premiumization vs. commoditization — The market bifurcates between low-cost hydrophobic powders and higher-value crystalline or hybrid systems. Strategy choices in 2026 should explicitly pick a lane — scale-volume or performance-premium — and align R&D, pricing and service models accordingly.
Recommended near-term actions for executives
-
Prioritize formulation investments that meet low-VOC requirements and certify to common green-building standards; this reduces tender friction and can justify price premiums.
-
Implement procurement frameworks that include raw-material indexation clauses and strategic supplier partnerships to reduce exposure to input-cost shocks.
-
Test premium hybrid admixtures on pilot infrastructure projects where lifecycle cost analysis can validate higher margin positioning and warranty commitments.
-
Expand technical services and specification support as a differentiator: warranty-backed systems and strong field support shorten sales cycles with institutional buyers.
-
Use the report’s M&A screening output to identify bolt-on targets that fill capability gaps (e.g., crystalline know-how, regional distribution, or complementary polymer chemistry).
Risk scenarios we modelled
-
Raw-material price shock: an input-cost spike that compresses margins for commodity players and accelerates consolidation.
-
Regulatory tightening: accelerated adoption of bio-derived agents that renders older solvent-based formulations commercially disadvantaged in major tenders.
-
Channel disruption: rapid automation of ready-mix plants, favoring liquid admixtures and penalizing powder-centric supply chains lacking packaging/logistics scale.
PW Consulting’s Worldwide Integral Waterproofing Compound Market report is intentionally structured to be a practical tool for the 2026 planning cycle: it offers not only directional market intelligence but also executable plans, contract language templates, and pilot ROI models. This preview demonstrates the report’s strategic value while preserving the granular segment and financial tables to encourage direct access to the full dataset.
To access the complete dataset, modelling templates, and company dossiers that underpin the recommendations above, please refer to the full PW Consulting report and dataset available through our client portal. PW Consulting’s advisors are available to present tailored briefings and to run enterprise-specific scenario workshops to operationalize the findings for your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Integral Waterproofing Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com