

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Rapid Expansion of Worldwide Foot Traffic & Customer Location Intelligence Market with 15.65% CAGR

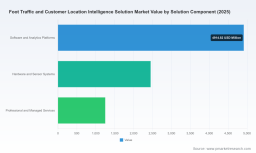
Worldwide Foot Traffic and Customer Location Intelligence Solution Market — Strategic Imperatives for 2026
PW Consulting is pleased to release an executive briefing drawn from our new market research, Worldwide Foot Traffic and Customer Location Intelligence Solution Market. As organizations plan budgets and strategy for 2026, this briefing highlights the commercial and operational levers that will determine winners and laggards in the era where physical places are instrumented, and location data becomes a strategic asset. The full report delivers the granular inputs, vendor scorecards, and datasets that enterprise leaders and investors need; this release serves as a high-fidelity preview of the report’s strategic value while reserving the proprietary segment-level details for subscribers.
Worldwide Anime Peripheral Market
Market trajectory and what it signals for 2026 decisions
The market for foot traffic and customer location intelligence has evolved from an emerging analytics niche into a mainstream technology stack. Our analysis shows the total addressable market growing materially during the early 2020s, with a pronounced acceleration into 2025 driven by renewed investments in physical retail analytics, smart building deployments, transportation optimization, and location-aware marketing. The market’s momentum continues: the forecast period beginning in 2026 assumes a robust compound annual growth rate (CAGR) of 15.65%, reflecting a combination of higher enterprise adoption, AI-driven analytics maturation, and new data fusion architectures that link mobile, sensor, and video sources.
Adaptable Accelerator Cards Market
For C-suite leaders planning 2026 spends, the message is straightforward: this is no longer an experimental line item. Location intelligence solutions will increasingly be interpreted as strategic infrastructure—analogous to CRM or ERP—because they directly inform site strategy, customer acquisition and retention, operational staffing, and property valuation. Firms that treat location intelligence as tactical will risk inefficient capital allocation and missed revenue uplift.
Electric 3 Wheel Forklift Truck Market
What the report provides (practical, operational content)
- Actionable vendor selection frameworks that prioritize data provenance, model explainability, update cadence, and API interoperability.
- Implementation blueprints for hybrid data architectures (edge sensors + centralized analytics), including reference hardware topologies, privacy-preserving ingestion pipelines, and integration patterns with POS, CRM, and digital ad stacks.
- ROI and TCO models tailored to common enterprise use cases—site selection, trade-area cannibalization analysis, marketing attribution, labor optimization, and asset-level valuation—enabling finance teams to stress-test investment cases.
- Data governance and compliance playbooks: practical approaches for data minimization, differential privacy, sovereign storage options, and contractual clauses to mitigate legal exposure in multi-jurisdiction deployments.
- Operational checklists and KPIs for pilot-to-scale transitions, including sample SLAs for data freshness and accuracy, sample RFP language, and vendor negotiation levers.
- Case studies and “war stories” from real-world deployments that surface common failure modes and the remediation steps that saved projects from under-delivering.
Technology realities and integration trade-offs
The ecosystem is technologically heterogeneous. Wi‑Fi and Bluetooth/BLE systems offer high-frequency, low-cost presence signals; GPS and satellite positioning provide coarse-grain outdoor traces; AI-based video analytics deliver higher-fidelity in-store behavioral insights; and infrared/thermal sensors enable anonymous counting in privacy-sensitive environments. The strategic choice is rarely binary. Instead, winning implementations are multi-modal: they fuse multiple sensor classes to raise signal-to-noise, compensate for coverage gaps, and provide layered attestations of the same event.
Key technical decisions for 2026 include where to place compute (edge vs. cloud), how to design resilient data pipelines, and how to implement privacy-preserving techniques without destroying business value. Increasingly important are data quality metrics—refresh intervals, dropout rates, and source lineage—because analytics outcomes are only as defensible as the inputs. Another emergent consideration is spectrum management for wireless sensors. Ongoing regulatory and standards discussions around spectrum sharing and AI-enabled spectrum utilization will influence hardware selection and deployment cadence in the coming 18–24 months.
Regulation and data sovereignty — design constraints that matter
Regulatory dynamics are no longer peripheral. Data sovereignty regimes are forcing providers and customers to rethink architectures, particularly where local laws mandate the storage or processing of raw location signals within national borders. At the same time, extraterritorial access regimes—such as provisions that permit access to data held by companies under certain jurisdictions—create compliance risks for multinational deployments. Enterprises must bake these considerations into procurement and legal documentation: contractual data residency guarantees, clear incident response processes, and the option to operate in “local-only” modes where required.
Competitive landscape: segmentation by capability and go-to-market
The market exhibits moderate concentration: a handful of vendors lead with broad platform capabilities while a larger group of specialists address vertical or technical niches. Market concentration metrics underscore this balance—there is leadership visibility, but also ample room for new entrants and strategic partnerships.
- Platform-first companies (example profiles): Firms that aggregate large-scale anonymized mobility footprints and expose analytics via SaaS APIs. They excel at cross-property comparisons, trend analysis, and site selection analytics.
- Mapping and GIS stalwarts: Companies with deep cartographic and spatial modeling expertise that bring strength in routing, spatial analytics, and enterprise GIS integrations—useful for municipal and infrastructure use cases.
- Sensor and in-store specialists: Vendors that supply people counters, camera-based analytics, and edge devices optimized for in-store conversion and queue management.
- Data suppliers and aggregators: Organizations that focus on raw mobility or POI datasets, enabling downstream analytics firms and internal data teams to build bespoke models.
Strategically, this stratification produces three repeatable vendor archetypes enterprises will encounter: (1) full-stack platforms that bundle data, analytics, and dashboards; (2) best-of-breed analytics vendors that prioritize model quality and APIs; and (3) hardware-oriented suppliers who increasingly pair sensors with software services. Our vendor benchmarking highlights not only capability differentials, but also differences in contract models, privacy practices, and service maturity.
Recent market signals and vendor moves (what to watch in early 2026)
- Thought leadership and market education activities are intensifying—vendors are investing in education to move buyers up the value curve (for example, recent webinars aimed at economic developers and retail real estate audiences).
- Strategic integrations between location analytics providers and commercial real estate platforms have emerged, signaling faster adoption among institutional investors and REITs that want asset-level consumer behavior inputs.
- Product enhancements focused on site selection, cannibalization modeling, and trade-area overlap demonstrate that vendors are migrating from descriptive metrics to predictive tools that drive capital allocation decisions.
Five strategic imperatives for enterprise leaders in 2026
- Adopt a hybrid data strategy: combine mobile, sensor, and video-derived signals to increase robustness and reduce single-source risk.
- Prioritize privacy and sovereignty in procurement: demand technical and contractual support for localized processing and demonstrable privacy-enhancing measures.
- Measure and operationalize: shift from vanity metrics (raw counts) to operational KPIs tied to revenue, cost, or asset valuation—define success metrics before vendor selection.
- Architect for modularity: prefer vendors that expose APIs and allow you to replace components without a forklift migration; this lowers switching costs as the market consolidates.
- Insist on clear SLAs and data lineage: accuracy, freshness, and provenance matter for high-stakes uses such as valuations or regulatory reporting.
Investment and partnership lens
For investors and strategic partners, the macro dynamics are compelling. The market’s expansion, combined with an ecosystem that mixes incumbents with nimble specialists, creates opportunities for both platform consolidation and vertical specialization plays. Key diligence areas are recurring revenue quality, customer retention on multi-year contracts, margin profiles across hardware/software/services bundles, and regulatory exposure across key operating geographies.
What the full PW Consulting report includes (and why you should read it)
The full report contains the detailed forecasts (covering 2026–2032), vendor profiles with capability matrices, use-case economic models, procurement templates, and the raw datasets that informed our market sizing and growth assumptions. It also provides a scenario analysis that maps regulatory and technology shocks to demand outcomes so decision makers can build contingency plans into 2026 budgets.
We intentionally keep this release a strategic preview. The core, segment-level insights and the proprietary dashboards that enable point-by-point comparison of vendors and use cases are available in the full report. Executives and investors who need to make procurement, partnership, or M&A decisions in 2026 should consult the report to access the detailed metrics and supplier scorecards that drive defensible choices.
PW Consulting’s Worldwide Foot Traffic and Customer Location Intelligence Solution Market research is built for leaders who must translate location signals into strategic advantage. To obtain the full report, vendor scorecards, and the interactive forecast models, please visit our website or contact the PW Consulting research desk for enterprise access and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com