

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Biogas Market Hits $63.48B in 2025, Projected to Reach $90.82B by 2032 at 5.27% CAGR
By pmarketresearch, 2026-09-15
Navigating the Biogas Transition: Strategic Intelligence for 2026 and Beyond
The global energy landscape is undergoing a structural shift, driven by decarbonization mandates and the urgent need for sustainable waste management solutions. At the heart of this transformation is the biogas sector, a market that has evolved from a niche renewable energy source into a critical component of the circular economy. For corporate strategists, investors, and policymakers, understanding the trajectory of this market is no longer optional it is a prerequisite for resilient decision-making.
PW Consulting is pleased to introduce our latest comprehensive market research, designed specifically to equip stakeholders with the actionable intelligence needed to navigate the complexities of 2026 and the subsequent seven-year forecast period. This report moves beyond surface-level headlines to deliver a granular analysis of market dynamics, competitive positioning, and risk factors that define the current operational environment.
As we enter a new fiscal year, the decisions made today regarding asset allocation, supply chain partnerships, and technology adoption will dictate competitive advantage for the remainder of the decade. The following analysis outlines the macro-economic context and the strategic value embedded within this new research publication, offering a preview of the depth and rigor applied to our findings.
Macro-Economic Trajectory and Market Size
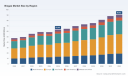
The biogas industry has demonstrated remarkable resilience and growth potential over the past five years. Our historical analysis covering the period from 2020 through 2025 reveals a consistent upward trend in revenue generation across the sector. The market valuation data indicates that the industry has successfully navigated supply chain disruptions and regulatory shifts that challenged other renewable sectors during the same timeframe.
Looking forward, the forecast period spanning 2026 to 2032 suggests a sustained growth trajectory. Our models project a Compound Annual Growth Rate (CAGR) of 5.27 percent over this horizon. This growth rate, while steady, masks significant volatility in specific sub-sectors and regions, which our report unpacks in detail. The market is expected to reach substantial valuation milestones by 2032, reflecting not only organic expansion but also increasing integration into broader energy grids and transport fuel mandates.
It is important to note that while the aggregate numbers show growth, the base year data from 2025 highlights a market that is maturing. The transition from high-growth experimental phases to commercial-scale deployment is evident in the revenue patterns. Stakeholders must understand where the growth is concentrated to avoid overexposure to saturating segments while capitalizing on emerging opportunities. Our full analysis provides the specific vessel for this understanding without relying on generalized industry averages.
Segmentation Dynamics and Feedstock Realities
The composition of the biogas market is defined by diverse input materials and application endpoints. Understanding the weight of different feedstock types is essential for evaluating supply chain security and operational costs. Our segmentation analysis covers agricultural waste, municipal waste, sewage sludge, and energy crops. However, raw numbers only tell part of the story.
Recent industry intelligence gathered from IEA Bioenergy Task 37 indicates that manure feedstock prices have risen due to volatility in fertilizer markets, directly increasing operational costs for manure-based anaerobic digestion plants. This cost pressure alters the profitability equations for specific plant types. Similarly, data from the Global Methane Initiative suggests that feedstock prices for cow dung in India have doubled due to disruptions affecting agricultural demand, leading to unprofitability and plant shutdowns in certain regions. These are not isolated incidents but indicators of structural risks within specific feedstock categories.
On the application side, the market serves ends ranging from electricity generation and heating to combined heat and power systems and biofuel production. The mix of these applications varies significantly by geography and regulatory environment. Our report dissects which applications are driving margin expansion versus those that rely heavily on subsidies. By analyzing the interplay between feedstock availability and end-use demand, we identify where logistical bottlenecks may emerge in 2026 and beyond.
Competitive Landscape and Key Players
The competitive environment in the biogas sector is characterized by a mix of specialized technology providers, large-scale operators, and influential industry associations. While market concentration metrics suggest a relatively fragmented landscape on paper, influence is often concentrated among key innovators and strategic developers who are setting the standards for technology and sustainability.
Our research profiles several core enterprises that are shaping the market. In the United Kingdom, Future Biogas stands out as a leading operator and developer, notably securing offtake agreements for unsubsidised biomethane projects, such as their facility for AstraZeneca. This signals a shift towards corporate power purchase agreements that reduce reliance on public subsidies.
Technology providers are equally critical. Clarke Energy, based in the UK, has expanded its footprint as a supplier of biogas upgrading systems. Their recent commissioning of the first membrane-based biogas upgrader in India demonstrates the globalization of technology deployment. In Germany, EnviTec Biogas AG remains a pivotal manufacturer of plant technology and components for anaerobic digestion systems worldwide, while VORN Bioenergy GmbH focuses on operating and developing facilities.
Corporate involvement is also increasing. Air Products and Chemicals from the USA provides membrane solutions for biogas separation, highlighting the convergence of industrial gas expertise with renewable energy infrastructure. Other significant players include Entsorga S.p.A. in Italy, known for waste-to-energy facilities, Green Data Science in Germany specializing in biomethane upgrading, and Genia Bioenergy in Spain, which focuses on livestock and agricultural waste facilities.
Industry associations play a surveillance and advocacy role that indirectly shapes market conditions. The American Biogas Council provides critical industry data, reporting that US biogas investment exceeded 2 billion dollars in 2025 with 70 new projects coming online. Meanwhile, the European Biogas Association released its 15th Statistical Report highlighting 165 new biomethane plants operational in the EU during 2024-2025. These data points inform our assessment of market momentum but the strategic implications vary widely by stakeholder type.
Biogas Power Plants Market
Regulatory and Operational Dynamics
No strategic analysis of the biogas market is complete without a rigorous examination of the regulatory framework. The period from 2025 to 2026 is seeing significant policy adjustments that alter the economic viability of projects. In Europe, the EU Methane Regulation 2024 requires detection and repair of methane leakage. However, recent analysis by the European Environmental Bureau points out there are no equivalent mandatory requirements for biogas and biomethane plants, creating a regulatory asymmetry that informed investors should monitor closely.
Furthermore, the EU energy crop limit for biomethane has been tightened. According to the HyFuelUp consortium, a floor deduction reduces the limit from 12 percent to 4 percent in 2025/2026. This shift pushes the market away from energy crops and towards waste-based feedstocks, fundamentally changing the supply chain requirements for producers.
Economic incentives are also undergoing revision. For instance, the Danish gas distribution company Evida proposed a new tariff model from January 2025 imposing a large feed-in tariff that reduces incentives for green biogas producers. Such changes at the regional level can ripple through investment models, affecting internal rates of return and payback periods.
Biogas Market
Our report synthesizes these regulatory fragments into a cohesive risk matrix. We analyze how these policies impact different project types and geographies, allowing readers to anticipate compliance costs and permitting delays. The goal is to provide a clear view of where policy support is strengthening and where it is thinning.
Why This Research Matters for 2026 Decision Making
In a market defined by policy volatility and feedstock fluctuations, generic market reports fail to provide the specificity needed for high-stakes decisions. Our research is built on the premise that competitive advantage comes from anticipating change before it becomes mainstream news. We do not just report what happened; we model what happens next.
For operations managers, this study offers insights into supply chain resilience, particularly regarding feedstock procurement in volatile markets. For financial analysts, the breakdown of revenue streams by application and region helps in valuation modeling and risk assessment. For policymakers and association leaders, the analysis of industry developments and regulatory gaps offers a benchmark against which to measure future policy efficacy.
The report includes detailed profiles of key companies, analysis of recent developments such as new plant launches and investment milestones, and a forward-looking assessment of market concentration. We also incorporate industry context noise, turning raw facts about material costs and regulatory changes into strategic signals.
This level of detail is crucial because the biogas market is not a monolith. A strategy that works for agricultural waste in Europe may not translate to municipal waste in Asia Pacific or energy crops in Latin America. Our segmentation analysis respects these differences, providing the nuance required to tailor strategies to specific contexts.
Conclusion
The biogas sector offers significant opportunities for growth and sustainability impact, but capturing that value requires precise intelligence. As the market moves toward 2032, the convergence of regulatory pressure, technological innovation, and feedstock economics will create winners and losers. PW Consulting's new Biogas Market research is designed to ensure that your organization is positioned among the winners.
To fully leverage the findings outlined in this preview, we invite you to access the complete report on our website. The full document contains the specific data tables, deep-dive regional analysis, and detailed financial modeling necessary to build a robust 2026 strategy. Trust in data-driven insight to navigate the complexities of the biogas revolution.
For detailed analysis of this topic, please visit the official page: Biogas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pelvic Organ Prolapse Repair Device Market to Hit $1,573.3M by 2032, 8.32% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Pelvic Organ Prolapse Repair Device Market: Navigating Growth and Complexity in 2026
The global landscape for pelvic organ prolapse repair devices is undergoing a profound transformation. For medical device executives, investors, and strategic planners, understanding the nuanced interplay between regulatory shifts, material science advancements, and evolving surgical preferences is no longer optional—it is critical for survival and growth. As we move into 2026, the market presents a complex matrix of opportunities tempered by significant compliance and reimbursement challenges. This article serves as a strategic primer, drawing from our latest comprehensive market research report, designed to equip leadership teams with the foresight needed to navigate the forecast period from 2026 through 2032.
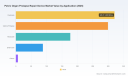
Our analysis indicates that the global market for pelvic organ prolapse repair devices, valued at approximately 892.5 million USD in 2025, is on a steady upward trajectory. The sector is projected to expand significantly over the coming years, reaching a valuation of 1,573.3 million USD by 2032. This growth is underpinned by an estimated Compound Annual Growth Rate (CAGR) of 8.32 percent during the forecast period. However, raw top-line numbers only tell a fraction of the story. The real strategic value lies in understanding the drivers behind this expansion, the fragmentation within the competitive landscape, and the specific dynamics reshaping product portfolios and surgical protocols.
Market Trajectory and Value Driver Analysis
The historical data from 2020 to 2025 reveals a consistent pattern of growth, recovering from 712.5 million USD in 2020 to the current 2025 baseline. This historical resilience sets the stage for the forecast period. The projected increase from 957.66 million USD in 2026 to over 1.5 billion USD by 2032 suggests a market that is maturing but still expanding. For stakeholders, this implies that while the low-hanging fruit of early adoption may be diminishing, significant volume remains in emerging markets and in the adoption of advanced procedural kits.
Several macroeconomic and demographic factors are converging to drive this demand. The aging global population continues to be a primary catalyst, as the prevalence of pelvic floor disorders increases with age. Furthermore, there is a shifting preference toward minimally invasive procedures and outpatient settings, driven by cost containment pressures within healthcare systems. This shift influences not just the volume of procedures but the type of devices being procured. For instance, the move toward single-use procedural instrumentation configurations reduces the need for extensive institutional sterilization infrastructure in ambulatory settings, aligning with hospital efficiency goals. Understanding where this shift is most pronounced geographically and by procedure type is essential for market entry or expansion strategies.
The Competitive Landscape: Consolidation and Innovation
The competitive environment is characterized by a moderate level of concentration. Our analysis shows that the top three companies hold approximately 58.0 percent of the market share, while the top five control around 62.0 percent. This concentration indicates that while there are dominant players, there is still substantial room for challengers and niche innovators to carve out significant value positions. The presence of major multinational corporations alongside specialized innovators creates a dynamic ecosystem where acquisition targets and partnership opportunities are frequent.
Pelvic Organ Prolapse Repair Device Market
Key players are actively differentiating their portfolios through technological innovation and strategic positioning. Johnson & Johnson MedTech (Ethicon) continues to leverage its scale to offer bioresorbable materials and minimally invasive kits aimed at restoring pelvic ligament support. Similarly, Boston Scientific Corporation provides the Capio SLIM suture-capturing device and Upsylon Y-Mesh, focusing on pelvic floor reconstruction and prolapse repair. These large entities benefit from established distribution networks and comprehensive reimbursement support.
However, the market is also seeing activity from specialized players. Coloplast Group develops and supplies biologic mesh solutions and procedural kits, capitalizing on the shift toward biological materials. Cook Medical Incorporated supplies customized mesh solutions and instrumentation for patient-specific reconstruction, addressing the need for tailored surgical outcomes. Integra LifeSciences and CooperSurgical, Inc. also remain pivotal, providing biologic grafts, support systems, and procedural kits. Additionally, companies like Utah Medical Products, Inc. focus on manufacturing instruments and support systems that streamline the procedural workflow.
Innovation is also coming from newer entrants disrupting traditional paradigms. Escala Medical, based in Israel, offers the Mendit device, an FDA-cleared incision-free anchor system for pelvic organ prolapse surgical repair. This type of innovation represents a shift away from traditional mesh or graft reliance toward anchor-based systems. In June 2025, Escala Medical raised 4.5m EUR (approximately 5.3m USD) to accelerate commercialization and global expansion of the Mendit device, signaling strong investor confidence in alternative surgical approaches. Meanwhile, regulatory clearances continue to shape the non-surgical segment. In March 2024, Cosm Medical received FDA 510(k) clearance for the Gynethotics Pessary, a collapsible device for temporary nonsurgical management, highlighting the ongoing demand for conservative management options alongside surgical interventions.
Regulatory and Reimbursement Dynamics
No strategic analysis of this market is complete without a rigorous examination of the regulatory and reimbursement environment. These factors often dictate the viability of product lines and the speed of adoption. The regulatory landscape presents a dichotomy of challenges and opportunities. The FDA maintains that transvaginal surgical mesh devices for pelvic organ prolapse do not have a favorable benefit-risk profile due to potential additional risks compared to native tissue repair. This stance has fundamentally altered product development roadmaps for many manufacturers, pushing innovation toward bioresorbable materials and alternative support systems.
In response to these regulatory pressures, new bioresorbable mesh solutions from major manufacturers emphasize faster tissue integration to address post-operative complication concerns in pelvic organ prolapse repair. This technological pivot is not merely a compliance exercise but a competitive differentiator. Companies that can demonstrate superior tissue integration and reduced complication rates are likely to secure preferential positioning with surgeons and hospital procurement committees. Furthermore, biological grafts are noted as the fastest-growing segment in pelvic organ prolapse repair following reduced synthetic mesh use. This trend underscores the importance of material science in the current market cycle.
On the reimbursement front, clarity is essential for financial modeling. Pelvic organ prolapse repair procedures such as transabdominal allograft treatment use CPT code 57280, which is reimbursed under Medicare physician fee schedules. Understanding the nuances of coding and payment guides, such as the Boston Scientific 2026 Coding and Payment Guide, is vital for sales teams and market access strategists. Variations in reimbursement policies across different regions can significantly impact the total addressable market for specific device types. Our full report delves into these nuances, providing the granular data necessary to model revenue streams accurately under different regulatory scenarios.
Strategic Implications for 2026 Decision Makers
As we approach 2026, several strategic imperatives emerge for organizations operating in this space. First, portfolio diversification is key. Given the regulatory scrutiny on synthetic mesh, companies must balance their offerings with biologic grafts and non-mesh support systems. Relying too heavily on a single material class exposes a firm to significant risk if regulatory guidance tightens further. Second, geographic expansion strategies must be data-driven. Different regions exhibit different adoption rates for new technologies and varying levels of regulatory strictness. Understanding where the market volume is concentrated without relying on generic data is crucial for resource allocation.
Third, partnerships and M&A activity should be monitored closely. The presence of companies like Escala Medical securing funding for novel devices suggests that venture capital is willing to back innovation in this sector. For larger incumbents, acquiring these technologies could accelerate their pipeline and mitigate risks associated with internal R&D delays. Fourth, sales and marketing efforts should align with the shift toward ambulatory settings. Emphasizing single-use instrumentation and ease of use in marketing collateral can resonate with facilities looking to optimize throughput and reduce sterilization costs.
Unlocking the Full Intelligence Picture
While this overview highlights the macro trends, the competitive moves, and the regulatory constraints, it necessarily omits the granular data required for immediate operational planning. To make informed decisions for 2026 and beyond, leadership needs access to detailed segmentation analysis, precise regional breakdowns, and specific application-based growth rates. Our full market research report provides this depth. It dissects the market by specific device types, application categories, and regional dynamics, offering the precise metrics needed to validate strategic hypotheses.
Vaginal Pessary Market
The report includes comprehensive profiles of key companies, detailed analysis of recent developments, and a thorough examination of the industry context noise that impacts market viability. It moves beyond general observations to provide actionable intelligence on market share distributions, growth vectors within specific segments, and the financial implications of regulatory changes. For executives who need to justify capital allocation, R&D spending, or market entry strategies to their boards, this level of detail is indispensable.
The pelvic organ prolapse repair device market is poised for significant growth, but the path to capturing that value is fraught with complexity. The difference between success and stagnation lies in the quality of intelligence guiding your strategy. We invite you to access the full research study to obtain the complete dataset, including specific regional valuations, segment percentage splits, and detailed company competitive analysis. Equip your organization with the precise knowledge required to lead in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Pelvic Organ Prolapse Repair Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acrylic Fibers Market to Hit $6.5B by 2032 as Asia Pacific Leads with 3.46% CAGR
By pmarketresearch, 2026-09-15
Navigating the Acrylic Fibers Market: Strategic Insights for 2026 and Beyond
The global acrylic fibers industry stands at a critical juncture as we move through 2026. For textile manufacturers, chemical producers, and investment strategists, understanding the nuanced shifts in this sector is no longer optional—it is a prerequisite for sustainable growth. The convergence of raw material volatility, evolving regulatory landscapes, and changing consumer preferences towards performance and sustainability is reshaping the competitive terrain. At PW Consulting, we have compiled an extensive analysis designed to cut through the noise and provide actionable intelligence for stakeholders aiming to secure their position in this evolving market.
This report serves as a foundational tool for executive decision-making. It moves beyond surface-level trends to offer a granular view of supply chain dynamics, regional performance, and competitive maneuvers. As the industry transitions from post-pandemic recovery patterns to a new normal defined by resource constraints, having access to precise data is the differentiator between reactive management and proactive strategy. Our analysis covers the historical trajectory from 2020 through 2025 and projects forward to 2032, providing a comprehensive timeline for planning capital allocation and product development.
Market Trajectory and Growth Catalysts
The market has demonstrated resilience over the past half-decade, navigating disruptions that affected global supply chains. Current valuation places the global market at a significant scale, with projections indicating a steady climb over the forecast period. The compound annual growth rate (CAGR) during the 2026-2032 window is estimated to reflect moderate but stable expansion, driven by consistent demand in core application sectors and emerging technical uses.
Historical Performance and Future Outlook
Understanding where the market has been is essential for predicting where it is going. The historical data from 2020 to 2025 reveals a market that has absorbed shocks while maintaining an upward trend. Starting from a baseline in 2020, the industry saw recovery and growth leading into 2025. The forecast suggests a continued path upward, with market size expected to reach new milestones by the early 2030s. However, this growth is not linear. Stakeholders must account for intermittent fluctuations caused by feedstock availability and regulatory adjustments.
- Base year analysis anchors current valuation metrics.
- Forecast period extends through 2032 to capture long-term investment cycles.
- Growth drivers include urbanization, synthetic fiber demand, and technical textile innovation.
Revenue Projections and Valuation Dynamics
Revenue projections indicate a healthy trajectory. The financial outlook suggests that while top-line growth is positive, the pace is influenced by external macroeconomic factors. Currency stability and production costs play pivotal roles in the final realized revenue for major players. Our analysis dissects these variables to help firms model their own financial scenarios against market averages.
Segmentation: Product Types and Application Verticals
Success in the acrylic fibers market depends heavily on understanding the specific performance characteristics of different product types and where they are applied. The market is broadly divided into staple and filament fibers, each serving distinct end-user needs. Our report provides a deep dive into how these segments are evolving independently and in relation to one another.
Product Type Dynamics
Staple fiber remains a dominant force, particularly in applications requiring texture, warmth, and blendability. Filament fiber, while representing a smaller portion of the volume, is critical for specific high-performance uses where strength and sheen are paramount. The balance between these types shifts based on pricing mechanisms and technological advancements in polymerization.
Application Sector Analysis
Demand is generated across three primary verticals. Apparel continues to be a major consumer of acrylic fibers, driven by fashion trends and the need for durable, cost-effective synthetic alternatives to natural fibers. Household furnishing represents a stable segment where acrylics offer durability and resistance to environmental factors. The industrial sector is increasingly becoming a focus area, leveraging acrylic fibers for technical applications that require specific chemical or physical properties.
- Apparel sector demand is sensitive to fashion cycles and raw material costs.
- Household furnishing applications benefit from the longevity and aesthetic versatility of acrylics.
- Industrial usage is expanding as new use-cases are validated for technical grades.
Regional Market Dynamics
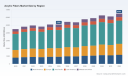
Geographical performance varies significantly based on local manufacturing capacity, consumption patterns, and regulatory environments. Asia Pacific remains a central hub for both production and consumption, reflecting the broader shift in the global textile industry. However, mature markets in Europe and North America retain significant value due to higher pricing power and specific quality standards.
Production and Consumption Hubs
Certain regions have established themselves as key nodes in the supply chain. Production capabilities are concentrated in areas with access to requisite feedstocks and logistical infrastructure. Consumption patterns are tied to local textile manufacturing robustness and retail demand. Our report maps these flows to identify potential bottlenecks or opportunities for market entry.
Acrylic Fibers Market
- Asia Pacific continues to drive volume growth due to manufacturing density.
- Europe and North America focus on high-value segments and compliance-driven markets.
- Emerging markets in Latin America and MEA are showing incremental but notable interest.
Competitive Landscape
The industry is characterized by a mix of regional players and global conglomerates. Market concentration indicates that while there are dominant players, there is still room for specialized niche providers. The CR3 and CR5 metrics suggest a moderate level of consolidation, but competition remains fierce based on innovation and cost efficiency.
Key Market Participants
Several key companies define the current competitive landscape. Organizations such as Aksa Akrilik Kimya Sanayii A.Ş. in Turkey, Dralon GmbH in Germany, and various Japanese entities like Toray Industries, Inc. and Kaneka Corporation represent established operational bases. Asian players from India, including Vardhman Acrylics Ltd. and Indian Acrylics Limited, as well as Chinese manufacturers like Jilin Chemical Fiber Group Co., Ltd., are also critical to the supply equation.
- Global players leverage scale and technology to maintain market share.
- Regional manufacturers often compete on agility and localized supply chain advantages.
- Collaboration and partnerships are becoming more common to secure raw material access.
Recent Strategic Developments
Recent activities among key players highlight the direction of the industry. In March 2025, Toray Industries, Inc. announced the implementation of mass balance methodology in their TORAYLON acrylic staple fiber production, signaling a strong move towards transparent sustainability tracking. Around the same period, Aksa Akrilik Kimya Sanayii A.Ş. expanded its acrylic fibre product range specifically for apparel and technical textile applications, indicating a strategy to diversify beyond commodity grades.
Operational investments remain a priority. Dralon GmbH continued production optimization and operational investments at acrylic fibre facilities throughout 2025, aiming to enhance efficiency amidst cost pressures. On the sustainability front, Thai Acrylic Fibre Co. Ltd. made significant strides in 2024. They partnered with FibreTrace to introduce traceability technology for Regel recycled acrylic fiber and subsequently launched Regel recycled acrylic fiber with Global Recycled Standards certification. These moves underscore a growing market demand for verified sustainable content.
Industry Dynamics: Risks and Regulations
Navigating the market requires a clear understanding of the headwinds facing producers. Raw material costs and regulatory compliance are the two most significant variables affecting profitability and expansion plans in 2026.
Acrylic Rubber Market
Raw Material Volatility
Feedstock stability is a persistent concern. Propylene prices have shown regional increases in early 2026, rising between 3% to 7% due to feedstock volatility and supply constraints. This directly impacts acrylonitrile costs, which are fundamental to acrylic fibers production. Furthermore, specific regional pricing spikes have been observed, such as a significant surge in U.S. Acrylonitrile prices in late March 2026 driven by declining global inventories and tighter upstream availability. Managing these cost fluctuations is central to maintaining margin health.
Regulatory Landscape
Compliance is becoming more rigorous and costly. Environmental restrictions on acrylonitrile have led to compliance costs affecting synthetic fibre producers, with nearly 40% facing operational limits on expansion. North American and European jurisdictions are tightening product certification and safety standards, increasing compliance requirements for acrylic fibers. Similarly, East Asian markets, led by India, are tightening quality and safety thresholds. These regulatory shifts favor suppliers with established compliance frameworks and robust quality assurance systems, potentially raising barriers to entry for smaller or less equipped competitors.
Strategic Value of Comprehensive Market Intelligence
In a market defined by complexity, guesswork is a liability. The strategic value of our Acrylic Fibers Market research lies in its ability to convert data into decision-ready insights. For CEOs and Strategy Directors, this report offers the evidence needed to justify capital expenditure, enter new geographies, or divest from underperforming segments. For Supply Chain Managers, it provides the context needed to negotiate contracts and manage inventory risks related to feedstock volatility.
The 2026 outlook is not just about revenue numbers; it is about understanding the ecosystem. It involves recognizing which competitors are investing in sustainability technologies and how those investments will affect market share in the coming years. It requires knowing where regulatory tightening might pause expansion projects and how to pivot accordingly. Our analysis provides the structural understanding necessary to anticipate these shifts rather than merely reacting to them.
Decision-makers need clarity on where the growth pockets are hidden. While overall market growth is steady, specific applications and regions may outperform the average. Identifying these pockets early allows companies to allocate resources more effectively. Furthermore, understanding the competitive moves of key players like Toray or Aksa helps in benchmarking one's own strategic direction.
Ultimately, this report is designed to empower your organization with the confidence to move forward. Whether you are looking to optimize existing production lines, explore partnerships for recycled fiber initiatives, or assess the risks associated with raw material procurement, the detailed intelligence contained within this study provides the roadmap. In an industry where margins can be squeezed by commodity fluctuations and compliance costs, knowledge is the most valuable asset.
To access the full depth of data, including detailed segmentation revenue figures, regional breakdowns, and proprietary company profiles, we invite stakeholders to review the complete Strategic Market Intelligence Report. This document is structured to support boardrooms discussions and strategic planning sessions throughout 2026 and beyond.
Begin your strategic planning with confidence. Secure the complete market intelligence necessary to navigate the complexities of the Acrylic Fibers Market.
For detailed analysis of this topic, please visit the official page: Acrylic Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ROV Revenue Hits $915M in 2025, Set for 6.89% CAGR Growth to $1.45B by 2032
By pmarketresearch, 2026-09-15
Navigating the Deep: Strategic Imperatives in the 2026 Offshore ROV Market
The offshore energy sector stands at a critical inflection point. As global demand for subsea infrastructure intensifies, driven by both traditional hydrocarbon extraction and the rapid expansion of renewable energy capabilities, the role of Remotely Operated Vehicles (ROVs) has evolved from auxiliary support to mission-critical necessity. For stakeholders navigating this complex environment, understanding the trajectory of the Offshore ROV Market is not merely an academic exercise; it is a fundamental component of risk management and capital allocation strategy.
PW Consulting's latest market research provides a comprehensive lens through which to view these dynamics. This analysis is designed to equip decision-makers with the intelligence required to optimize portfolios, identify partnership opportunities, and anticipate technological shifts that will define the industry through 2032.
Market Trajectory and Historical Context
To understand where the market is going, one must first appreciate the resilience and growth pattern established over the last half-decade. The industry has demonstrated a robust recovery and expansion phase following the volatility of the early 2020s. Historical data indicates a steady climb in market valuation, reflecting increased operational activity and capital investment in subsea technologies.
Starting from a baseline in 2020, the market has progressed through a period of consolidation and growth. By 2025, the industry reached a significant milestone in valuation, setting the stage for the forecast period. The momentum is expected to continue with a compound annual growth rate that underscores the sector's health and long-term viability. This growth is not linear but is influenced by varying regional demands, technological adoptions, and application-specific requirements.
Financial Outlook and Forecast Horizon
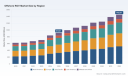
The forecast period extending to 2032 suggests a clear upward trajectory. Projections indicate that market revenue will expand from approximately 996 million in 2026 to over 1.45 billion by the end of the forecast window. This expansion represents more than just nominal growth; it signals increased deployment rates, higher specification requirements for ROV systems, and broader adoption across diverse offshore activities.
For strategic planners, these figures highlight a market that is maturing yet still offers room for differentiation. The consistent growth rate of nearly 7 percent implies that while competition is intensifying, the total addressable market is expanding sufficiently to accommodate new entrants and innovative solutions. However, capturing this value requires a nuanced understanding of where the demand originates and how it is distributed across different operational classes and regions.
Segmentation Dynamics and Operational Diversity
The Offshore ROV Market is not a monolith. It is segmented by operational capability, geographic presence, and application vertical. Each segment presents unique challenges and opportunities for vendors and end-users alike. Our research delves into the specific revenue contributions and volume drivers within these categories, providing a granular view that aggregate numbers often obscure.
Vehicle Classifications and Technical Specifications
The market is broadly categorized by the class of ROV, ranging from observation-class systems used for light inspection to heavy work-class systems capable of complex intervention tasks. The divergence in pricing and capability between a micro/mini system and a heavy work-class unit is substantial. Price points can vary from a few thousand dollars for basic units to several million for advanced systems equipped with sophisticated navigation packages utilizing DVL and USBL technology, which alone can command significant premiums depending on range and precision requirements.
Understanding the revenue split among these classes is vital for manufacturers aligning their production capabilities with market demand. Light work-class and observation-class vehicles continue to hold significant share, driven by their versatility in inspection and maintenance roles. However, the heavy work-class segment remains critical for deep-water construction and high-intensity intervention, particularly in the oil and gas sector. Our report details the specific valuation of each class, allowing stakeholders to assess where their technology fits within the value chain.
Geographic Distribution and Regional Hubs
Demand for ROV services and systems is geographically dispersed, with established hubs in North America, Europe, and the Asia Pacific region. Each region presents distinct regulatory environments, energy mix priorities, and operational challenges. For instance, regulatory frameworks such as the NORSOK U-102 standard in Norway dictate specific requirements for safety, operator competence, and equipment, influencing how ROV services are procured and deployed in that region.
Similarly, international guidelines from the International Maritime Organization provide protocols for operations involving both divers and ROVs, adding a layer of compliance complexity that varies by jurisdiction. Our analysis maps the market value across key regions, identifying where growth is most pronounced. This regional intelligence is crucial for supply chain planning, sales localization, and identifying potential barriers to entry in emerging markets.
Application Verticals: Beyond Traditional Oil and Gas
While the oil and gas sector has historically been the dominant driver of ROV demand, the landscape is diversifying. Offshore wind energy, scientific research, and military and defense applications are contributing an increasing share of the total market volume. This diversification is a key risk mitigation factor for the industry, reducing reliance on a single commodity price cycle.
Diversification into Renewables and Defense
The growth of offshore wind farms requires extensive cable laying, inspection, and maintenance, creating a steady demand for ROVs specialized in these tasks. Military and defense applications also present unique requirements for underwater surveillance and intervention, driving innovation in stealth and endurance. Our report quantifies the revenue contribution from these varying sectors, highlighting how the balance of demand is shifting. Stakeholders who rely solely on traditional energy cycles may find their growth potential limited compared to those who have diversified their service offerings to include renewables and research support.
Regulatory and Compliance Landscape
Operating in these diverse sectors requires adherence to strict regulatory standards. In addition to regional safety standards, industrial and offshore ROV operations often require certified operators and documented maintenance procedures. Compliance is not just a legal obligation but a competitive differentiator. Companies that can demonstrably meet these rigorous standards gain trust with major operators who prioritize safety and reliability above cost alone. Our analysis examines how regulatory trends are shaping procurement criteria and vendor selection processes.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of large multinational corporations and specialized niche players. While the top few companies hold a noticeable portion of the market share, the market remains relatively fragmented compared to other heavy industrial sectors. This fragmentation suggests opportunities for consolidation, strategic partnerships, or specialized niche dominance.
Key Players and Capability Profiles
Several key companies define the current competitive environment. Oceaneering International, based in Houston, stands as one of the world's largest manufacturers and operators of work-class ROV systems, providing integrated services ranging from deepwater work-class systems to remote piloting and advanced visualization. Their scale allows them to influence pricing and technology standards across the industry.
In Europe, companies like Soil Machine Dynamics in the UK and Saab Seaeye Limited are pushing the boundaries of electric and hybrid systems. SMD specializes in advanced work-class ROVs including electric Quantum EV and Quasar MkII systems, focusing on cable tracking and offshore wind cable laying. Saab Seaeye offers electric and hybrid ROV systems for inspection and maintenance in both oil and gas and renewables.
TechnipFMC plc, also headquartered in Houston, leverages its Schilling Robotics legacy to provide advanced work-class ROV systems and intervention tools. They emphasize electric ROV electrification and remote piloting proof-of-concepts, positioning themselves at the forefront of subsea robotics innovation. Forum Energy Technologies and IKM Group round out the significant players, offering subsea technologies and inspection tools tailored for oil and gas and renewables.
International representation is strong, with Saipem in Italy focusing on subsea services for construction and IRM projects, and ECA Group in France providing ROV systems for subsea intervention. L3Harris Technologies and Deep Ocean Engineering contribute communication and integration systems, while TMT and Argus Remote Systems offer specialized ROV and subsea technologies for offshore operations.
Recent Innovations and Technology Shifts
The competitive landscape is currently being reshaped by technological announcements and product launches. In early 2026, Deep Trekker Inc. launched the SPECTRA ROV at Oceanology International, a next-generation subsea robot designed for high-current offshore environments with heavy payloads and precise inspection tasks. This highlights the industry's move towards higher performance in challenging conditions.
Simultaneously, Oceaneering has discussed the ROV electrification inflection point, positioning electric systems as a key efficiency driver in offshore energy. This aligns with broader industry trends towards decarbonization and operational efficiency. Furthermore, MacArtney Offshore Solutions was awarded a contract for a fully electrical eLARS system in early 2026, supporting ROV operations on offshore vessels. These developments signal a clear shift towards electrification and automation, themes that our report explores in depth to help companies prepare their technology roadmaps.
Strategic Value for 2026 Decision-Making
In an environment defined by rapid technological change and shifting energy priorities, access to accurate, forward-looking data is paramount. This market research is not just a retrospective on performance but a tool for shaping future strategy. It enables executives to validate assumptions, benchmark against competitors, and identify whitespace opportunities.
Risk Mitigation and Opportunity Identification
By understanding the concentration of market power, companies can better anticipate pricing pressures and competitive moves. The data on market concentration reveals the degree of rivalry and potential for consolidation. For investors, this informs valuation models and exit strategies. For operators, it informs procurement strategies and vendor management. Furthermore, recognizing the growth rates across different applications allows companies to pivot resources towards high-growth sectors such as offshore wind or specialized defense contracts before the market becomes saturated.
Technology Roadmap Alignment
The shift towards electric systems and automation requires significant capital investment and retraining. Companies need to know the pace of this adoption to avoid stranded assets or obsolescence. Our research provides the context needed to align internal R&D with external market demand. Whether it is investing in navigation precision, payload capacity, or energy efficiency, knowing the specific requirements of the end-user is critical.
Conclusion and Access to Intelligence
The Offshore ROV Market presents a compelling case for strategic investment and careful planning. With a clear growth trajectory extending into the next decade and a evolving competitive landscape driven by electrification and diversification, the opportunities are significant for those equipped with the right intelligence.
Offshore ROV Market
Offshore AUV Market
However, the macro trends discussed here only scratch the surface of the available intelligence. To truly navigate this landscape, stakeholders require a granular understanding of segment-specific revenue flows, regional growth nuances, and detailed competitor benchmarking that goes beyond public profiles.
PW Consulting's full Offshore ROV Market report offers this depth. It provides the specific segmentation data, regional valuations, and comprehensive competitive analysis necessary to formulate robust strategies for 2026 and beyond. To access the complete dataset and detailed forecasts that will inform your critical business decisions, we invite you to visit the source webpage for the full research briefing.
For detailed analysis of this topic, please visit the official page: Offshore ROV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Small Caliber Ammunition Market Hits $8,170M in 2025, Forecasts 3.55% CAGR to $10,375M by 2032
By pmarketresearch, 2026-09-15
Navigating the Small Caliber Ammunition Market: Strategic Intelligence for 2026 and Beyond
The global defense and commercial landscape is undergoing a period of rapid recalibration, driven by shifting security architectures, heightened procurement demands, and persistent supply chain complexities. For executives, investors, and procurement leaders operating in the munitions sector, understanding the trajectory of small caliber ammunition is no longer a peripheral exercise. It is a central component of risk management, capacity planning, and competitive positioning. As we enter 2026, the market stands at a critical inflection point where historical performance, near-term procurement cycles, and long-term capability transitions intersect. This industry insight introduces our latest comprehensive research report on the Small Caliber Ammunition Market, designed to equip stakeholders with actionable intelligence for strategic decision-making throughout the forecast period and beyond.
Market Trajectory and Structural Evolution
Over the past half-decade, the small caliber ammunition sector has demonstrated a clear pattern of resilience and steady expansion. Historical tracking from 2020 through 2025 reveals a market that has consistently navigated fluctuating demand signals, procurement cycles, and macroeconomic variables. The baseline valuation for 2025 anchors the industry at approximately 8,170.0 million USD, reflecting a mature yet continuously evolving ecosystem. Looking forward, the forecast horizon spanning 2026 to 2032 projects a compound annual growth rate of 3.55 percent, culminating in a projected market size of 10,375.0 million USD by the terminal forecast year.
This growth trajectory is not merely a function of incremental volume increases. It reflects deeper structural shifts in how governments, security agencies, and commercial enterprises approach ammunition procurement and inventory management. The forecast period captures the ramp-up of next-generation weapon platform transitions, sustained homeland security requirements, and the commercial sector's adaptation to evolving regulatory and market conditions. Importantly, the data underscores a market that is expanding at a measured but durable pace, demanding that stakeholders balance short-term operational agility with long-term strategic foresight.
Core Dimensions of the Industry Landscape
The contemporary small caliber ammunition market operates across multiple intersecting dimensions, each carrying distinct implications for pricing, production capacity, and competitive positioning. The product architecture is dominated by centerfire and rimfire configurations, with specialized variants serving highly specific tactical, training, and commercial requirements. These product segments interact continuously with downstream application demands, ranging from military combat and training programs to homeland security and law enforcement operations, as well as hunting, sports, and commercial self-defense markets.
Small Caliber Ammunition Market
Geographically, the market exhibits pronounced regional concentration patterns, with certain territories accounting for a disproportionate share of total revenue generation. This distribution is driven by defense spending priorities, domestic manufacturing capabilities, export policies, and the localization of procurement frameworks. Understanding these geographic dynamics is essential for companies evaluating market entry, capacity allocation, and partnership strategies. The interplay between regional demand centers and production hubs creates a complex web of opportunity and constraint, particularly as supply chain localization and strategic autonomy become increasingly prominent policy objectives.
Furthermore, the market's competitive structure reflects a moderately concentrated environment. The top three players command a significant share of total industry revenue, while the leading five firms collectively account for the majority of market output. This concentration highlights the importance of scale, established defense contracting relationships, and proprietary manufacturing capabilities. At the same time, it leaves room for specialized manufacturers and regional players to capture niche segments, particularly where localized demand, export opportunities, or differentiated product offerings create competitive openings.
Competitive Dynamics and Strategic Positioning
The competitive landscape is shaped by a blend of established defense contractors, national munitions manufacturers, and specialized commercial producers. Winchester Ammunition, operating from East Alton, Illinois, remains a defining force in the sector, leveraging its operational control of the Lake City Army Ammunition Plant to manufacture critical small caliber ammunition, including 5.56mm, 7.62mm, and .50 caliber variants for both U.S. military and commercial channels. Its deep institutional integration with defense procurement programs positions it as a central actor in shaping production capacity and technology flow.
In Europe, Nammo AS, headquartered in Lysaker, Norway, maintains a strong footprint through its comprehensive 5.56mm and 7.62mm ammunition series. The company's portfolio spans ball, armor piercing, tracer, and training variants, supporting both military readiness and commercial applications across allied markets. This diversified product approach enables Nammo to respond to varying operational requirements while maintaining a consistent presence in high-demand caliber categories.
Meanwhile, regional manufacturers are increasingly asserting their strategic relevance. CBC Global Ammunition, based in São Paulo, Brazil, produces small caliber ammunition for military and commercial markets, including 5.56mm, 7.62mm, and .50 caliber formats. Its presence underscores the growing importance of Latin American production capabilities and export-oriented manufacturing strategies. Similarly, PT Pindad, headquartered in Bandung, Indonesia, manufactures small caliber ammunition for the Indonesian military and export markets, reflecting the broader trend of regional defense industrialization and indigenous capability development.
These companies operate within an environment where scale, technological integration, and supply chain resilience determine competitive advantage. The ability to align production capacity with procurement cycles, manage raw material dependencies, and meet stringent quality and compliance standards remains a defining differentiator. For stakeholders evaluating partnership, investment, or market entry opportunities, understanding the strategic posture of these key players is essential.
Recent Industry Developments and Capacity Expansion
The period leading into 2026 has been marked by notable operational and strategic developments across the small caliber ammunition sector. Organizational restructuring and asset integration have emerged as recurring themes. In April 2025, Olin Corporation completed the acquisition of small caliber ammunition manufacturing assets from AMMO, Inc., integrating brass shellcase production and the Manitowoc, Wisconsin facility into Winchester operations. This move signals a strategic emphasis on vertical coordination and production consolidation, reinforcing manufacturing efficiency and supply chain control.
On the defense procurement front, the U.S. Army and the Joint Program Executive Office for Armaments and Ammunition broke ground in February 2025 on a new 6.8mm ammunition production facility at the Lake City Army Ammunition Plant. This initiative is designed to support the Next Generation Squad Weapon Program, illustrating how caliber transitions and platform modernization are directly reshaping production infrastructure. By January 2026, the facility reached a significant milestone with the topping out of the 508,345-square-foot production building, marking tangible progress in next-generation ammunition capacity development.
International capacity expansion efforts have also accelerated. Sellier & Bellot expanded its production capabilities with a new manufacturing facility in the Czech Republic in September 2025, enhancing its ability to serve European and export markets. In June 2025, Mesko announced a substantial capacity expansion, quintupling its small-caliber ammunition production capacity to 250 million rounds annually. These initiatives reflect a broader industry response to sustained demand pressure and the strategic imperative to build resilient, scalable manufacturing networks.
Supply Chain, Raw Material, and Regulatory Dynamics
The operational environment for small caliber ammunition manufacturers is increasingly defined by raw material dependencies and regulatory frameworks that shape procurement, production, and trade. Nitrocellulose, a critical propellant component, has emerged as a focal point of supply chain management and pricing strategy. Recent solicitations have referenced Economic Price Adjustment mechanisms for Nitrocellulose in small caliber ammunition contracts, highlighting the sensitivity of production costs to raw material market fluctuations and the need for contractual flexibility.
In response to these dependencies, major industry participants have pursued strategic supply chain security measures. Colt CZ Group acquired a majority stake in Synthesia Nitrocellulose to secure propellant supply for small caliber ammunition, while CSG acquired IFF nitrocellulose production in Germany to strengthen propellant supply capabilities. These moves underscore a broader industry trend: the recognition that raw material access is not merely a procurement variable but a strategic asset that directly affects production continuity, cost stability, and competitive resilience.
Regulatory developments are equally influential. In June 2025, the ATF authorized the importation of certain marking or training rounds under the Gun Control Act for research use only, creating new pathways for specialized procurement while reinforcing compliance boundaries. Export controls also remain a defining parameter, as evidenced by the certification of 5.56mm assault rifle exports under the Arms Export Control Act with congressional notifications. These regulatory frameworks shape market access, trade flows, and the strategic calculus of international procurement and distribution.
What Our Research Report Delivers
Our Small Caliber Ammunition Market research report is structured to provide decision-makers with a comprehensive, actionable intelligence framework. Rather than offering static snapshots, the analysis is built around forward-looking scenario planning, competitive benchmarking, and operational insight. The report maps market size evolution across historical and forecast periods, providing a clear baseline for evaluating growth trajectories and demand drivers.
Beyond macroeconomic indicators, the report delivers granular examinations of product architecture, application segmentation, and regional distribution patterns. These analyses are integrated with competitive profiling, enabling stakeholders to assess market share dynamics, production capacity trends, and strategic positioning among leading manufacturers and emerging entrants. The research also incorporates a detailed review of recent industry developments, including facility expansions, asset acquisitions, and capacity milestones, contextualizing them within broader market forces.
Supply chain and regulatory considerations are treated as core analytical pillars. The report examines raw material dependencies, pricing mechanisms, and strategic procurement adjustments, while mapping the regulatory landscape that governs importation, export control, and compliance requirements. This multidimensional approach ensures that executives, analysts, and investors can evaluate not only where the market is heading, but also the structural factors that will influence profitability, risk exposure, and strategic optionality.
Large Caliber Ammunition Propellant Market
Strategic Imperatives for 2026 Decision-Making
For organizations operating in or adjacent to the small caliber ammunition market, 2026 presents a decisive window for strategic alignment. The convergence of caliber modernization programs, capacity expansion initiatives, raw material security measures, and evolving regulatory frameworks creates both opportunity and complexity. Companies that succeed in this environment will be those that integrate market intelligence into procurement planning, capacity investment, and partnership strategy.
Decision-makers must evaluate how shifts in military procurement priorities, law enforcement demand, and commercial market dynamics will affect volume forecasts and pricing structures. They must also assess how competitive concentration and regional manufacturing strategies influence supply reliability and market access. The ability to anticipate capacity bottlenecks, manage raw material exposure, and navigate regulatory parameters will separate resilient organizations from those that are overly exposed to volatility.
This report is designed to support that evaluation. By synthesizing market sizing, segmentation insights, competitive analysis, and industry dynamics into a coherent intelligence framework, it provides the foundation for informed strategic choices. Stakeholders who engage with the full analysis will gain a clearer understanding of where value is being created, how competitive boundaries are shifting, and what operational adjustments are required to maintain positioning in a market that is expanding with purpose and precision.
The small caliber ammunition market is not defined by sudden disruption alone, but by the cumulative effect of procurement strategy, manufacturing investment, supply chain security, and regulatory evolution. For leaders navigating this landscape, the difference between reactive positioning and proactive strategy lies in the quality of intelligence available. Our research report offers that intelligence in depth, providing the analytical rigor necessary to support confident, forward-looking decisions throughout 2026 and the forecast period ahead.
For detailed analysis of this topic, please visit the official page: Small Caliber Ammunition Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Textile Dyes Market Hits $1.19 Billion in 2025, Projected 5.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Chromatics of Growth: Strategic Intelligence for the Textile Dyes Market Through 2032
The global textile dyes industry is entering a defining era. As sustainability mandates tighten, raw material volatility accelerates, and regional manufacturing footprints shift, color chemistry has evolved from a commoditized input into a strategic differentiator. For executives, procurement leaders, and product developers operating in the fibers and fabrics value chain, the ability to anticipate demand curves, regulatory inflection points, and competitive realignments is no longer optional. It is the foundation of resilient margin planning and portfolio strategy.
PW Consulting's latest Textile Dyes Market research report delivers a structured, data-rich examination of the sector across the forecast horizon of 2026 through 2032. Drawing on a rigorous historical evaluation spanning 2020 to 2025 and anchored in a base year of 2025, this study translates complex market mechanics into actionable intelligence. The following overview outlines the strategic architecture of the report, highlights the macro-momentum shaping the industry, and demonstrates how decision-makers can leverage these findings to outperform in a rapidly evolving landscape.
Market Trajectory: A Measured Expansion with Strategic inflection Points
Over the past half-decade, the textile dyes sector has demonstrated consistent growth, reflecting steady fiber production, evolving consumer color preferences, and the ongoing technical upgrading of dyeing infrastructure across mature and emerging manufacturing hubs. Historical revenue expanded from approximately 920.5 million USD in 2020 to a base-year valuation of 1190.0 million USD in 2025, underscoring the industry's capacity to compound value even amid supply chain disruptions and raw material price fluctuations.
Looking ahead, the forecast trajectory signals sustained expansion. The market is projected to reach a valuation of 1246.44 million USD in 2026, climbing steadily through the decade to attain a terminal forecast value of 1689.4 million USD by 2032. This path reflects a compound annual growth rate of 5.2 percent across the full forecast period, a pace that rewards early strategic positioning while demanding disciplined capacity planning, pricing architecture, and compliance readiness. Critically, the growth curve is not linear; it is shaped by distinct catalysts—including regulatory phase-ins, regional capacity realignments, and technology-led differentiation in dye chemistry—that require granular analysis to translate into operational advantage.
This study dissects those catalysts without oversimplifying them. Rather than offering a single headline number, the report maps the interplay between historical demand elasticity, forward-looking procurement signals, and the structural factors that will determine which market participants capture disproportionate share. Readers will find that the macro-outlook serves as an anchoring framework, while the deeper segmentation layers reveal where margin pools are forming and where competitive intensity is likely to compress returns.
Report Architecture: From Strategic Framework to Operational Playbook
A market study earns its place on the executive dashboard only when it bridges high-level economic signals with on-the-ground decision variables. The PW Consulting Textile Dyes Market report is built around that principle. It delivers a comprehensive, multi-layered assessment that spans quantitative forecasting, qualitative industry mapping, and competitive benchmarking, all organized to support scenario planning and resource allocation.
At its core, the report integrates a detailed industry analysis covering the period from 2020 through 2032, with a sharp focus on the immediate two-year strategic window of 2026 and 2027. This design enables leadership teams to calibrate both near-term tactical responses and longer-term capital deployment. The study examines the market through a structured segmentation lens—by type, by application, and by region—allowing users to isolate the demand engines most relevant to their product portfolios, manufacturing footprint, and distribution channels. Each segmentation dimension is evaluated for growth momentum, pricing sensitivity, and substitution risk, ensuring that strategic plans rest on differentiated evidence rather than aggregated averages.
Beyond segmentation, the report incorporates a thorough competitive landscape assessment. Market concentration metrics are analyzed to clarify the balance between consolidated leadership and fragmented niche competition, while company-level profiles illuminate the strategic priorities shaping the actions of dominant players. These profiles are not static corporate summaries; they are structured around each firm's specific dye offerings, regional strengths, and innovation orientation, providing a practical map of where incumbents are reinforcing their positions and where gaps may be opening for fast-moving challengers.
Dyes Market
The research also embeds a robust view of industry dynamics. Raw material economics, regulatory evolution, and sustainability-driven procurement requirements are treated as interconnected forces, not isolated events. By tying these dynamics to forecast periods and competitive behavior, the report equips readers to anticipate cost pressures, compliance expenditures, and product reformulation timelines that will influence sourcing strategies and product roadmaps.
For practitioners seeking operational depth, the study delivers the kind of actionable detail that supports concrete decisions: pricing architecture considerations, demand-center prioritization, regulatory readiness checks, and technology adoption pathways. The objective is to give executives and analysts a reference point that can be directly integrated into commercial planning, supply chain strategy, and R&D prioritization.
Competitive Landscape: Positioning, Differentiation, and the Battle for Specialty Relevance
The textile dyes market is characterized by a mix of global specialty chemical leaders, regional manufacturing powerhouses, and focused dye specialists. Competitive intensity is shaped not only by volume scale, but by the ability to offer performance-advantaged products, compliance-forward formulations, and application-specific color solutions. Market concentration reflects a moderately consolidated structure, with leading players commanding a meaningful share of total revenue while leaving substantial space for differentiated mid-tier and regional competitors to compete on technical service, agility, and customer intimacy.
Several organizations stand out for the strategic direction of their dye portfolios. Archroma, headquartered in Pratteln, Switzerland, has been advancing sustainable specialty dyes and dyeing solutions with bio-based options, signaling a clear orientation toward lower-environmental-impact chemistry and resource-efficient processing. DyStar Group, based in Singapore, continues to position itself as a leading supplier of textile dyes, pigments, and colorants with broad fiber coverage, an approach that supports customers seeking continuity across diverse material inputs. Huntsman Corporation, operating from The Woodlands, Texas, United States, maintains a portfolio of textile effects dyes and performance chemicals, reinforcing a value proposition centered on functional outcomes as well as color.
In Europe, Clariant AG of Muttenz, Switzerland, contributes specialty chemicals including dyes tailored for textile applications, while Lanxess AG, based in Cologne, Germany, offers dyes under its Macrolex brand for textiles, aligning its product identity with established performance credentials. Across the Indian subcontinent, Atul Ltd., headquartered in Atul, Gujarat, and Kiri Industries Ltd., also based in Gujarat, represent strong regional capabilities—Atul with performance chemicals and dyes for textiles, and Kiri with a focused emphasis on reactive and acid dyes. BASF SE, headquartered in Ludwigshafen, Germany, sustains a broad offering of dyes and intermediates for textile applications, leveraging scale and integrated chemistry competencies. Meanwhile, Sumitomo Chemical Co., Ltd., operating from Tokyo, Japan, pursues specialty dyes for textiles, underscoring the continued relevance of application-specific innovation in the global supply base.
Together, these players illustrate the competitive logic of the market: scale provides procurement and distribution advantages, but differentiation increasingly depends on sustainability attributes, color fastness and reproducibility, regulatory compliance readiness, and the ability to support customers through process optimization. The report analyzes how these firms are navigating raw material cycles, expanding or rationalizing capacity, and positioning their portfolios against tightening compliance expectations. By synthesizing these competitive signals, the study helps readers identify which strategic moves are likely to strengthen market standing and which product categories may face intensifying margin pressure.
Industry Dynamics: Regulation, Raw Materials, and the New Compliance Premium
No strategic assessment of the textile dyes market can ignore the regulatory and input-cost environment reshaping procurement behavior. In 2026, these forces are not background conditions; they are direct determinants of product design, supplier selection, and regional sourcing decisions.
On the regulatory front, compliance expectations are becoming more demanding and more tightly enforced. From 1 January 2026, OEKO-TEX standards tightened PFAS limits to 25 µg/kg across all standards, accompanied by enhanced verification mechanisms. This change directly affects the colorant and auxiliary chemistry that textile manufacturers can confidently specify, accelerating the shift toward lower-concern formulations. In parallel, REACH Annex XVII Entry 72 continues to restrict 33 substances in clothing, textiles, and footwear that come into contact with human skin, with ongoing enforcement sustaining pressure on product stewardship across the value chain. Broader chemical policy signals add further complexity: a PFAS restriction in consumer textiles such as rain jackets bans the sale and use of PFHxA from 2025 onward, and a U.S. Environmental Protection Agency final rule prohibits the distribution of articles containing phenol, isopropylated phosphate in U.S. commerce starting 31 October 2026, affecting textile and fashion supply chains.
These developments carry a strategic implication: compliance is moving from a defensive obligation to a commercial asset. Manufacturers that can demonstrate clear substance profiles, robust verification documentation, and reformulated dye systems are better positioned to serve brands and converters facing their own disclosure and procurement requirements. The report examines how regulatory timing interacts with product launch cycles and sourcing transitions, helping readers gauge where compliance-driven demand may accelerate adoption of specific dye technologies.
Raw material dynamics are equally consequential. During the first quarter of 2026, H acid prices increased moderately in Germany to 5,266 USD per metric ton, up 3.09 percent, driven by steady demand from specialty chemical and textile converter procurement. While the move is measured rather than disruptive, it reflects a broader environment in which input costs are influenced by regional demand patterns, production constraints, and the specialized nature of key intermediates. For dye producers and downstream textile processors, even moderate input-price movements can affect margin structures, quotations, and inventory timing.
Recent market events further illustrate the operational reality of this environment. In February 2026, Zhejiang Runtu Co., Ltd. announced a significant price surge for disperse dyes effective that month, with increases reaching up to 600 USD per metric ton for high-concentration blacks and blues. Around the same time, Zhejiang Longsheng Group Co., Ltd. announced an additional CNY 2,000 increase for disperse black and blue dyes, bringing the cumulative hike in the year to CNY 5,000, a move attributed to raw material costs. These announcements underscore how regional pricing actions can quickly affect cost planning and highlight the importance of monitoring supplier signaling as part of broader procurement strategy.
On the innovation and validation side, January 2026 saw Archroma announce the commercial launch of a new line of cellulosic direct dyes with up to 35 percent effluent COD reduction compared to conventional grades, a development that aligns product performance with wastewater management objectives. In April 2026, SGS attended China Interdye 2026 in Shanghai, connecting with experts on sustainable chemical management and awarding the first No PFAS Detected green-mark certificate for a water-repellent agent to a textile firm. Such milestones matter because they signal where validation frameworks, customer expectations, and product differentiation are converging.
Strategic Priorities for 2026 Decision-Making
For executives entering 2026, the central challenge is to convert market complexity into structured choices. The forecast growth rate of 5.2 percent confirms that demand expansion will continue, but value capture will depend on how well organizations align portfolio, sourcing, and compliance strategies with the specific forces shaping their segments. Several strategic priorities emerge from the broader market picture.
Textile Dyes Market
First, portfolio composition should be evaluated against both demand durability and regulatory exposure. Dye families and application areas that face higher compliance scrutiny may require accelerated reformulation, while segments with strong growth momentum and lower substitution risk may justify prioritized capacity or inventory support. Second, pricing and procurement planning should account for regional raw material behavior and supplier-level pricing actions, especially in disperse dye categories where recent increases have demonstrated the speed at which cost structures can shift. Third, sustainability and verification capabilities are becoming competitive levers. Formulations that reduce effluent load, lower concern-substance risk, and support customer documentation needs can strengthen supplier positioning in brand-driven procurement environments. Fourth, regional demand patterns should inform distribution and service strategies, since growth is not evenly distributed and customer expectations differ across manufacturing centers.
The study is designed to support each of these priorities with specific evidence, enabling readers to test assumptions, compare scenarios, and identify where decisive action will generate the greatest strategic return. By connecting the macro trajectory to segmentation-level dynamics, competitive behavior, and regulatory timing, the report provides a decision framework rather than a static market snapshot.
Accessing the Full Intelligence
The overview presented here reflects the analytical direction and strategic scope of the full Textile Dyes Market research report. To obtain the complete dataset, detailed segmentation analysis, comprehensive company profiles, and the full set of market forecasts and competitive assessments that support rigorous planning, readers are encouraged to access the complete report and accompanying materials directly. The depth required for precise sourcing, product roadmap decisions, and competitive positioning can be found in the full study, where each macro signal is reinforced by structured evidence and actionable interpretation.
For detailed analysis of this topic, please visit the official page: Textile Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cover Glass Market Hits $1.56B with 1.3% CAGR from 2026-2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the 2026 Decision-Maker: Smartphone Cover Glass Market Outlook
The smartphone cover glass market stands at a critical inflection point as industrial leaders navigate the 2026 operating environment. Following five years of moderate historical expansion from 2020 through 2025, the sector now enters a forecast horizon extending to 2032 that demands precise strategic calibration. Our latest market research study translates complex supply-demand signals, regulatory shifts, and competitive maneuvers into actionable intelligence for procurement executives, R&D planners, and C-suite strategists who must allocate capital with confidence in a market defined by high concentration, evolving material science, and geopolitical recalibration.
This introduction outlines the strategic architecture of the full report, demonstrating why leadership teams should treat this assessment as a core input to 2026 portfolio decisions, capacity planning, and supplier negotiations. Rather than presenting a static snapshot, the research functions as a forward-looking decision framework that connects macro trajectory signals to on-the-ground execution priorities.
Market Trajectory and the Strategic Imperative for 2026
Historical revenue data from 2020 through 2025 reveals a market that has demonstrated resilience through cycles of component volatility, shifting OEM demand patterns, and intermittent supply disruptions. The sector crossed the 1,560 million USD threshold in the most recent base year measurement before entering the current forecast window, where trajectory modeling projects growth toward the 1,700 million USD range by the close of the decade. The forecasted compound annual growth rate of 1.3 percent across the 2026 to 2032 period underscores a market characterized by measured, structural expansion rather than explosive volatility.
For decision-makers, this trajectory carries nuanced implications. A modest CAGR in a high-value component category often masks significant underlying shifts in product mix, regional sourcing preferences, and premiumization trends within flagship device portfolios. The market is not simply growing; it is recomposing. Foldable device architectures, chemically strengthened glass specifications, and OEM supply chain localization strategies are altering where margin accrues and which suppliers capture disproportionate value. Strategic leaders who rely on backward-looking averages risk misallocating resources in a landscape where product-level differentiation and capacity positioning matter far more than aggregate market size.
The full report decomposes this trajectory into decision-grade scenarios, enabling teams to map procurement commitments, capital expenditure timing, and partnership strategies against realistic demand pathways rather than single-point projections. Readers are invited to access the complete forecast modeling and scenario analysis on our source page, where detailed growth drivers, sensitivity parameters, and regional momentum indicators are presented in full operational depth.
Competitive Architecture and Supplier Positioning
Market concentration remains a defining structural feature of the smartphone cover glass landscape. With the top three participants commanding approximately 80 percent of revenue and the top five collectively representing roughly 85 percent, the sector operates as an oligopolistic environment where incumbent scale, proprietary material formulations, and long-standing OEM relationships create formidable barriers to displacement. Yet within this concentrated framework, competitive dynamics are intensifying as suppliers race to align capacity with next-generation device requirements and navigate cost pressures from regulatory and raw-material headwinds.
Incumbent Technology Leaders
Corning Incorporated continues to anchor the premium cover glass segment through its Gorilla Glass series, anchoring a substantial share of flagship smartphone adoption. The launch of Corning® Gorilla® Glass Ceramic 3 in March 2026 marks a deliberate push into enhanced drop durability for foldable device architectures, signaling how material innovation is being reoriented around new form factors rather than traditional flat-panel optimization. This product introduction follows a broader capacity expansion effort in early 2026 designed to support high-volume flagship OEM demand across North American and Asian supply networks.
The strategic weight of these moves was reinforced by the August 2025 commencement of production at a Kentucky facility developed in partnership with Apple, representing a 2.5 billion USD investment that consolidated a significant share of iPhone and Apple Watch cover glass manufacturing within a single U.S.-based operation. For the broader market, this capacity concentration illustrates how anchor OEM commitments can reshape regional supply footprints while reinforcing the competitive moat of leading material science firms.
Diversified Global Contenders
AGC Inc. maintains a strong premium positioning through its Dragontrail® product family, delivering chemically strengthened glass solutions targeted at flagship and high-tier device segments. Schott AG continues to compete in the chemically strengthened category with its Xensation® series, including the Xensation® α specification engineered for improved drop performance in flagship smartphones. Nippon Electric Glass Co., Ltd. supplies chemically strengthened cover glass across smartphone and foldable device applications, while AvanStrate Inc. operates production facilities across Japan, Taiwan, and Korea to support display and cover glass requirements for major OEM customers.
In the broader production ecosystem, Biel Crystal Manufactory Ltd. has scaled as a major global producer of cell phone cover glass and sapphire components, with annual production capacity exceeding 1.85 billion units. Lens Technology Co., Ltd. functions as a key supplier of cover glass, structural parts, and functional modules for smartphones, serving major OEMs worldwide. TPK Holding Co., Ltd. rounds out the competitive field as a manufacturer of cover glass and touch solutions for smartphones. Together, these players illustrate a competitive matrix in which differentiation hinges on material specifications, geographic production flexibility, and the ability to secure multi-year OEM program wins.
The report's competitive analysis module provides granular supplier benchmarking, program win trajectory assessment, and capability-to-capacity alignment mapping. Complete supplier profiles, performance scorecards, and strategic risk indicators are available through the full research portal, enabling procurement and R&D teams to pressure-test their current sourcing strategies against an evolving competitive baseline.
Market Dynamics Shaping Strategic Decisions
The operating environment for smartphone cover glass in 2026 is shaped by intersecting forces that extend well beyond simple demand forecasting. Regulatory compliance costs, export control expansions, import surge patterns, raw-material lead-time elongation, and critical material export restrictions all contribute to a more complex sourcing and planning landscape. Decision-makers must integrate these factors into scenario planning rather than treating them as peripheral risks.
Regulatory and Chemical Compliance Pressure
The European Chemicals Agency reported that compliance costs for hydrofluoric acid used in glass tempering processes rose by 15 percent in 2024. This increase directly touches the cost structure of chemically strengthened glass production, a category that constitutes a meaningful share of premium cover glass supply. For procurement teams, the implication is twofold: cost models that rely on historical chemical input assumptions may underestimate current and forward pricing pressure, and supplier negotiations must account for regional regulatory divergence that affects landed cost and availability.
A separate indicator of demand strength and import dependency comes from the U.S. International Trade Commission, which recorded a 17 percent increase in imports of chemically strengthened glass for smartphones in 2024. This import trajectory signals both robust downstream demand and the extent to which supply chains remain internationally interconnected, even as OEMs pursue localized capacity strategies. The tension between import reliance and regional supply expansion is a key theme explored in the full report's dynamics section.
Geopolitical and Supply Chain Disruption Vectors
U.S. export controls on advanced computing items expanded in 2024, creating ripple effects across global supply chains for specialty glass components. While cover glass may not always fall directly within the narrowest controlled categories, the broader export control environment influences manufacturing equipment access, technology transfer constraints, and supplier qualification pathways across multiple jurisdictions. Strategic sourcing plans that do not explicitly model geopolitical fragmentation risk understimating qualification timelines and dual-sourcing complexity.
Compounding these dynamics, supply chain constraints and precursor cost surges drove average lead times for cover glass components to approximately 45 days in 2024. For program managers and inventory planners, extended lead times translate directly into buffer stock requirements, working capital exposure, and scheduling rigidity. The report's operations section translates these lead-time signals into inventory strategy recommendations and supplier diversification frameworks tailored to high-concentration supply markets.
Smartphone Cover Glass Market
In addition, China's Export Control Law and related MOFCOM regulations, updated with detailed rules in October 2024, impose restrictions on exports of critical materials used in display cover glass production. For organizations with material dependencies crossing this regulatory boundary, the compliance pathway now demands explicit mapping of raw-material origin, processing steps, and end-use classification. The research study provides a regulatory impact matrix that helps teams identify where material flow vulnerabilities could affect cost, availability, or program continuity.
Report Contents and Practical Applications
The full market research study is designed as a decision-support toolkit rather than a static market description. It integrates historical baseline analysis, multi-year forecasting, segmentation perspectives, competitive profiling, and dynamic risk factor assessment into a cohesive reference for 2026 strategy development. The following components represent the operational core of the study.
- Market Sizing and Trajectory Framework: A comprehensive revenue trajectory spanning historical baseline years and a forecast window extending through 2032, structured to support demand planning, capacity justification, and investment prioritization. The analysis presents total market perspective alongside segmentation views that illuminate type-based and application-based composition without isolating strategic detail from its broader market context.
- Segment-Level Composition Analysis: Detailed coverage of material type categories and end-use application patterns, enabling teams to understand where revenue concentration lies and how product mix evolution may influence sourcing requirements, specification priorities, and supplier selection criteria over the forecast horizon.
- Competitive Intelligence and Supplier Profiling: In-depth profiles of the key companies shaping the market, including headquarters location, product positioning, recent strategic developments, and capability signals. The study connects company-level moves to market-level implications, allowing readers to assess competitive threats, partnership opportunities, and supply base resilience.
- Dynamics and Risk Factor Integration: A structured treatment of regulatory cost pressures, export control and trade policy developments, import trend indicators, raw-material lead-time dynamics, and critical material export restrictions. This section translates external signals into actionable planning considerations for procurement, compliance, and supply chain leadership.
- Strategic Implications and Decision Scenarios: Synthesis sections that connect market data, competitive signals, and dynamic risks into decision scenarios for capacity planning, supplier diversification, program timing, and technology roadmapping. These scenarios are designed to support internal alignment across R&D, operations, procurement, and executive strategy functions.
Throughout the study, segmentation insights are presented with the discipline required for confidential strategic use: enough structural clarity to inform sourcing and planning logic, while preserving the detailed quantitative granularity that belongs in the paid research deliverable. The complete segmentation splits, scenario parameters, and sensitivity ranges are available in the full report, where they can be applied directly to internal models and negotiation frameworks.
Why This Research Matters for 2026 Decisions
In a market where a small number of suppliers command the majority of revenue, where material specifications are rapidly evolving around foldable and flagship device requirements, and where regulatory and geopolitical factors are reshaping cost and availability assumptions, strategic advantage depends on early visibility and precise interpretation. Aggregate market size alone does not reveal where margin is shifting, which supplier capabilities will be stressed by new device architectures, or how regional compliance costs will alter sourcing economics over the forecast period.
This research is built to answer those questions with the rigor required for enterprise decision-making. It equips leaders with a structured view of market trajectory, competitive positioning, and dynamic risk factors so that 2026 planning can move beyond reactive adjustments and toward proactive portfolio design. Whether the objective is to validate a long-term supplier partnership, prioritize R&D investment in cover glass specifications, or construct a resilient sourcing strategy amid extended lead times and raw-material constraints, the study provides the analytical foundation to make those choices with greater confidence.
The complete market research study, including full forecast modeling, detailed segmentation breakdowns, supplier capability assessments, and dynamic risk matrices, is available through our source page. We encourage strategy, procurement, and product leadership teams to access the full report to integrate these insights directly into 2026 planning cycles and supplier engagement strategies.
Glass Screen Protector Market
For detailed analysis of this topic, please visit the official page: Smartphone Cover Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Erythritol Market Reaches $271.5M in 2025, Projects 6.5% CAGR
By pmarketresearch, 2026-09-15
Strategic Sweetening: Navigating the Erythritol Market Outlook Through 2032
The global demand for sugar alternatives has evolved from a niche health trend into a fundamental restructuring of the food and beverage supply chain. As regulatory pressures tighten and consumer preferences shift decisively toward clean-label formulations, erythritol has emerged as a cornerstone ingredient for manufacturers seeking to balance caloric reduction with sensory performance. However, the landscape is no longer defined solely by consumer trends. The period from 2026 onward is characterized by intense geopolitical friction, supply chain realignment, and consolidation among key production capacities.
PW Consulting is pleased to present our latest comprehensive market intelligence report on the Erythritol Market. This document serves as a strategic guide for stakeholders aiming to secure competitive advantage in a volatile environment. By integrating historical performance data with forward-looking projections, this analysis provides the necessary framework to make informed decisions regarding capacity planning, sourcing strategies, and market entry.
Market Trajectory and Growth Dynamics
Understanding the macroeconomic trajectory of erythritol is essential for validating long-term investment hypotheses. Our analysis tracks the market revenue over a robust historical period from 2020 through 2025, establishing a baseline against which future performance can be measured. The data indicates a consistent upward trend in valuation, reflecting the ingredient's transition from a specialty additive to a mainstream commodity in the sweetener sector.
The historical revenue progression shows a market that has grown from approximately 198.3 million USD in 2020 to a projected 271.5 million USD at the 2025 base year. This growth underscores the successful commercialization of erythritol across multiple sectors. Looking ahead, the forecast period spanning 2026 to 2032 suggests sustained momentum. The market is anticipated to reach a valuation of 418.65 million USD by the end of the forecast horizon.
This expansion is supported by a Compound Annual Growth Rate (CAGR) of 6.5 percent during the forecast period. While this figure indicates healthy growth, it also implies a maturing market where marginal gains must be driven by efficiency and strategic differentiation rather than mere volume expansion. For corporate strategists, this trajectory signals a critical window for action. Entering the market post-2028 may incur higher barriers due to established supply chains and potential regulatory hardening, making the immediate years crucial for positioning.
Navigating Supply Chain Volatility and Raw Material Costs
One of the most critical variables influencing profitability in the erythritol sector is the cost of raw materials, specifically corn starch which serves as the primary feedstock for fermentation processes. Fluctuations in feedstock prices directly impact the marginal cost of production, yet these are often opaque to downstream formulators.
Recent analyst insights highlight significant regional disparities in raw material pricing as of April 2026. Corn starch prices were recorded at USD 437.00 per metric ton FOB in China, contrasting with USD 495.42 per metric ton CIF in the USA and USD 519.11 per metric ton CIF in India. These differentials create complex arbitrage opportunities but also expose supply chains to currency risk and logistics costs.
For procurement managers, relying on a single geographic source is no longer a viable risk mitigation strategy. Our report delves into the nuances of these cost structures, helping clients understand how regional price variations might impact total landed cost. Understanding the interplay between feedstock volatility and final product pricing is vital for maintaining margin integrity in a competitive bidding environment.
The Geopolitical Dimension: Trade Barriers and Duty Impacts
The erythritol market in 2026 is defined as much by trade policy as by consumer demand. The imposition of anti-dumping duties represents a structural shift in global trade flows, fundamentally altering the cost-benefit analysis of sourcing from different regions. In January 2025, the European Commission imposed definitive anti-dumping duties on Chinese erythritol imports, with rates ranging significantly from 34.4 percent to 233.3 percent. These duties were retroactive to June 2024, creating immediate liquidity pressures for importers who had stockpiled inventory based on previous cost assumptions.
Xylitol Market
Simultaneously, the United States has tightened its stance on Chinese imports. US Section 301 tariffs and preliminary anti-dumping measures on Chinese erythritol entered into effect in July 2025, with final orders issued in March 2026. These measures effectively close the price gap between Western producers and low-cost Asian competitors, reshaping the competitive landscape.
These regulatory developments are not merely background noise; they are active drivers of market share reallocation. A major legal milestone occurred in August 2025 when Cargill Incorporated filed an anti-dumping petition against Chinese erythritol producers, citing overcapacity and market distortions, and secured an initial victory. This legal advocacy signals a broader industry intention to protect domestic fermentation capacities against subsidized or underpriced foreign competition.
Our report provides a detailed regulatory watch section that maps these evolving obligations. For multinational corporations, understanding the specific duty tiers applicable to different suppliers is essential to avoid compliance pitfalls and unexpected cost spikes. The analysis explores how these duties will influence capacity utilization rates in Europe and North America versus export-oriented facilities in Asia.
Competitive Landscape and Strategic Positioning
The market structure exhibits moderate concentration, with the top three players accounting for 56.0 percent of market share and the top five representing 67.0 percent. This concentration suggests that while there is room for niche players, scale advantages remain significant, particularly in fermentation capacity and downstream distribution networks.
Erythritol Market
Key incumbents define the boundaries of competition. Cargill Incorporated, headquartered in Minneapolis, operates the sole Western Hemisphere fermentation capacity for Zerose erythritol at approximately 30,000 metric tons annually. This geographic insulation provides a strategic buffer against transoceanic tariff fluctuations. Similarly, Archer Daniels Midland Company and Tate & Lyle PLC maintain strong positions through their respective fermentation capabilities and brand portfolios such as ERYTESSE.
In Europe, Jungbunzlauer Suisse AG supplies ERYLITE through non-GMO wheat and corn sources, catering to specific regional preferences for non-GMO credentials. Meanwhile, the Asian supply base is dominated by large-scale fermentation producers in Shandong Province, China, including Shandong Sanyuan Biotechnology, Zhucheng Dongxiao Biotechnology, Baolingbao Biology, and Zhucheng Xingmao Corn Developing. These entities focus on cost-effective bulk and food-grade output, leveraging integrated corn processing infrastructure.
Beyond manufacturers, the supply chain includes global traders and distributors such as Mitsubishi Corporation, ProAgro GmbH, and Buxtrade GmbH. These entities facilitate liquidity and logistics but also serve as sentiment indicators for market tightness. The report includes comprehensive profiles of these key companies, analyzing their production capacities, technological focus, and recent strategic moves. Understanding who holds the leverage in specific regions allows clients to negotiate better terms or identify reliable alternative partners should primary supply lines be disrupted by trade policy.
Segmentation and Application Versatility
Erythritol's utility spans far beyond simple sugar replacement in beverages. The market is segmented by type, primarily distinguishing between Powder and Granular forms, each serving different manufacturing requirements. The powder segment often commands different handling and packaging logistics compared to granular variants, influencing the choice of supplier based on the end-product format.
On the application side, the demand is diversified. Beverages represent a significant portion of consumption, driven by the ready-to-drink sector's push for low-calorie profiles. However, substantial volumes are also absorbed by the Bakery and Confectionery sectors, where bulking agents and mouthfeel properties are critical. Dairy products and Pharmaceuticals also utilize erythritol for functional benefits, while the Personal Care sector explores its properties in oral hygiene formulations.
Our segmentation analysis breaks down the revenue contribution across these categories, identifying which sectors offer the highest growth elasticity. For instance, while beverages may offer volume, specialized applications in pharmaceuticals or personal care might offer higher margin potential. The report details these splits to help clients identify white space opportunities. Instead of competing directly in saturated segments, manufacturers can pivot toward applications where erythritol's technical properties offer a unique solution to formulation challenges.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast horizon ending in 2032, the strategic imperatives for stakeholders become clear. The era of unrestricted arbitrage is ending. Companies must decide whether to integrate vertically to secure feedstock stability, form joint ventures to access protected markets, or specialize in high-value downstream formulations that are less sensitive to bulk commodity price swings.
The convergence of regulatory pressure, raw material volatility, and competitive consolidation means that agility is paramount. Data-driven decision-making is no longer optional. Firms that rely on outdated supply chain maps or ignore the nuances of anti-dumping duty structures risk significant erosion of profitability.
Conclusion and Access to Full Intelligence
The erythritol market presents a complex matrix of opportunity and risk. The growth trajectory is favorable, supported by global health trends and a CAGR of 6.5 percent, but the path to capturing value is obstructed by trade barriers and cost volatility. Success requires a granular understanding of regional dynamics, competitor capabilities, and regulatory timelines.
This overview provides a high-level strategic summary, but the full depth of the analysis resides in our complete market research report. PW Consulting's detailed study includes prognostic models, granular segmentation data by region and type, and comprehensive risk assessment frameworks that are critical for precise planning.
We invite industry leaders, investors, and supply chain executives to access the full report. The complete intelligence package offers the specific data points and confidential industry interviews necessary to build robust strategies. Do not navigate this shifting landscape with partial information. Secure the full strategic advantage by downloading the complete Erythritol Market Research report from PW Consulting today.
For detailed analysis of this topic, please visit the official page: Erythritol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com