

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Cable Assembly Market Hits $167B in 2025, Projects 6.12% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Cable Assembly Market: Strategic Intelligence for 2026 and Beyond
The global cable assembly industry stands at a critical inflection point. As connectivity demands intensify across automotive, industrial automation, and data communication sectors, manufacturers and investors require more than surface-level projections to navigate the coming growth cycle. Our latest Cable Assembly Market research delivers a structured, decision-ready intelligence framework designed specifically for enterprise strategy teams operating in 2026 and planning through 2032.
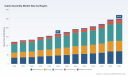
Built on a rigorous historical reconstruction spanning 2020 through 2025, the analysis establishes a verified baseline before extending forward-looking projections through the end of the decade. The market has demonstrated consistent momentum, with revenue climbing from 122.3 billion USD in 2020 to 167.0 billion USD by 2025. This trajectory reflects sustained adoption of advanced interconnect solutions, increasingly complex electronic architectures, and the ongoing migration toward higher-speed, higher-reliability transmission formats. Looking ahead, the forecast period projects a compound annual growth rate of 6.12 percent, positioning the industry to reach approximately 251.8 billion USD by 2032.
Numbers alone, however, do not capture the strategic texture of this market. What matters for leadership teams is how growth fragments across cable types, application verticals, and geographic corridors, how competitive dynamics shape pricing and capacity, and how regulatory, material, and supply-chain variables alter operational planning. This research was engineered to answer those exact questions.
The Architecture of the Report: Operational Depth Over Generic Forecasting
Many market reports stop at headline valuations and regional summaries. Our methodology deliberately goes further. The study maps the structural drivers that will determine which participants capture margin, which segments face oversupply, and where cross-functional strategy teams must allocate capital and engineering resources in the next planning cycle.
Inside the full report, readers will find:
- A granular breakdown by cable assembly type, examining how coaxial, twisted pair, fiber optic, and flat ribbon architectures are positioned across different performance thresholds, volume profiles, and design constraints.
- Application-level analysis covering automotive, data communication, industrial automation, and medical devices, with attention to the distinct qualification requirements, lifecycle expectations, and procurement patterns that define each vertical.
- Geographic demand mapping that isolates growth corridors, export-oriented production advantages, and regional compliance environments, including areas where tariff-free manufacturing and localized sourcing strategies are reshaping cost structures.
- Competitive benchmarking that evaluates how major players differentiate through product portfolios, manufacturing footprints, custom engineering capabilities, and strategic expansions into high-density semiconductor and electronics interconnects.
- Material and supply-chain context, incorporating recent observations on copper and optical fiber pricing trends, ongoing supply constraints, and the implications for contract manufacturers and electronics OEMs.
- Regulatory and standards coverage, including hazardous-environment certification frameworks, defense-sector procurement dynamics, and export-control compliance considerations that influence production planning and market access.
Each section is structured to support concrete action rather than abstract observation. Procurement leaders can use the segmentation analysis to stress-test sourcing strategies. Strategy and corporate development teams can leverage the competitive landscape mapping to identify partnership, acquisition, or geographic expansion targets. R&D and engineering management can align product roadmaps with the performance trajectories and application requirements most likely to drive volume in their respective segments.
Competitive Landscape: Differentiation, Capacity, and Recent Strategic Moves
The cable assembly market is characterized by a fragmented but increasingly sophisticated competitive field. Concentration metrics indicate that the top three players hold roughly 28.5 percent of revenue, while the top five approach 35.2 percent. This structure suggests a market where scale matters, but where specialized capabilities, custom engineering competence, and regional manufacturing agility often determine win rates in high-mix or high-reliability contract work.
Several established interconnect leaders continue to anchor the market through broad portfolios and deep application expertise. Amphenol Corporation operates across electronics, semiconductor, data communications, and high-speed applications through its communications solutions division, offering both custom and standard interconnect cable assemblies. Molex, LLC extends its positioning with custom cable assemblies, wire harnesses, and integrated interconnect solutions designed for electronics and semiconductor connectivity. TE Connectivity designs and manufactures cable assemblies and sensor interconnects tailored to electronics, semiconductor, automotive, and industrial applications, reinforcing its relevance in sectors where signal integrity and environmental durability are paramount. ICA Holdings specializes in specialty wire harnesses, cable assemblies, and electromechanical assemblies for high-mix electronics and semiconductor needs, while Meridian Cable Assemblies, LLC focuses on custom designs and manufacturing for medical, military, industrial, and electronics industries, where qualification rigor and traceability are central to customer selection.
In parallel, a strong cohort of contract manufacturers and custom assembly specialists has expanded its footprint, particularly where PCB integration, low-cost assembly, and multi-sector service capabilities create differentiated value. OurPCB provides custom cable assembly services with PCB integration spanning automotive, EV, robotics, medical, industrial, and semiconductor-related electronics. Cloom Tech specializes in custom wire harnesses and cable assemblies for automotive, aerospace, defense, robotics, and electronics sectors, and has recently strengthened its custom manufacturing capabilities for contract production serving those OEMs. SAISONIC manufactures custom cable assemblies and wire harnesses for computers, instruments, medical, machines, and electrical appliances. Romtronic produces custom cable assemblies and wire harnesses for medical, industrial automation, and automotive applications. JINNFENG Electronic Technology Co., Ltd. focuses on wire harnesses, cable assemblies, and connectors for export markets including electronics and semiconductor applications. SINNHONG Electronics Co., Limited delivers custom wire harnesses and cable assemblies with China-Vietnam manufacturing for industrial automation, consumer electronics, automotive, and communications. Wiringo manufactures custom wiring harnesses and cable assemblies for electronics, power, signal, automotive, and semiconductor applications.
Recent developments underscore how quickly competitive positioning can shift when product innovation or capacity expansion intersects with market demand. In February 2026, Molex introduced Impress Co-Packaged Copper Solutions with a compression-based on-substrate connector and mating cable assembly supporting 224Gbps PAM-4 for high-density electronics and semiconductor interconnects. This move highlights the intensifying focus on next-generation signaling performance and packaging integration. In March 2026, IWCS identified new topics for manufacturing processes of copper and optical fiber cables and innovative cable design for electronics applications, signaling continued industry attention to process improvement and design optimization. By May 2026, Cloom Tech had strengthened its custom cable assembly manufacturing capabilities for contract production across automotive, aerospace, defense, robotics, and electronics OEMs. Around the same period, WellPCB and OurPCB launched low-cost PCB assembly and custom cable assembly services for electronics and semiconductor projects, illustrating the persistent pressure to combine cost efficiency with broad application coverage.
For strategy teams, these moves are not isolated news items. They are indicators of where capability investments are flowing, which performance thresholds are becoming table stakes, and which customer segments are attracting new competition. The full report evaluates these dynamics in greater depth, connecting recent announcements to longer-term positioning and market share implications.
Market Dynamics: Regulation, Materials, and Regional Manufacturing Realities
Cable assembly markets rarely move in isolation from regulatory frameworks, material economics, and manufacturing geography. In 2026, several forces are actively shaping operational decision-making.
On the regulatory and compliance side, industry participants continue to navigate an environment where certification and export control requirements influence both product design and market access. IEC 60079 standards and related certifications remain relevant for cable assemblies deployed in hazardous environments and industrial electronics applications, creating a barrier to entry that rewards experienced manufacturers with established quality systems. At the same time, defense and aerospace procurement activity is stimulating demand in specific niches. A recent Department of Defense solicitation related to cable assembly, posted in late May 2026 with responses due in early June, illustrates how government requirements can create short-cycle opportunities while also reinforcing the importance of compliance readiness. Compliance with US Bureau of Industry and Security Export Administration Regulations and Directorate of Defense Trade Controls requirements continues to be a critical operational consideration for firms serving sensitive end markets, including those linked to Amphenol Aerospace and related facilities.
Material conditions are equally consequential. Copper and optical fiber cables used in cable assembly manufacturing are experiencing ongoing price trends alongside supply constraints within the electronics supply chain. These pressures affect cost structures, contract negotiations, and inventory planning, especially for manufacturers balancing high-mix custom work with volume commitments. Companies that can secure stable material sourcing, optimize design for material efficiency, or align product portfolios with alternative transmission architectures may gain meaningful cost and delivery advantages.
Regional manufacturing dynamics further complicate the picture. Custom cable assembly production in China and Vietnam continues to benefit from tariff-free manufacturing advantages that support global electronics export markets. For multinational buyers and contract manufacturers alike, this creates a durable cost and logistics incentive, but it also raises strategic questions about supply-chain concentration, risk mitigation, and the balance between localized production and diversified sourcing.
These dynamics do not affect all segments uniformly. Automotive, data communication, industrial automation, and medical devices each interact with regulation, materials, and geography in different ways. The report examines those interactions in detail, helping decision-makers understand not just where demand is growing, but why it is growing there, and what constraints may shape profitability.
Why This Research Matters for 2026 Decision-Making
Enterprise strategy in the cable assembly sector requires more than knowing that the market is expanding. It requires understanding which growth paths are structurally durable, which customer requirements are escalating, and where competitive intensity will compress margin unless companies act deliberately.
The 6.12 percent compound annual growth rate projected across the forecast period is a useful framing device, but the strategic value of this research lies in what sits beneath that headline. The study connects macro momentum to the specific cable types, application verticals, and geographic segments that are driving it. It situates recent product launches, capacity expansions, symposium-level manufacturing discussions, and regulatory solicitations within a coherent competitive narrative. It also highlights material constraints and compliance requirements that can determine execution risk long before demand materializes.
Fiber Optic Cable Assembly Market
For 2026 planning, this means leadership teams can approach the market with clearer hypotheses about where to invest, how to configure sourcing and manufacturing footprints, and which customer segments warrant deeper technical engagement. The research is designed to support scenario planning, procurement strategy, partnership evaluation, and product roadmap alignment in a market where performance, cost, and compliance are increasingly intertwined.
What the Full Study Delivers
The complete Cable Assembly Market report builds on the context outlined here and extends it into a comprehensive decision-support tool. It provides detailed segmentation analysis, competitive profiling, regional demand mapping, application-specific requirements, and forward-looking scenario coverage through 2032. It also integrates market concentration data, recent developments, and industry-context signals into a single analytical structure, allowing teams to compare strategic options against a consistent evidentiary baseline.
Readers seeking the full segmentation breakdowns, region- and application-level revenue detail, and complete competitive profiles will find them in the full report. That documentation is intended for teams that need to translate market intelligence into procurement plans, capacity decisions, partnership discussions, and long-range growth models.
Cable Assembly Market
Conclusion: Positioning for Informed Growth
The cable assembly market is expanding within a landscape defined by technological acceleration, material variability, regulatory complexity, and increasingly specialized competition. In that environment, strategic advantage belongs to organizations that can read the market with precision and act before structural shifts become obvious to everyone else.
Our research is built for exactly that challenge. It provides the depth required to support credible planning in 2026, while leaving the most granular intelligence available for teams ready to commit to a complete analytical framework. For executives, strategy leaders, and market development teams seeking to align their next moves with verified market direction, the full study offers the detail, structure, and operational relevance needed to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ADCP Market to Grow at 5.8% CAGR to $277M by 2032, with Europe Accounting for 74.19% Revenue
By pmarketresearch, 2026-09-15
Navigating the Currents: Strategic Imperatives in the ADCP Market Through 2032
As global hydrological and oceanographic monitoring demands intensify, Acoustic Doppler Current Profilers (ADCP) have transitioned from specialized survey instruments to critical infrastructure enablers. Our latest market research, ADCP Market: Strategic Forecast and Competitive Intelligence 2026–2032 , provides a rigorous, decision-grade assessment of an industry undergoing structural growth, technological consolidation, and supply chain recalibration. This article outlines the strategic context driving the market and demonstrates why timely intelligence on pricing, segmentation dynamics, and competitor roadmaps will separate market leaders from reactive followers in 2026.
Market Trajectory: A Decade of Structural Expansion
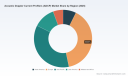
Drawing on historical data spanning 2020 through 2025 and extending our forecast horizon to 2032, the ADCP market has demonstrated consistent upward momentum. The sector breached the $140 million threshold in 2020, accelerated through the post-pandemic recovery period, and reached approximately $188 million by 2025. Our 2026 baseline projection places the market near $204 million, with growth compounding steadily across the decade to surpass the $277 million mark by 2032. This trajectory translates to a compound annual growth rate of 5.8 percent, underpinned by expanding monitoring mandates, aging coastal infrastructure requirements, and the operational necessity of precision current data in offshore, hydrological, and environmental applications.
Growth is not uniform across time or geography. The historical window reveals a market that initially rebounded through mature demand centers before broadening participation in emerging monitoring programs and specialized survey deployments. Forward-looking projections indicate that revenue acceleration will increasingly depend on procurement cycles tied to government programs, institutional research funding, and long-term infrastructure contracts rather than sporadic capital expenditure. Organizations that map their product roadmaps and go-to-market strategies against these procurement rhythms will secure a compounding competitive advantage as the decade progresses.
What This Report Delivers: Operational Intelligence for 2026 Decision-Makers
The study is engineered for executives, product leaders, and regional strategists who require more than top-line forecasts. It combines quantitative modeling with qualitative market intelligence to answer the operational questions that drive P&L outcomes, channel strategy, and R&D prioritization. Readers will gain access to:
- A detailed segmentation architecture that traces demand distribution across equipment configurations, application verticals, and regional procurement ecosystems, highlighting where volume, margin, and service revenue intersect.
- A competitive landscape evaluation that profiles incumbents and challengers, mapping product portfolios, channel strengths, and positioning across oceanographic, hydrological, navigation, offshore energy, and environmental monitoring deployments.
- A market structure assessment that quantifies concentration dynamics, revealing how share distribution, ecosystem partnerships, and technology differentiation shape bargaining power and pricing tolerance.
- Scenario-driven demand modeling that connects end-user procurement behaviors with macro forces, regulatory frameworks, and field-deployment realities, helping teams anticipate volume inflection points and contract tenor shifts.
- A technology and operations review that examines factors influencing total cost of ownership, including data-processing instrumentation economics, quality-assurance requirements in manufacturing, and the strategic implications of specialized material sourcing constraints.
- A forward-looking risk and opportunity matrix that identifies where supply continuity, certification standards, and end-user budget cycles will create divergence in performance between well-prepared and under-informed operators.
Crucially, the analysis avoids superficial aggregation. Instead, it isolates the decision variables that matter in 2026: which instrument architectures are gaining traction in specific operating environments, how application-specific requirements are reshaping configuration preferences, and where regional procurement patterns are diverging from global averages. These insights are structured to support pricing strategy, channel expansion, partnership selection, and capital allocation decisions without exposing the full depth of our quantitative models here.
Competitive Architecture: Concentration, Positioning, and Strategic Signals
The ADCP landscape is characterized by a concentrated core of established manufacturers and a surrounding layer of specialized providers, distributors, and integrators. Market concentration metrics underscore how tightly leadership is held by a handful of players, while still leaving meaningful space for differentiation through field-proven reliability, configuration flexibility, and domain-specific service capabilities. This structure rewards companies that can pair technical credibility with dependable supply, field support, and long-term maintenance relationships.
Several established players anchor the market with broad portfolios and deep deployment histories. Teledyne Marine, for example, has sustained a leadership position through a comprehensive range of current profiling systems and a global installed base that spans oceanographic research, coastal monitoring, and offshore applications. Its recent activity reflects the kind of multi-vector strategy that defines competitive resilience: continued product evolution, major monitoring program deliveries, and long-duration service and supply agreements that lock in recurring engagement with institutional buyers. Similarly, Nortek has maintained strong relevance through portable and self-contained profilers tailored to hydrological monitoring and coastal surveys, while Xylem Inc., through its SonTek and Aanderaa affiliates, has strengthened its footprint among research institutions, environmental consultancies, and disaster-response operations with high-precision profiling solutions.
The competitive field also includes providers that compete on form factor, deployment simplicity, and integration. LinkQuest emphasizes battery-powered, lightweight instruments suited to shallow-water surveys and extended field campaigns, while RBR Ltd. combines ADCP capabilities with CTD integration for oceanographic assessments and monitoring networks. Falmouth Scientific, Valeport, ASL Environmental Sciences, and Ocean Scientific International each contribute domain-specific credibility across research vessels, long-term moorings, port navigation, and institutional programs. Meanwhile, Kongsberg Maritime, Sonardyne, Sea-Bird Scientific, and Hydroptic illustrate the breadth of deployment models, from vehicle-mounted and stationary configurations to sensor-integrated packages and renewable-energy-focused environmental projects.
Acoustic Doppler Current Profilers (ADCP) Market
For strategists, the critical insight is not simply who leads today but how competitive advantage is being built. Differences in manufacturing quality controls, data-processing ecosystem compatibility, battery and power management, and the ability to support multi-year deployments are increasingly decisive. Procurement teams are evaluating not just instrument accuracy, but total operating burden, service responsiveness, and the resilience of the supplier’s supply chain. Organizations that can articulate and deliver on these dimensions will shape pricing conversations and win share in the highest-value contracts.
Worldwide Hydrophone Market
Market Dynamics: Cost Structures, Quality, and Supply Chain Sensitivity
Beyond segmentation and competition, the market is being shaped by operational realities that affect both suppliers and end users. Data-processing and automation tooling represent one of the practical cost drivers that influence adoption decisions. Instruments such as automated samplers and chemistry analyzers used in ADCP-related data processing workflows carry substantial per-unit cost ranges, reinforcing the importance of integrated solutions and service models that reduce the hidden burden of field-to-office workflows. In parallel, quality-management discipline continues to matter. Demonstrated adherence to recognized manufacturing quality standards signals reliability in production consistency, a factor that resonates strongly with institutional buyers and long-duration program managers.
Supply-side considerations are equally important. The ADCP industry has noted vulnerabilities in specialized piezoelectric transducer materials, creating a strategic dimension around procurement diversification, inventory planning, and design resilience. Companies that proactively manage these dependencies are better positioned to protect delivery timelines and margin stability during periods of demand acceleration. On the demand side, government and defense segments continue to represent a meaningful share of end-user demand in oceanographic monitoring, reinforcing the role of public procurement cycles, institutional budgets, and program-led purchasing in shaping near-term volume patterns.
Together, these dynamics create a market where performance is defined by a combination of product credibility, operational reliability, and procurement agility. The firms that will outperform are those that can align product roadmaps with the practical economics of deployment and data handling while anticipating sensitivity points in the materials and manufacturing base.
Strategic Outlook for 2026: Where Intelligence Converts into Advantage
The 2026 operating environment will reward disciplined interpretation of demand signals and rapid alignment of commercial strategy to procurement realities. Several themes will define the year for ADCP market participants:
- Procurement cycles are becoming more program-centric, with multi-year monitoring and offshore operations creating opportunities for sustained engagement rather than transactional sales. Long-duration contracts and service attachments will increasingly determine lifetime value.
- Instrument configuration preferences are being driven by application realities, ranging from portable field deployments to deep-water and integrated sensor packages. Differentiation will depend on matching technical capability to the operational constraints of each use case.
- Total cost of ownership will continue to matter as much as instrument performance. Data-processing economics, field-service responsiveness, and the reliability of supply chains for specialized components will influence purchasing decisions at the program level.
- Regional demand patterns will diverge based on institutional priorities, coastal and hydrological monitoring mandates, and energy-sector activity. Understanding where procurement power sits and how budgets are structured will be essential for market entry and expansion planning.
- Competitive intensity will be shaped by concentration dynamics, meaning that positioning, partnership strategy, and service differentiation will be as important as hardware specification in contested segments.
These themes are not abstract; they directly affect pricing strategy, resource allocation, channel investment, and risk management. Leaders who act on them early will be able to prioritize the contracts, configurations, and geographies that generate the strongest returns, while avoiding the temptation to compete across every dimension simultaneously.
Why the Full Study Matters Now
The ADCP market is entering a phase where growth is increasingly earned through operational excellence and strategic positioning rather than broad-based expansion alone. Our full report provides the underlying segmentation detail, regional and application-level demand context, competitive intelligence, and scenario analysis required to make informed decisions in 2026 and beyond. It connects the macro trajectory with the micro decisions that determine market performance: which configurations to prioritize, where to concentrate field support, how to frame value against total operating cost, and which competitive moves will protect margin in a concentrated landscape.
The quantitative foundation of the study reflects a market moving from approximately $204 million in 2026 toward more than $277 million by 2032, with a 5.8 percent CAGR guiding the forecast architecture. But the strategic value lies in what sits beneath that trajectory: the distribution of demand across configurations and applications, the concentration of competitive power, the cost and supply sensitivities that shape delivery and pricing, and the procurement behaviors that determine which programs scale and which stall. These elements are developed in depth within the report, with the granularity required for executive planning, product strategy, and regional expansion decisions.
Conclusion
As organizations plan for the next phase of ADCP market development, the margin between reactive positioning and proactive strategy will narrow. Demand is expanding, competition is concentrated, and the operational realities of deployment, data handling, and supply continuity are becoming central to commercial success. Our ADCP Market research is designed to give leadership teams a clear, evidence-based view of where value is being created and how to capture it. For executives seeking the full segmentation architecture, competitive profiling, and scenario detail needed to act with confidence in 2026, the complete study offers the strategic intelligence required to navigate the next wave of growth on favorable terms.
For detailed analysis of this topic, please visit the official page: Acoustic Doppler Current Profilers (ADCP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phycocyanin Market Hits $175M in 2025, Projected 7.3% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Phycocyanin Market: Navigating the 2026 Decision Landscape
The global phycocyanin market is entering a critical inflection point. Market research published by PW Consulting reveals a sector that has evolved from a niche natural colorant segment into a strategically vital component of the broader clean-label ingredient landscape. With established historical trajectories and a clearly defined forecast horizon extending through 2032, this market presents both structural opportunity and execution complexity for executives across food, beverage, nutraceutical, cosmetic, and pharmaceutical value chains. This intelligence briefing outlines the strategic contours of the phycocyanin market and explains why a methodical, forward-looking market assessment is indispensable for 2026 enterprise decision-making.
The Macro Trajectory: A Market Built on Sustained Momentum
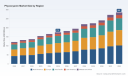
Historical performance from 2020 through 2025 establishes a consistent growth narrative. The overall market has expanded from approximately 121.5 million USD in 2020 to a base-year valuation of 175.0 million USD in 2025. This progression reflects more than cyclical demand fluctuation; it signals a structural repositioning of phycocyanin as a mainstream functional ingredient. The compound annual growth rate of 7.3 percent during the historical window underscores steady adoption across multiple downstream sectors, supported by shifting consumer preferences toward plant-derived colorants and bioactive extracts.
The forward-looking trajectory from 2026 to 2032 extends this momentum into a clearer strategic horizon. The forecast period projects continued valuation expansion, opening from 182.23 million USD in 2026 and advancing toward 285.0 million USD by 2032. For corporate strategists, this is not merely a growth projection. It is a planning framework that demands alignment across supply chain architecture, formulation strategy, regulatory compliance, and geographic market prioritization. The consistency of the trajectory suggests that phycocyanin is transitioning away from speculative positioning into a category where operational readiness and market intelligence directly influence competitive positioning.
Executing in this environment requires more than awareness of headline figures. It requires an understanding of where value is concentrated, which application channels are accelerating, how form-factor preferences are evolving, and which regional ecosystems are shaping procurement and distribution pathways. A comprehensive market study supplies the structural context necessary to convert macro growth signals into actionable corporate strategy.
Why Market Intelligence Matters for 2026 Decision-Making
Strategic planning cycles for 2026 cannot rely on historical benchmarks alone. The phycocyanin category sits at the intersection of regulatory evolution, raw material economics, manufacturing capacity expansion, and formulation innovation. Each of these dimensions carries distinct implications for cost structure, compliance risk, product positioning, and market entry timing. Organizations seeking to allocate capital, portfolio resources, or R&D effort must therefore understand the underlying mechanics of the market rather than reacting to surface-level demand narratives.
The most consequential strategic decisions in this space will depend on precise segmentation understanding, competitive benchmarking, and regulatory impact mapping. Executives need clarity on how application channels are diverging in terms of volume, formulation requirements, and price sensitivity. They need visibility into how form preferences are shaping extraction technology investments and downstream processing capabilities. They need insight into regional market behavior without falling into the trap of treating geographic growth as a uniform metric. And they need to account for concentration dynamics that influence pricing power, supplier dependency, and negotiation leverage.
When these elements are assessed in isolation, strategic planning becomes fragmented. A well-constructed industry study consolidates them into a coherent decision framework, allowing leadership teams to evaluate trade-offs, stress-test assumptions, and prioritize initiatives with greater confidence. In that sense, the value of the research is not limited to data access. It lies in the translation of complex market architecture into a usable blueprint for strategy execution.
Competitive Architecture and Strategic Dynamics
The phycocyanin ecosystem reflects a diverse competitive landscape spanning vertically integrated algae cultivation, specialty extraction expertise, and large-scale ingredient distribution. Among the organizations defining competitive intensity are DIC Corporation, Earthrise Nutritionals, Cyanotech Corporation, DDW Inc., GNT Holding B.V., Sensient Technologies Corporation, Parry Nutraceuticals Limited, Fuqing King Dnarmsa Spirulina Co., Ltd., Dongtai City Spirulina Bio-Engineering Co., Ltd., Viridia Biotech, Zhejiang Binmei Biotechnology Co., Ltd., Tianjin Norland Biotech Co., Ltd., Far East Bio-Tec Co., Ltd., and Naturalin Bio-Resources Co., Ltd.
These players illustrate the multidimensional nature of the market. Some competitors derive advantage from integrated spirulina farming and extraction operations that reduce feedstock exposure and improve supply consistency. Others compete through purification technology, standardized food-grade extract portfolios, or specialized formulation capabilities tailored to industrial beverage, processed food, and nutraceutical applications. The presence of both established multinational players and regional manufacturers indicates that competitive advantage is not determined by scale alone. It is increasingly shaped by production efficiency, quality assurance, certification readiness, and the ability to meet application-specific formulation requirements.
Recent operational developments reinforce this competitive complexity. In March 2025, DIC Group subsidiary Earthrise Nutritionals inaugurated a new sustainable algae cultivation facility in California using smart-farming technologies for spirulina biomass and phycocyanin production. This expansion signals a strategic emphasis on cultivation modernization, sustainability positioning, and capacity resilience. Such investments matter because feedstock economics directly influence cost discipline, supply reliability, and margin protection, particularly given that spirulina biomass prices can vary substantially depending on quality, sourcing, and market conditions.
Market concentration data further shapes the strategic picture. With the top three firms accounting for approximately 48 percent and the top five firms reaching roughly 58 percent of market revenue, the category displays meaningful concentration while still retaining a broad field of active participants. For procurement leaders and product developers, this structure has practical implications. It suggests that supplier diversification strategies, technical qualification processes, and contractual negotiation approaches must be calibrated carefully, especially when sourcing high-purity extracts or standardized colorant inputs for regulated product categories.
The competitive environment is not static. Suppliers are competing not only on color performance but also on extraction consistency, batch stability, certification frameworks, and the ability to support downstream innovation. As a result, strategic assessments must evaluate competitor positioning dynamically, accounting for capacity plans, technology differentiation, and the evolving demands of application developers.
Regulatory and Market Dynamics: Navigating Uncertainty and Opportunity
Regulatory developments are reshaping the commercial boundaries of the phycocyanin market. In February 2026, the U.S. Food and Drug Administration updated the listing of color additives exempt from certification to include Spirulina Extract containing phycocyanin, with amended use provisions in human foods. This regulatory milestone potentially expands formulation flexibility and market access for manufacturers seeking to integrate natural blue colorants into food applications with clearer compliance pathways.
The same listing process included a delayed effective date announced in March 2026 to allow further review and objection periods. For strategic planners, this sequence illustrates an important reality: regulatory clarity does not arrive as a single event but as a phased process with operational consequences. Companies that monitor the timeline, understand the scope of amended use provisions, and prepare formulation or labeling adjustments in advance are better positioned to align product development cycles with compliance readiness. In contrast, organizations that treat regulatory changes as administrative details risk missed market windows or reactive restructuring under time pressure.
Beyond regulation, raw material dynamics remain central to commercial planning. Spirulina biomass, the primary feedstock for phycocyanin extraction, is subject to pricing variability that depends on quality and sourcing parameters. This creates a direct link between cultivation practices, extraction yields, purification efficiency, and final product economics. Strategic procurement and production planning must therefore address feedstock volatility through supplier qualification, contract design, and, where relevant, vertical integration or partnership models that improve cost predictability.
Trade classification and tariff considerations add another layer of operational relevance. Phycocyanin extracts and spirulina-based colorants sourced from China are subject to standard tariff classifications for natural pigments and colorants. For companies managing cross-border sourcing, formulation localization, or export strategy, understanding classification pathways and customs treatment is essential to avoid cost surprises and maintain supply continuity.
Taken together, these dynamics show that phycocyanin market strategy cannot be built solely around product performance or consumer trend alignment. It must also address compliance sequencing, feedstock economics, sourcing risk, and trade architecture. The organizations that succeed will be those that integrate regulatory monitoring and supply chain resilience into the core of their commercial planning.
What an Actionable Market Study Delivers
A robust market analysis for phycocyanin must go beyond aggregate projections. It should provide functional decision support across multiple strategic workstreams. The most useful studies are structured to translate market behavior into operational clarity, giving executive teams the inputs needed for portfolio planning, competitive positioning, and resource allocation.
At a foundational level, the analysis should map historical and forecast revenue trends with enough granularity to support scenario planning without exposing organizations to overgeneralized assumptions. It should segment the market by form, application, and region in a way that reveals where value is migrating and which pathways are attracting the strongest adoption signals. This includes understanding how powder and liquid formats are positioned across different formulation and distribution environments, and how application channels such as food and beverages, nutraceuticals, cosmetics, and pharmaceuticals differ in terms of growth character, technical requirements, and commercialization constraints.
Equally important is the competitive section of the study. Effective analysis should differentiate between competitor types, summarize strategic postures, and contextualize recent developments that affect capacity, technology direction, and market momentum. Rather than treating corporate profiles as static summaries, the study should frame them as indicators of strategic intent and operational evolution. This allows readers to identify who is expanding capability, who is emphasizing sustainability or purification technology, and where gaps or opportunities may exist in the competitive field.
Regulatory and raw material context should be woven into the market dynamics discussion rather than isolated as background noise. That includes commentary on color additive exemption developments, amended use provisions, compliance timing, feedstock cost variability, and the trade classification implications of international sourcing. These elements matter because they shape both the speed and the cost of market entry, product reformulation, and supplier qualification. A well-designed study connects these dynamics directly to strategic implications, enabling decision-makers to anticipate operational friction and prepare response plans.
Finally, the most valuable research should help executives answer practical questions: Where should capacity or partnership investment be prioritized? Which application channels offer the clearest near-term commercialization path? How should procurement teams structure sourcing to balance cost, quality, and supply resilience? Which regulatory developments require immediate compliance attention, and which require monitoring? The ability to answer such questions depends on an analytical framework that integrates market size, segmentation behavior, competitor structure, and regulatory context into one coherent view.
Strategic Imperatives for the 2026 Planning Cycle
For organizations operating in or evaluating the phycocyanin market, the 2026 planning cycle represents a moment to move from observation to deliberate positioning. The convergence of sustained market growth, regulatory refinement, capacity expansion, and feedstock variability creates both opportunity and execution risk. Companies that treat this moment as a data-driven planning opportunity will be better equipped to make defensible decisions about product development, sourcing strategy, geographic focus, and competitive differentiation.
One strategic imperative is to align product and formulation roadmaps with the evolving application landscape. Natural colorant adoption does not progress uniformly across categories. Each application environment imposes distinct performance thresholds, stability requirements, labeling expectations, and procurement criteria. Understanding how these requirements differ enables more precise portfolio design and reduces the likelihood of misaligned commercialization efforts.
A second imperative is to strengthen supply chain and sourcing strategy against feedstock volatility and regulatory timing uncertainty. Whether through diversified supplier qualification, contractual structuring, or strategic partnerships, procurement and operations teams must build resilience that supports consistent quality while protecting cost competitiveness. In a market where cultivation and extraction efficiency directly affect margin outcomes, supply strategy is not administrative support. It is a competitive lever.
Phycocyanin Market
A third imperative is to incorporate regulatory intelligence into product launch and market entry planning. The recent FDA color additive exemption developments and the associated effective-date adjustments illustrate that compliance pathways can evolve in phases. Organizations that integrate regulatory monitoring into their planning cadence can sequence formulation work, labeling updates, and commercial rollout with greater predictability.
A fourth imperative is to evaluate competitive positioning with a longer time horizon. Capacity investments, purification technology development, sustainability initiatives, and application-specific standardization efforts are shaping the future structure of the market. Strategic decisions made in 2026 should reflect not only current competitor behavior but also the direction of capability building across the field.
Conclusion: From Market Awareness to Strategic Execution
The phycocyanin market is no longer an emerging curiosity. It is a growing, regulated, supply-sensitive ingredient category with meaningful implications for food, beverage, nutraceutical, cosmetic, and pharmaceutical innovation. The historical record demonstrates durable expansion, and the forecast horizon suggests that this trajectory will continue to reward organizations that invest in informed strategic planning.
Yet the strategic value of this market can only be realized when executives have access to a detailed, structured, and operationally relevant market study. Aggregate figures provide direction, but they do not by themselves enable sourcing strategy, formulation prioritization, compliance sequencing, or competitive differentiation. A comprehensive research report bridges that gap by converting market behavior into decision-ready intelligence.
Phycobiliprotein Market
PW Consulting's detailed Phycocyanin Market research is designed to provide exactly that depth. It examines the structural drivers, segmentation dynamics, competitive actions, and regulatory developments that define the category, while preserving the analytical precision required for serious strategic planning. Readers seeking the full segmentation view, complete application and form analysis, regional market context, and detailed competitor evaluation are encouraged to access the complete study through the original report page, where the full dataset and strategic discussion are available. In a market moving at this pace, the difference between reactive positioning and informed execution often comes down to the quality of the intelligence behind the decision.
For detailed analysis of this topic, please visit the official page: Phycocyanin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium Metal Market Poised for 16% CAGR to Hit $7.29 Billion by 2032
By pmarketresearch, 2026-09-15
The Lithium Metal Market Outlook 2026: Strategic Intelligence for Next-Generation Energy Decisions
Executive Overview
The global energy transition is entering a decisive phase where material science and supply chain resilience determine competitive advantage. Lithium metal has emerged as a foundational enabler for high-energy-density storage systems, advanced alloys, and next-generation electrochemical applications. Our latest Lithium Metal Market research provides a comprehensive, forward-looking assessment of an industry experiencing structural acceleration. With a compound annual growth rate of 16.0 percent spanning the forecast horizon through 2032, the market trajectory reflects deepening integration across battery innovation, materials engineering, and regional supply chain reconfiguration. This article outlines the strategic rationale behind the study, highlights the analytical architecture, and demonstrates how enterprise leaders can convert macro-level intelligence into actionable 2026 planning.
Macro Trajectory and Market Scale
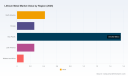
Historical performance from 2020 through 2025 illustrates a consistent expansion pattern, with revenue climbing from 1.5 billion USD to 2.6 billion USD. The acceleration observed in the base year establishes a strong foundation for the forecast period, during which valuations are projected to move from 3.04 billion USD in 2026 toward 7.29 billion USD by 2032. This scale of growth is not merely a function of incremental demand but reflects a broader technology shift toward lithium metal anodes, high-purity metallic inputs, and specialized alloy applications.
The market structure reveals meaningful concentration dynamics. Top-tier participants collectively account for a dominant share of revenue, indicating an industry where scale, process expertise, and supply chain control create durable barriers to entry. Yet concentration does not equate to stasis. Strategic partnerships, localized production initiatives, and novel refining pathways are actively reshaping competitive positioning. For decision-makers, the critical insight lies in recognizing how concentration interacts with innovation velocity: incumbents leverage manufacturing maturity while emerging players target niche performance requirements and regional supply chain independence.
Segmentation Landscape and Application Drivers
The Lithium Metal Market unfolds across distinct product forms and end-use categories. Ingots represent the dominant volume format, serving as the primary input for downstream processing and battery manufacturing. Powder and other specialized forms cater to increasingly precise electrochemical formulations, where particle morphology, purity thresholds, and surface characteristics directly influence cell performance. This structural split underscores a broader trend: customers are no longer purchasing commoditized material alone. They are procuring tailored material properties that support specific energy-density targets, thermal behavior profiles, and cycle-life requirements.
Lithium-Metal Secondary Battery Market
Application demand is heavily anchored by battery systems, which continue to command the largest share of market absorption. Alloys and other specialized applications provide meaningful supplementary vectors, supporting advanced material combinations, thermal management strategies, and specialized engineering use cases. Importantly, the relationship between application categories and growth is not linear. Battery advancement cycles, platform qualification timelines, and form-factor transitions introduce phased demand patterns that require granular planning. Our research captures these nuances by mapping application pathways to material specifications, manufacturing readiness, and regional procurement behavior without reducing the market to oversimplified share percentages.
Regional Dynamics and Supply Chain Reconfiguration
Geographically, the market reflects a diversified but unevenly distributed footprint. Asia Pacific anchors the largest portion of activity, reflecting dense manufacturing ecosystems, strong downstream demand, and rapidly scaling production capabilities. North America, Europe, Latin America, and the Middle East and Africa each contribute distinct strategic value, whether through localized supply chain initiatives, regulatory-driven procurement shifts, or specialized application clusters.
Regional analysis in this study is framed around operational realities rather than static share figures. Factors such as localized production investments, logistics constraints, material sourcing strategy, and regulatory alignment determine how demand translates into procurement decisions. The focus is on where capability is building, where dependency risks exist, and how companies can position themselves to access the right material streams under shifting trade and compliance conditions.
Recent Industry Developments and Strategic Signals
Recent operational milestones demonstrate how quickly the competitive landscape is evolving. In April 2025, a leading U.S. innovator initiated domestic production of battery-grade lithium-metal alloys and foils, establishing a fully localized, tariff-free supply chain using domestically produced alloys and sourced lithium metal. By November 2025, another vertically integrated player secured a Saudi patent covering its pure lithium metal production and lithium battery manufacturing technology, reinforcing the importance of intellectual property in advanced materials business models.
Moving into 2026,execution momentum continued. In January 2026, a sustainable refining company signed a multi-year material supply agreement for battery-grade lithium carbonate produced through its proprietary refining process, illustrating how recycling and refining innovation are being embedded directly into supply contracts. In February 2026, a composite anode materials developer and a battery technology partner formalized a memorandum of understanding to commercialize next-generation lithium-metal batteries, building on scale-up progress achieved during the prior year.
These developments share a common strategic theme: companies are reducing exposure to volatile intermediate markets by strengthening vertical integration, protecting process innovation, and securing supply agreements aligned with downstream qualification cycles. For enterprise planners, the implication is clear. Procurement strategy, partnership selection, and technology roadmapping must now account for a market where localized production, IP-protected processes, and closed-loop refining are becoming competitive differentiators.
Regulatory and Raw Material Context
Market behavior does not unfold in isolation from regulatory and commodity dynamics. Transportation compliance continues to shape logistics planning for lithium metal and lithium-ion batteries. As of January 2026, updated guidance introduced revised classification flowcharts, new test summaries, and modified state-of-charge requirements for packed equipment and lithium metal battery shipments. These changes affect packaging design, freight qualification, warehousing protocols, and cross-border shipment timelines. Firms that treat compliance as a static checklist risk operational friction; firms that integrate regulatory evolution into product launch planning and supply chain design gain predictability.
Raw material pricing also remains a relevant planning input. Market data from mid-2026 indicates lithium carbonate pricing declining to approximately 163,000 CNY per ton, reflecting a month-over-month contraction. While lithium metal markets are not perfectly synchronized with carbonate pricing, such movements influence input cost expectations, procurement timing, contract negotiation posture, and internal investment hurdle rates. The relationship is nuanced: different product forms, purity specifications, and supply routes create varying degrees of exposure. Our research addresses these sensitivities by examining how pricing trends interact with material grade requirements, regional sourcing options, and long-term contract structures.
Competitive Landscape: Differentiated Capabilities and Strategic Positioning
The competitive field spans established multinationals, specialty materials innovators, and vertically integrated challengers. Each participant is shaping the market through a distinct value proposition.
- Albemarle Corporation emphasizes ultra-thin lithium metal anodes designed for high-energy-density solid-state and lithium-metal battery platforms, positioning process precision as a performance enabler.
- Ganfeng Lithium Group Co., Ltd. focuses on high-purity lithium metal produced via oil-free vacuum melting and low-temperature vacuum distillation, reflecting an emphasis on purity control and process discipline.
- Pure Lithium Corporation pursues vertically integrated pure lithium metal anodes and batteries using brine-to-battery technology, linking upstream sourcing directly to downstream cell production.
- Lyten Inc. targets battery-grade lithium-metal alloys and foils for U.S.-localized lithium-sulfur batteries, aligning material development with regional supply chain objectives.
- Aqua Metals, Inc. contributes battery-grade lithium carbonate and nickel metal through its AquaRefining process, integrating sustainable recycling and refining into the material supply chain.
- Soelect advances lithium-metal composite anode materials for advanced high-energy-density batteries, focusing on material formulations that support next-generation cell architectures.
- Elevated Materials develops ultra-thin lithium metal films for commercial battery programs, addressing the growing demand for precision-format metallic inputs.
- Cuberg concentrates on lithium-metal cell technology for ultra-safe, high-energy-density modules in aviation and vertical takeoff and landing applications, linking material performance to demanding transport and mobility requirements.
The strategic takeaway is not simply that competition is intense, but that competition is multidimensional. Some players compete on purity and process control. Others compete on integration, localization, recycling, or application-specific cell architecture. As a result, procurement teams and technology strategists must evaluate partners against more than volume or price. Material consistency, qualification support, IP positioning, and supply continuity under regulatory change are equally relevant.
What the Report Delivers: Operational Intelligence for 2026 Planning
This study is designed as a decision-support instrument, not a broad overview. It translates market-scale data into operational context by mapping growth vectors to the practical questions enterprise teams face when planning for 2026 and beyond. The report includes analysis covering demand drivers by application pathway, product-form preferences and their manufacturing implications, regional capability building and procurement relevance, and competitive positioning based on technology readiness, integration strategy, and supply chain design.
Beyond structural assessment, the report integrates development tracking that connects corporate milestones to market consequences. Patent grants, localized production launches, multi-year supply agreements, and commercialization partnerships are examined for what they reveal about capability maturity, supply chain directionality, and the pace of market entry. Regulatory updates and raw material pricing movements are incorporated where they affect planning assumptions, with attention to how compliance shifts influence logistics and how input cost dynamics shape negotiation and sourcing strategy.
The objective is to give strategy, procurement, and technology leaders a coherent framework for evaluating opportunity, risk, and timing. Rather than leaving decision-makers with isolated figures, the study provides the connective tissue needed to interpret growth in terms of actionable market behavior: which material specifications are gaining relevance, where regional supply chain shifts are accelerating, how concentration affects access and negotiation leverage, and which development patterns indicate near-term capacity or partnership opportunities.
Lithium Metal Market
Strategic Implications for 2026 Enterprise Decisions
For organizations operating in or adjacent to the Lithium Metal Market, the 2026 planning cycle should be informed by three overarching priorities. First, align material sourcing with technology roadmaps. As battery platforms and alloy formulations continue to advance, procurement specifications increasingly need to reflect performance-sensitive characteristics rather than generic commodity procurement.
Second, incorporate regulatory and logistics evolution into product and supply planning. Updated transportation guidance, classification requirements, and state-of-charge constraints affect launch timing, packaging design, and distribution strategy. Companies that build compliance-aware supply planning into their operational cadence reduce execution risk.
Third, evaluate partnership and investment choices through the lens of integration and differentiation. Vertical integration, localized production, sustainable refining, and IP-protected processing are no longer peripheral initiatives. They are becoming core elements of supply reliability and competitive positioning. The market concentration pattern reinforces the importance of selecting partners with credible scale, process control, and continuity strategy, while the emergence of specialized innovators signals where tailored solutions and application-specific alliances may create advantage.
Conclusion
The Lithium Metal Market is moving with sufficient velocity and structural complexity that broad narratives are no longer sufficient for high-stakes planning. Growth, concentration, regional reconfiguration, regulatory updates, and corporate execution are interacting in ways that require a more disciplined intelligence framework. Our research provides that framework by linking macro trajectory to operational relevance, translating recent developments into strategic signals, and identifying the decision points that matter most for 2026.
For leaders who need the full analytical breakdown—detailed segmentation interpretation, regional capability mapping, competitive profiling, regulatory impact assessment, and development tracking with market implications—the complete report offers the depth required to convert insight into action. The market is expanding, differentiating, and reorganizing around integration, purity, localization, and application specificity. Access the full study to ground your next planning cycle in comprehensive, decision-ready intelligence.
For detailed analysis of this topic, please visit the official page: Lithium Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saw Wire Market to Reach $344.8M by 2032, Growing at 6.98% CAGR from 2025
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Saw Wire Market: Navigating Growth Trajectories Through 2032
The industrial landscape of precision cutting and material processing is undergoing a significant transformation. As manufacturing tolerances tighten and the demand for high-quality semiconductors and construction materials escalates, the saw wire market has emerged as a critical enabler of industrial efficiency. For executive leaders and strategic planners, understanding the nuances of this sector is no longer optional; it is a prerequisite for sustainable growth.
PW Consulting is pleased to introduce our latest comprehensive market research study focused on the Saw Wire Market. This report is designed not merely as a data repository, but as a strategic tool for decision-making in 2026 and beyond. By analyzing historical performance from 2020 through 2025 and projecting forecasts until 2032, we provide a clear lens through which stakeholders can evaluate opportunities, risks, and competitive positioning.
Market Trajectory and Growth Dynamics
The historical data indicates a robust expansion phase for the saw wire industry. Between 2020 and 2025, the market demonstrated consistent resilience and upward momentum, overcoming global supply chain disruptions and shifting economic conditions. This historical foundation sets the stage for the forecast period spanning 2026 to 2032.
Our analysis projects a Compound Annual Growth Rate (CAGR) of approximately 6.98 percent during the forecast period. This growth trajectory suggests that the market will evolve from a valuation of roughly 235.21 million USD in 2026 to nearly 344.8 million USD by 2032. For investors and corporate strategists, this implies a sustained demand environment where capacity expansion and technological innovation will be key differentiators. The steady climb in revenue underscores the material's integral role in high-value industries such as semiconductor manufacturing and advanced construction.
However, raw numbers only tell part of the story. The strategic value lies in understanding the velocity of this growth across different vectors. Our research digs into the underlying drivers that will sustain this CAGR, identifying where capital allocation will yield the highest returns. Leaders who grasp the timing of these demand waves will be better positioned to secure supply chains and optimize production schedules.
Report Scope and Operational Content
To support nuanced decision-making, this report offers a granular examination of the market ecosystem. We have structured the research to address the specific informational needs of procurement officers, product managers, and investment analysts. The study moves beyond top-line estimates to explore the mechanics of market behavior.
Key components of the analysis include:
- Historical Baseline Analysis: A detailed review of market performance from 2020 to 2025, establishing the baseline against which future growth is measured. This section contextualizes the recent recovery and stabilization phases following earlier global disruptions.
- Forecast Modeling: Projections extending to 2032 that account for varying economic scenarios. This allows stakeholders to stress-test their strategies against potential shifts in demand or regulatory environments.
- Segmentation Deep Dives: While maintaining confidentiality on specific proprietary splits, the report analyzes the structural composition of the market. We examine the relative weight of different material types and industrial applications, highlighting which segments are driving the bulk of revenue generation.
- Regional Performance Overview: The study assesses market attractiveness across major geographic zones. We evaluate how local industrial policies, infrastructure development, and manufacturing hubs influence regional revenue contributions without disclosing specific localized percentage shares.
- Competitive Intelligence: A thorough profiling of key market participants, analyzing their strategic moves, product portfolios, and geographic footprints.
By integrating these elements, the report serves as a single source of truth for stakeholders who need to align their internal strategies with external market realities.
Competitive Landscape and Corporate Strategies
The saw wire market is characterized by a mix of specialized manufacturers and diversified industrial giants. Our research identifies a competitive environment where innovation in diamond wire technology and steel composition is paramount. The market concentration indicates a fragmented yet strategically clustered environment, with the top players holding significant but not absolute sway over market direction.
Worldwide Wire Saw Market
We have identified several core enterprises that define the current competitive landscape. Firms like Well Diamond Wire Saws SA, based in Switzerland, have long established reputations for precision stainless steel wires and cutting technology since 1974. Their focus on stone and concrete applications highlights the enduring importance of construction and material processing sectors. Similarly, Asahi Diamond Industrial Co. from Japan represents the high-tech end of the spectrum, leading production of diamond wires for semiconductor wafer slicing and solar photovoltaic industries.
Other significant players include Noritake Co. Limited, also in Japan, which specializes in diamond wires and consumables for industrial sawing, and SOMOS IWT in the United States, which targets semiconductor and crystal precision applications. European presence is maintained by companies like Husqvarna Construction in Sweden, supplying premium diamond wires for concrete and marble, and Diamond WireTec, offering coil and loop options across various materials.
The United States hosts a diverse range of specialists, including MTI, known for electroplated diamond wires for scientific cutting, and Princeton Scientific Corp, focusing on lab and professional settings. Taiwanese manufacturer Ensoll Tools contributes with diamond wire saw machines, while France-based Thermocompact provides industrial diamond wire saws for professional applications. Additionally, Wire Saw Solutions Group acts as a crucial distributor and service provider, facilitating access to brands like Well Diamond.
Recent developments underscore the dynamic nature of this competition. In June 2025, Schwing introduced the MDS 5034 mobile diamond wire saw, specifically designed for on-site cutting of large natural-stone blocks in mining applications. This launch signals a push towards mobility and on-site efficiency in the mining sector. Furthermore, in late 2025, Zhejiang Jingsheng Mechanical and Electrical launched a diamond line project focused on expansion into semiconductor material and equipment manufacturing, indicating a strategic pivot towards high-growth tech sectors.
Saw Wire Market
Understanding the moves of these key companies provides valuable insight into where the industry is heading. Their investments in R and D, capacity expansion, and geographic reach serve as leading indicators for market trends. Our report analyzes these strategic maneuvers to help clients anticipate competitor actions and identify potential partnership or acquisition opportunities.
Raw Material and Regulatory Headwinds
Strategic planning in the saw wire market must account for external forces that influence cost structures and operational feasibility. Raw material volatility remains a critical concern. Recent data indicates that hot-rolled coil steel prices reached approximately 1,040 USD per ton in the week of April 2026, representing a notable increase from 905 USD per ton in the equivalent week of 2025. This upward pressure on steel costs directly impacts the production economics of wire saws.
Compounding this issue, the Producer Price Index for carbon steel wire drawing rose to 299.798 in April 2026 from 289.227 in February 2026. These inflationary trends suggest that manufacturers may need to adjust pricing strategies or invest in efficiency improvements to maintain margins.
Regulatory dynamics are equally influential. China's General Administration of Customs introduced an export license management system for steel products under at least 100 HS codes, effective January 1, 2026. This move could alter global supply chains and availability of raw materials. In Europe, the European Chemicals Agency updated the REACH SVHC candidate list to 253 substances in February 2026, impacting chemical and material compliance for wire production. Additionally, EU Regulation (EU) 2026/261 on phasing out Russian natural gas imports entered into force in January 2026, affecting global energy-related material supply chains.
These factors create a complex operating environment. Companies that proactively adjust their supply chain strategies and compliance frameworks will be better equipped to navigate these headwinds. Our report details how these regulatory and cost factors intersect with market demand to shape overall profitability.
Strategic Implications for 2026 Decision Makers
For leaders operating in 2026, the Saw Wire Market presents a landscape of calculated opportunity. The projected growth to 344.8 million USD by 2032 offers a compelling case for investment, but success will depend on precise execution. Strategic priorities should include securing stable raw material sources amidst price volatility, aligning product development with high-growth segments like semiconductor manufacturing, and monitoring regulatory shifts in key regions like China and the EU.
The fragmentation of the competitive landscape, with a CR3 of 24.6 percent and CR5 of 26.2 percent, suggests that there is room for consolidation or for niche players to capture significant value through specialization. Companies that can offer superior cutting technology or specialized consumables for precision applications will likely command premium positioning.
Furthermore, understanding the regional nuances without relying solely on aggregate numbers is crucial. Whether it is the industrial demand in Asia Pacific, the established infrastructure in North America, or the emerging opportunities in Latin America and the Middle East, each region presents unique challenges and rewards. Our report provides the contextual depth needed to evaluate these regions effectively.
Conclusion
The Saw Wire Market is at an inflection point where industrial demand, technological innovation, and regulatory complexity converge. PW Consulting's latest market research offers the depth and clarity required to navigate this environment. By leveraging our detailed analysis of market size, growth rates, competitive moves, and external dynamics, stakeholders can make informed decisions that drive long-term value.
We invite you to explore the full findings of this study to gain the comprehensive intelligence necessary for strategic planning in 2026 and beyond. The complete report contains the specific segmentation data, detailed company profiles, and granular regional analysis needed to finalize your strategic roadmap.
For detailed analysis of this topic, please visit the official page: Saw Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Membrane Filtration Market to Hit $30.11B by 2032 Growing at 6.6% CAGR
By pmarketresearch, 2026-09-15
Navigating the Membrane Filtration Landscape: Strategic Intelligence for 2026 Decision-Making
The Imperative for Precision Intelligence in a Shifting Market
The membrane filtration industry has evolved far beyond a commoditized utility service. As we move deeper into 2026, it stands as a sophisticated nexus of technological innovation, regulatory compliance, and critical resource management. For executives, investors, and strategic planners, distinguishing between market noise and actionable intelligence is no longer a luxury; it is a fundamental requirement for survival and growth. The sector is characterized by rapid technological iterations, fluctuating raw material costs, and stringent environmental mandates that vary significantly across jurisdictions. In this environment, generalized market research is insufficient. Leaders need granular, forward-looking data that connects macroeconomic trends with micro-level operational realities.
Our latest comprehensive study on the Membrane Filtration Market is designed to bridge the gap between broad industry observation and tactical execution. This report is not merely a collection of historical figures; it is a strategic roadmap engineered to support critical decisions throughout the forecast horizon. By analyzing the trajectory from historical baselines through to the projected landscape of 2032, we provide the context necessary to anticipate shifts in demand, supply chain vulnerabilities, and competitive maneuvers before they impact the bottom line. The following overview outlines the scope, depth, and strategic utility of this intelligence, highlighting why it is essential reading for stakeholders aiming to secure a competitive advantage in the coming years.
Market Trajectory and Structural Dynamics
Historical Context and Future Growth Horizons
Understanding the market's momentum requires a clear view of its historical consolidation and future expansion vectors. The industry has demonstrated resilience and steady expansion over the past half-decade, driven by increasing global awareness of water scarcity, stricter industrial discharge norms, and the escalating demand for purity in life sciences and food processing. Our analysis tracks this evolution meticulously, establishing a robust baseline from 2020 through the base year of 2025. This historical lens allows us to validate growth models against actual performance data, filtering out speculative volatility to identify genuine structural trends.
Looking forward, the forecast period extends through 2032, offering a long-term view essential for capital-intensive planning. The market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.6% during this forecast period. This rate indicates sustained momentum, outpacing many traditional industrial sectors. To put this in perspective, the market valuation has matured significantly from its 2020 levels, reaching an estimated 19.25 billion USD in the base year of 2025. As we move through the forecast window, the valuation is expected to climb steadily, reflecting the compounding effect of technological adoption and expanding application scopes. This growth is not linear; it is influenced by regional readiness, regulatory catalysts, and the pace of innovation in membrane materials. Our report dissects these growth drivers to help stakeholders identify where the highest value creation opportunities lie within the forecast timeline.
Segmentation Nuances Across Type and Application
The membrane filtration ecosystem is diverse, comprising various technologies that serve distinct functional purposes. The market is segmented by type, primarily including Reverse Osmosis, Ultrafiltration, Microfiltration, and Nanofiltration. Each segment operates under different performance parameters and cost structures. Reverse Osmosis continues to hold a significant position, particularly in applications requiring high-purity water and desalination. However, the dynamics are shifting. Ultrafiltration and Microfiltration are witnessing renewed interest due to their versatility in industrial water treatment and biological separations. Nanofiltration occupies a specialized niche, often bridging the gap between ultrafiltration and reverse osmosis for specific contaminant removal needs.
Similarly, the application landscape is fragmented across Water & Wastewater, Food & Beverages, Industrial, and other sectors. The Water & Wastewater segment remains a cornerstone of demand, driven by municipal infrastructure upgrades and industrial effluent treatment requirements. Food & Beverages represents a high-value segment where membrane technology ensures safety and quality without thermal degradation. The Industrial sector is increasingly adopting filtration for process water reuse and resource recovery. Our report delves into the specific drivers within each application area, analyzing how sector-specific regulations and operational efficiencies influence technology selection. Rather than providing static market shares, we analyze the relative momentum of each segment to guide portfolio decisions.
Regional Deployment and Market Concentration
Geographic dynamics play a crucial role in shaping market opportunities. The global footprint of membrane filtration is uneven, with varying levels of infrastructure maturity and regulatory stringency. North America and Europe maintain established markets with high adoption rates of advanced technologies, often driven by stringent environmental regulations and aging infrastructure replacement cycles. Asia Pacific represents a high-growth region, fueled by rapid industrialization, urbanization, and increasing investments in water security. Latin America and the Middle East and Africa present emerging opportunities, often linked to specific large-scale infrastructure projects and resource management challenges.
On the supply side, the market exhibits moderate to high concentration. The combined share of the top three competitors stands at approximately 55.0%, while the top five players account for around 62.0%. This concentration suggests a competitive landscape where scale, technological proprietary rights, and global service networks are significant barriers to entry. However, it also indicates room for specialized players who can offer niche solutions or superior customization. Understanding this concentration is vital for assessing supply chain risks and negotiating leverage. Our analysis provides insights into how this competitive structure influences pricing power, innovation speed, and strategic partnerships across different regions.
Deep Dive into Competitive Landscape and Key Players
Profiles of Market Leaders and Their Strategic Focus
The competitive arena is populated by global giants and specialized innovators, each carving out strengths in specific technology domains or application verticals. Our report includes detailed profiles of key companies that define the current market structure. Merck KGaA, based in Darmstadt, Germany, is a prominent player focusing on high-purity solutions. Their Millipore® Filter Membranes and Durapore® PVDF membranes are critical for sterile filtration in biopharma, life sciences, and HPLC applications, positioning them strongly in the high-value life sciences segment.
DuPont Water Solutions, headquartered in Wilmington, Delaware, maintains a robust presence in the water treatment sector. Their offerings, such as Inge™ UF modules with integrated pre-filters and the IntegraTec™ XTP series, address challenges in drinking water, seawater, and industrial applications. DuPont's focus on integrating pre-filtration and increasing flow rates per module reflects a strategy aimed at operational efficiency and space optimization for customers. Toray Industries, Inc., from Tokyo, Japan, is another key contender. Their F-HFUG Series UF membrane modules are specifically engineered for wastewater reuse and biofouling reduction, addressing critical pain points in water recycling initiatives.
Ultrafiltration Membrane Filtration Market
Air Products and Chemicals, Inc., located in Allentown, Pennsylvania, brings a different perspective with gas separation and purification membrane systems. Their solutions for biogas, hydrogen recovery, and aerospace applications highlight the growing intersection of membrane technology with energy transition and industrial gas processing. PPG Industries, Inc., based in Pittsburgh, focuses on Ultrafiltration antifouling spiral-wound membranes, targeting industrial water purification and oily wastewater treatment. This specialization in antifouling capabilities addresses a persistent operational challenge in industrial settings. Alfa Laval AB, from Lund, Sweden, offers advanced membrane filtration solutions and plants for industrial processes and fermentation, emphasizing system integration and process optimization.
Other significant players include Pentair plc, headquartered in Shannon, Ireland, which provides commercial and industrial membrane filtration solutions for water treatment and purification. SUEZ Water Technologies & Solutions, based in Paris, France, delivers integrated water treatment systems and membrane filtration technologies for municipal and industrial use, leveraging their extensive utility network. Koch Separation Solutions, from Wichita, Kansas, specializes in custom membrane filtration modules and systems for industrial and chemical processing, catering to bespoke engineering requirements. Finally, Asahi Kasei Corporation, based in Tokyo, Japan, offers Microza® UF and MF membranes for water and industrial applications, showcasing strong material science capabilities. Our report analyzes how these companies are positioning themselves relative to one another and the gaps they are attempting to fill.
Recent Strategic Moves and Product Innovations
The landscape is dynamic, with key players constantly adjusting their positions through product launches, capacity expansions, and availability updates. In May 2026, Toray Industries, Inc. launched its F-HFUG Series ultrafiltration membrane module, specifically targeting wastewater reuse and aiming to reduce biofouling in RO processes. This move underscores the industry's focus on enhancing the longevity and efficiency of downstream processes through upstream innovation. Earlier, in April 2026, DuPont Water Solutions introduced Inge™ UF modules with an integrated pre-filter, designed for space-saving in drinking water and seawater applications. This launch demonstrates a trend toward compact, multi-functional systems that reduce installation footprints.
Capacity expansions also signal confidence and market demand. In June 2026, Air Products and Chemicals, Inc. held a ribbon-cutting for a 70 million USD expansion of their Missouri Manufacturing and Logistics Center. This investment increases production capacity for membrane solutions, particularly supporting their gas separation and purification applications. Such capital expenditure indicates strong expected demand in energy-related membrane applications. On the product availability front, DuPont made its IntegraTec™ XTP 100 IG ultrafiltration modules globally available in October 2025, offering up to 30% more flow per module. This incremental innovation highlights the continuous race to improve performance metrics. PPG Industries, Inc. also contributed to the innovation cycle in November 2025 by introducing an ultrafiltration antifouling membrane for industrial water purification capable of handling oily contaminants. These recent developments are cataloged and analyzed in our report to help clients anticipate competitor trajectories and identify potential partnership or acquisition targets.
Industry Dynamics: Raw Materials, Regulations, and Cost Structures
Raw Material Volatility and Supply Chain Implications
The economics of membrane filtration are heavily influenced by raw material costs and supply chain stability. The cost of key materials, such as PVDF resin used in water treatment membranes, fluctuates based on petrochemical trends and regional supply constraints. In 2024, the average global market price for PVDF resin for water treatment membranes was approximately 22,041 USD per ton. However, volatility can spike significantly; for instance, coatings-grade PVDF membrane resin main quoted prices reached between 65,000 and 70,000 USD per ton in November 2025. This discrepancy highlights the premium associated with specific grades and the potential for cost shocks.
Such volatility impacts manufacturing costs and, consequently, pricing strategies for membrane modules. Stakeholders need to understand how these material costs translate into end-product pricing and margin pressures. Our report examines the relationship between raw material indices and market pricing, offering insights into how companies are mitigating risks through long-term contracts, alternative material research, or value engineering. For procurement leaders and financial planners, grasping these dynamics is essential for budgeting and scenario planning over the forecast period.
Membrane Filtration Market
Regulatory Frameworks and Certification Requirements
Regulatory compliance is a non-negotiable aspect of the membrane filtration market, particularly in applications involving drinking water and public health. Standards such as NSF/ANSI/CAN 61 govern the health effects of drinking water system components. As of June 2026, listings for ultrafiltration devices under these certifications remained active, indicating ongoing compliance and market access. Furthermore, NSF International continues to list multiple PVDF ultrafiltration modules certified for Cryptosporidium removal efficiency, with a mean Log Reduction Value (LRV) of 4. This level of performance certification is critical for municipal and industrial water treatment projects where pathogen removal is paramount.
These regulations not only dictate market access but also influence technology preferences. Membrane technologies that can demonstrate verified performance against specific contaminants gain a competitive edge in regulated markets. Our analysis explores the impact of these regulatory requirements on product development and market entry strategies. For companies operating in North America, Europe, and other regulated regions, understanding the certification landscape is vital for ensuring product viability and avoiding costly compliance delays. The report details how regulatory trends are shaping the adoption of specific membrane types and materials.
Strategic Value of the Report for 2026 Decision-Making
Actionable Insights for Capital Allocation and Portfolio Strategy
In a market growing at a CAGR of 6.6% towards a projected valuation exceeding 30 billion USD by 2032, the allocation of capital must be precise. This report serves as a decision-support tool for senior management, offering the granularity needed to prioritize investments. Whether evaluating entry into a new geographic market, expanding production capacity for specific membrane types, or diversifying into adjacent application sectors, the data provided helps quantify potential returns and risks. The analysis of market concentration and competitor profiles allows strategists to identify white spaces where competition is less intense or where customer needs are underserved.
For investors, the report clarifies the growth trajectories of different segments, helping to identify which technologies and applications are likely to yield the highest value creation. The distinction between mature segments and high-growth niches is critical for portfolio construction. The insights into raw material dynamics and regulatory environments further de-risk investment theses by highlighting potential headwinds and tailwinds. By synthesizing market size, growth rates, and competitive intelligence, the report enables a holistic view of the investment landscape.
Operational Planning and Risk Mitigation
Beyond strategic planning, the report supports operational decision-making. Understanding the specific offerings of key competitors, such as DuPont's focus on integrated pre-filters or Toray's emphasis on biofouling reduction, helps procurement and engineering teams benchmark their own specifications and negotiate better terms. Awareness of recent capacity expansions, like those by Air Products, signals potential supply chain shifts that may affect lead times or material availability. The analysis of regulatory certifications ensures that operational plans align with compliance requirements, reducing the risk of project delays.
Furthermore, the report's coverage of regional dynamics assists in tailoring go-to-market strategies. What works in a mature North American market may not translate directly to the emerging opportunities in Asia Pacific or Latin America. By understanding the distinct drivers in each region, companies can localize their value propositions and sales approaches. The detailed segmentation analysis, while maintaining confidentiality on specific splits within the report, guides users on where to focus their commercial efforts for maximum impact.
Conclusion: Empowering Leadership with Comprehensive Intelligence
The membrane filtration market is at a pivotal juncture, driven by technological advancement, environmental necessity, and industrial demand. Navigating this complex landscape requires more than superficial market data; it demands deep, structured intelligence that connects the dots between historical performance, current dynamics, and future potential. Our Membrane Filtration Market research report is designed to provide this depth. By covering market size evolution, segmentation trends, competitive profiles, recent developments, and critical industry dynamics such as raw material costs and regulations, the report equips stakeholders with the knowledge needed to make informed decisions in 2026 and beyond.
We invite you to explore the full scope of this analysis. The complete report contains detailed quantitative data, specific segmentation splits, regional breakdowns, and granular competitor assessments that are essential for precise planning. Accessing the full intelligence will enable your organization to move from general awareness to targeted action, ensuring that your strategies are aligned with the most robust market evidence available. For leaders committed to excellence and growth in the membrane filtration sector, this report is an indispensable resource.
For detailed analysis of this topic, please visit the official page: Membrane Filtration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Banking Market Hits $1.92B in 2025, Forecast to Reach $3.71B by 2032 at 8.5% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Digital Banking Market (2026–2032)
The digital banking landscape is undergoing a structural transformation, moving beyond simple digitization to become the central nervous system of modern financial institutions. For executive teams and investors, the margin for error is narrowing. Understanding where capital should be deployed, which technologies will define competitive advantage, and how regulatory shifts will reshape operational models is no longer optional—it is imperative. PW Consulting's latest market research report, Digital Banking Market, offers a comprehensive roadmap for navigating this complex environment through 2032.
This analysis serves as an introduction to the depth of intelligence contained within the full report. While we highlight key macro trends and strategic imperatives here, the specific quantitative data, granular segmentation breakdowns, and proprietary risk assessments are reserved for our clients to ensure actionable confidentiality and maximum strategic value.
Market Trajectory and Scale
The momentum behind digital banking is robust, driven by a fundamental shift in consumer behavior and institutional necessity. Over the past half-decade, the market has demonstrated consistent growth, evolving from a nascent ecosystem into a dominant financial infrastructure. Historical data from 2020 through 2025 shows a clear upward trajectory in revenue generation across the sector.
Looking forward, the forecast period from 2026 to 2032 indicates sustained expansion. The market is projected to climb significantly in valuation, underpinned by a compound annual growth rate that signals healthy, long-term viability rather than ephemeral hype. This growth is not merely top-line; it reflects deepening penetration across diverse banking services and regions. For stakeholders, this macro view confirms that digital banking is a core growth engine, not a supplementary feature. However, realizing value within this expanding market requires navigating distinct competitive and regulatory currents that our full report dissects in detail.
Regulatory Dynamics and Compliance Imperatives
One of the most critical drivers shaping the 2026 decision-making landscape is the evolving regulatory environment. Compliance is transitioning from a back-office cost center to a strategic differentiator. In the United States, recent executive actions and agency rules are reshaping underwriting standards and data usage. For instance, directives from the White House in mid-2026 have asked federal financial regulators to clarify credit risk factors, including specific considerations for wage loss among non-work authorized borrowers within underwriting processes for digital banking services.
Simultaneously, the implementation of the CFPB Section 1033 rule, which began in 2025, mandates consumer financial data portability. This regulation is accelerating the adoption of API-first architectures, forcing platforms to be interoperable and transparent. Across the Atlantic, the EU's PSD3 legislation, effective in 2026, expands open banking requirements to encompass investment accounts, insurance products, and pension data. These regulatory layers create a complex compliance matrix. Our report analyzes how these specific legislative changes impact technology stacks and risk models, providing a clear view of where compliance investment yields competitive leverage versus where it represents pure cost. Furthermore, recent revisions to the CFPB proposed Section 1071 small-business lending reporting rule, which exempts community banks originating fewer than 1,000 covered loans per year, highlight the nuanced impact of regulation across different institution sizes.
Technology and Product Evolution
The product landscape is diversifying as institutions seek to balance legacy stability with modern agility. The market is segmented across various technological delivery models and product types, each serving different strategic needs. Cloud-based deployments continue to gain favor for their scalability and reduced infrastructure overhead, while on-premises and hybrid models retain relevance for institutions with specific latency or sovereignty requirements.
In terms of product offerings, mobile banking applications remain a primary touchpoint for consumers, but the value is shifting toward integrated platforms. Online banking platforms provide the robust backbone for complex transactions, while API banking services are becoming the glue that connects disparate financial ecosystems. Additionally, AI and automation tools are emerging as critical differentiators, enabling institutions to move from reactive service to predictive engagement. The full report details the revenue distribution and growth potential across these categories without exposing sensitive competitive benchmarks to the public domain.
Competitive Landscape and Strategic Moves
The market is characterized by high concentration, with a few key players commanding a significant share of the revenue. This consolidation creates barriers to entry but also pressures incumbents to innovate rapidly to maintain market share. Our analysis profiles leading companies that are defining the standards of the industry.
Companies like CSI, headquartered in Paducah, Kentucky, provide core banking platforms like NuPoint and digital banking solutions such as Apiture to modernize operations for US financial institutions. Their recent movements illustrate the consolidation trend; in late 2025, CSI completed the acquisition of Apiture to integrate its digital banking platform, enhancing tools for banks and credit unions. Following this, Apiture launched an AI-powered user interface in November 2025 aimed at predictive and personalized experiences. By early 2026, institutions like Wayne County Bank selected the Apiture Digital Banking platform to power their growth phase, and CSI subsequently introduced a Customer Intelligence Suite in May 2026 featuring AI-powered insights for retail and business banking.
On the technology frontier, London-based Thought Machine develops next-generation cloud-native core banking technology with Vault Core and Vault Payments, focusing on deep digital transformation. Similarly, nCino, based in San Mateo, California, delivers cloud-based digital banking platforms with extensive integrations for CRM and core systems. Lumin Digital, from San Ramon, California, offers a cloud-native Compounding Growth Platform focused on AI-powered solutions for banks and credit unions, recently launching a suite of AI-enabled tools in December 2025 to enhance performance and experience. Meanwhile, SDK.finance provides fintech infrastructure with international deployment capabilities across the US, Europe, MENA, and Africa. Understanding the strategic positioning of these players is essential for partnership evaluation and competitive benchmarking.
Strategic Recommendations for 2026 Decision Makers
Based on the trajectory of the market and the dynamics outlined above, several strategic priorities emerge for leadership teams in 2026. First, the integration of AI must move beyond pilot programs to core operational functionality, particularly in customer intelligence and risk underwriting. Second, API architecture must be treated as a strategic asset, especially in light of data portability rules like CFPB Section 1033 and EU PSD3. Institutions that build flexible, compliant API layers will be better positioned to adapt to future regulatory changes and partner ecosystems.
Third, regional considerations remain vital. While global growth is strong, the distribution of market value varies significantly across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Our report provides a nuanced view of these regional dynamics without disclosing the precise value splits that constitute our proprietary analysis. Executives must tailor their expansion and investment strategies to the specific maturity and regulatory environment of each geography. Finally, the high concentration of the market suggests that partnership or acquisition may be a faster route to capability building than organic development for many institutions.
Digital Banking Market
Digital Insurance Market
Conclusion
The Digital Banking Market is at a pivotal juncture where technology, regulation, and consumer expectation converge. The growth projections through 2032 indicate a massive opportunity, but capturing it requires more than general market awareness. It demands precise intelligence on segmentation, competitive moves, and regulatory impacts. This overview provides the strategic context, but the full PW Consulting report delivers the actionable data and deep-dive analysis required to make informed investment and operational decisions. For those ready to secure a competitive edge in the evolving financial landscape, accessing the complete intelligence suite is the logical next step.
For detailed analysis of this topic, please visit the official page: Digital Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Lamination Films Market to Hit US$4,104 Million by 2032 at 8.8% CAGR
By pmarketresearch, 2026-09-15
Strategic Outlook: Unlocking Growth in the Thermal Lamination Films Market Through 2032
In an era where packaging functionality and visual appeal directly influence consumer behavior, thermal lamination films have evolved from simple protective overlays to critical enablers of brand differentiation and product durability. PW Consulting's latest comprehensive market research, Thermal Lamination Films Market, provides decision-makers with the analytical rigor required to navigate a sector undergoing rapid technical and regulatory transformation. This executive overview outlines the strategic architecture of the study, demonstrates its immediate relevance to 2026 corporate planning, and highlights the structural forces reshaping competitive dynamics across global value chains.
Market Architecture and Macro Trajectory
The global thermal lamination films market has demonstrated consistent expansion across a robust historical track record and is positioned for sustained mid-term acceleration. Between 2020 and 2025, industry revenues progressed from 1,562.0 million USD to an estimated 2,269.0 million USD, reflecting a compound trajectory that underscores both baseline demand resilience and incremental volume uptake across downstream sectors. The forecast horizon extends through 2032, during which the market is projected to surpass 4,104.0 million USD, supported by a forecast-period CAGR of 8.8 percent.
This growth pattern is not merely a function of macro packaging expansion. It reflects an ongoing redefinition of lamination value propositions. Where traditional thermal films once served primarily as mechanical shields, contemporary formulations increasingly deliver optical clarity, tactile differentiation, chemical resistance, and, critically, compatibility with evolving sustainability mandates. The report's top-line modeling isolates these inflection points, allowing leadership teams to distinguish between cyclical volume fluctuations and structural addressable-market expansion when calibrating capacity, procurement, and geographic allocation strategies for 2026.
Core Segmentation Framework and Applied Intelligence
Strategic clarity requires more than aggregate growth figures. The study deconstructs the market across three foundational dimensions, each mapped to operational decision contexts rather than abstract taxonomy.
- Material architecture: Thermal lamination solutions are predominantly anchored in BOPP, BOPET, and BOPA chemistries, supplemented by specialized alternatives. The analysis examines how resin cost dynamics, melt-adhesive performance thresholds, and end-use durability requirements drive material selection across packaging, labeling, and graphic applications.
- Application environments: Industrial printing, commercial printing, and adjacent use cases are evaluated through the lens of throughput requirements, finishing economics, and protection specifications. This framework helps manufacturers align film grades with customer workflows rather than competing solely on price per square meter.
- Geographic deployment: Regional consumption profiles are assessed in relation to packaging intensification, printing infrastructure maturity, and regulatory exposure. The report avoids static share tables in favor of scenario-informed regional prioritization that reflects logistics realities, import dependency, and local certification regimes.
By integrating these segmentation layers, the study equips readers to identify where margin protection, product line extension, or channel repositioning will generate the highest incremental value in the coming planning cycle.
Competitive Landscape and Strategic Positioning
The thermal lamination films ecosystem is characterized by a heterogeneous participant base, ranging from globally integrated film producers to regionally focused converters. Market concentration metrics indicate that the top three players collectively account for 29.5 percent of recorded revenue, while the top five reach 41.2 percent, signaling a landscape that is neither fully consolidated nor purely fragmented. This structure creates both partnership opportunities and competitive pressure points for mid-sized and emerging suppliers.
The report profiles a broad spectrum of incumbent and challenger organizations, including COSMO Films (GBC), Transilwrap Company LLC, D&K Group, FlexFilm, Derprosa by Taghleef Industries, GMP, Royal Sovereign, Ipak, Drytac, PKC Co., Ltd., J-Film Corporation, Shagun Films, Kangde Xin, New Era, Hongqing, KANGLONG, Dingxin, EKO Film, Eluson Film, JPFL Films (BC Jindal), Polyplex, Mitsubishi Chemical America, Inc., Transcendia Inc., Guangdong EKO Film Manufacture Co. Ltd, Taghleef Industries, Fujian Taian Lamination Film Co. Ltd., Flexcon Company Inc., and Ultralen Film GmbH. Rather than presenting static corporate summaries, the analysis evaluates each participant's strategic posture across several actionable dimensions.
- Product differentiation: How firms are leveraging soft-touch, anti-scratch, anti-fingerprint, floatable, and thinner-gauge constructions to command price premiums or secure long-term converters' contracts.
- Geographic and application footprints: Where companies are concentrating investment versus where they are exposed to commoditization risk.
- Certification and compliance readiness: The extent to which ISO 9001:2015 and BRCGS credentials shape supplier eligibility in food, beverage, and liquid packaging channels.
- Innovation cadence: The pace at which new grades, adhesive technologies, and substrate compatibilities are reaching commercial deployment.
For 2026 planners, this competitive mapping translates into concrete strategic questions: which capability gaps are inviting displacement, which customer segments are overserved, and where can targeted R&D or acquisition create defensible positioning before market maturity compresses differentiation returns.
Worldwide Thermal Film Market
Recent Industry Movements Shaping 2026 Playbooks
The study embeds current corporate activity within broader sector momentum, ensuring that forward-looking strategy rests on observed execution rather than speculative trend-reading. Recent developments underscore how quickly premium protection and recyclability objectives are converging in product roadmaps.
Thermal Lamination Films Market
Taghleef Industries, for example, advanced its sustainability-driven portfolio with the May 2025 launch of SHAPE360 TDSW, a high-performance floatable white polyolefin TD shrink sleeve label film engineered for bottle-to-bottle recycling and reduced material thickness. In parallel, Derprosa by Taghleef Industries introduced Derprosa DL Soft Touch Pro-Shield 4x4, a soft-touch film with enhanced anti-scratch and anti-fingerprint protection, illustrating the premium tactile segment's continued refinement. By October 2025, Derprosa further reinforced its market visibility through a targeted exhibition presence at Printing United Orlando, showcasing a suite of premium soft-touch, anti-fingerprint, and anti-scratch thermal lamination films to converters and brand stakeholders.
These moves matter because they demonstrate a dual strategic emphasis: protecting visual and tactile quality while aligning with recycle-friendly design expectations. For buyers, this creates a more nuanced sourcing environment where film selection must balance performance specifications, compliance readiness, and downstream sustainability narratives. The report synthesizes such developments into actionable implications for procurement timing, specification standardization, and supplier evaluation criteria.
Structural Dynamics, Regulation, and Cost Architecture
No 2026 strategy can rely solely on demand forecasts. The thermal lamination films market is being continuously reshaped by regulatory frameworks, certification requirements, and raw material volatility that directly affect cost structures and market access.
Extended Producer Responsibility schemes across multiple regions are requiring manufacturers to take greater accountability for end-of-life packaging management. This regulatory pressure is indirectly accelerating demand for durable protective thermal lamination films that extend product life, reduce damage-related waste, and support more responsible packaging architectures. At the same time, ISO 9001:2015 and BRCGS certifications are increasingly mandated for suppliers whose films enter food and liquid packaging applications, raising the compliance floor for market participation and favoring suppliers with robust quality systems.
On the input side, thermal lamination films are primarily manufactured from BOPP and PET resins combined with thermal adhesives designed to melt at low temperatures, enabling efficient application across high-speed converting lines. However, production economics remain sensitive to fluctuations in polypropylene, polyethylene, and PET resin prices driven by oil and gas market volatility. These input swings can compress margins for price-takers while creating opportunities for suppliers with forward contracting, formulation flexibility, or differentiated performance that justifies cost pass-through. The study integrates these dynamics into scenario-based cost and margin analysis, helping leaders stress-test pricing strategies and inventory decisions against plausible resin-price environments.
What the Report Delivers for 2026 Decision-Making
PW Consulting designed this market research to function as a working strategic asset rather than a retrospective summary. The full study provides depth and granularity that enable cross-functional teams to align around shared assumptions and measurable priorities.
- Demand and revenue modeling: Forecast trajectories through 2032 anchored to historical performance, supporting capacity planning, sales targeting, and investment justification.
- Differentiation and application mapping: Clear linkage between film types, end-use requirements, and customer value arguments that guide product positioning and marketing messaging.
- Competitive benchmarking: Structured evaluation of participant strengths, geographic exposure, and innovation direction to inform competitive response and partnership selection.
- Regulatory and cost context: Practical assessment of how EPR expectations, certification mandates, and resin-price variability influence sourcing, compliance roadmaps, and margin management.
- Scenario-ready interpretation: Analytical frameworks that help teams translate macro trends into regional, segment, and product-line decisions without relying on a single deterministic outlook.
Taken together, these components allow executives to answer the practical questions that determine 2026 outcomes: where to prioritize innovation spend, which customer segments warrant dedicated service models, how to structure supplier negotiations amid input volatility, and where consolidation or niche positioning offers the most attractive risk-adjusted returns.
Turning Intelligence into Execution
Thermal lamination films are no longer a peripheral packaging input; they are a strategically relevant layer where protection, aesthetics, compliance, and sustainability intersect. With the market advancing from an estimated 2,392.86 million USD in 2026 toward a projected 4,104.0 million USD by 2032, the window for deliberate positioning is narrowing. Companies that treat this period as a pure volume play risk being squeezed by resin volatility, certification barriers, and intensifying competition from firms that have already aligned product roadmaps with recyclability and premium protection expectations.
PW Consulting's Thermal Lamination Films Market research is built for leaders who need more than directional optimism. It provides the structural evidence, competitive intelligence, and applied scenario tools required to convert sector momentum into disciplined execution. For organizations preparing 2026 investment, sourcing, and growth decisions, the complete study offers the detailed segmentation analysis, company-level assessment, and forward-looking interpretation necessary to act with confidence. We invite decision-makers to access the full report and integrate its findings directly into strategic planning, product roadmap prioritization, and competitive positioning workflows.
For detailed analysis of this topic, please visit the official page: Thermal Lamination Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com