

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Membrane Filtration Market to Hit $30.11B by 2032 Growing at 6.6% CAGR

Navigating the Membrane Filtration Landscape: Strategic Intelligence for 2026 Decision-Making
The Imperative for Precision Intelligence in a Shifting Market
The membrane filtration industry has evolved far beyond a commoditized utility service. As we move deeper into 2026, it stands as a sophisticated nexus of technological innovation, regulatory compliance, and critical resource management. For executives, investors, and strategic planners, distinguishing between market noise and actionable intelligence is no longer a luxury; it is a fundamental requirement for survival and growth. The sector is characterized by rapid technological iterations, fluctuating raw material costs, and stringent environmental mandates that vary significantly across jurisdictions. In this environment, generalized market research is insufficient. Leaders need granular, forward-looking data that connects macroeconomic trends with micro-level operational realities.
Our latest comprehensive study on the Membrane Filtration Market is designed to bridge the gap between broad industry observation and tactical execution. This report is not merely a collection of historical figures; it is a strategic roadmap engineered to support critical decisions throughout the forecast horizon. By analyzing the trajectory from historical baselines through to the projected landscape of 2032, we provide the context necessary to anticipate shifts in demand, supply chain vulnerabilities, and competitive maneuvers before they impact the bottom line. The following overview outlines the scope, depth, and strategic utility of this intelligence, highlighting why it is essential reading for stakeholders aiming to secure a competitive advantage in the coming years.
Market Trajectory and Structural Dynamics
Historical Context and Future Growth Horizons
Understanding the market's momentum requires a clear view of its historical consolidation and future expansion vectors. The industry has demonstrated resilience and steady expansion over the past half-decade, driven by increasing global awareness of water scarcity, stricter industrial discharge norms, and the escalating demand for purity in life sciences and food processing. Our analysis tracks this evolution meticulously, establishing a robust baseline from 2020 through the base year of 2025. This historical lens allows us to validate growth models against actual performance data, filtering out speculative volatility to identify genuine structural trends.
Looking forward, the forecast period extends through 2032, offering a long-term view essential for capital-intensive planning. The market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.6% during this forecast period. This rate indicates sustained momentum, outpacing many traditional industrial sectors. To put this in perspective, the market valuation has matured significantly from its 2020 levels, reaching an estimated 19.25 billion USD in the base year of 2025. As we move through the forecast window, the valuation is expected to climb steadily, reflecting the compounding effect of technological adoption and expanding application scopes. This growth is not linear; it is influenced by regional readiness, regulatory catalysts, and the pace of innovation in membrane materials. Our report dissects these growth drivers to help stakeholders identify where the highest value creation opportunities lie within the forecast timeline.
Segmentation Nuances Across Type and Application
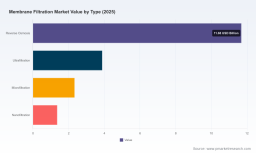
The membrane filtration ecosystem is diverse, comprising various technologies that serve distinct functional purposes. The market is segmented by type, primarily including Reverse Osmosis, Ultrafiltration, Microfiltration, and Nanofiltration. Each segment operates under different performance parameters and cost structures. Reverse Osmosis continues to hold a significant position, particularly in applications requiring high-purity water and desalination. However, the dynamics are shifting. Ultrafiltration and Microfiltration are witnessing renewed interest due to their versatility in industrial water treatment and biological separations. Nanofiltration occupies a specialized niche, often bridging the gap between ultrafiltration and reverse osmosis for specific contaminant removal needs.
Similarly, the application landscape is fragmented across Water & Wastewater, Food & Beverages, Industrial, and other sectors. The Water & Wastewater segment remains a cornerstone of demand, driven by municipal infrastructure upgrades and industrial effluent treatment requirements. Food & Beverages represents a high-value segment where membrane technology ensures safety and quality without thermal degradation. The Industrial sector is increasingly adopting filtration for process water reuse and resource recovery. Our report delves into the specific drivers within each application area, analyzing how sector-specific regulations and operational efficiencies influence technology selection. Rather than providing static market shares, we analyze the relative momentum of each segment to guide portfolio decisions.
Regional Deployment and Market Concentration
Geographic dynamics play a crucial role in shaping market opportunities. The global footprint of membrane filtration is uneven, with varying levels of infrastructure maturity and regulatory stringency. North America and Europe maintain established markets with high adoption rates of advanced technologies, often driven by stringent environmental regulations and aging infrastructure replacement cycles. Asia Pacific represents a high-growth region, fueled by rapid industrialization, urbanization, and increasing investments in water security. Latin America and the Middle East and Africa present emerging opportunities, often linked to specific large-scale infrastructure projects and resource management challenges.
On the supply side, the market exhibits moderate to high concentration. The combined share of the top three competitors stands at approximately 55.0%, while the top five players account for around 62.0%. This concentration suggests a competitive landscape where scale, technological proprietary rights, and global service networks are significant barriers to entry. However, it also indicates room for specialized players who can offer niche solutions or superior customization. Understanding this concentration is vital for assessing supply chain risks and negotiating leverage. Our analysis provides insights into how this competitive structure influences pricing power, innovation speed, and strategic partnerships across different regions.
Deep Dive into Competitive Landscape and Key Players
Profiles of Market Leaders and Their Strategic Focus
The competitive arena is populated by global giants and specialized innovators, each carving out strengths in specific technology domains or application verticals. Our report includes detailed profiles of key companies that define the current market structure. Merck KGaA, based in Darmstadt, Germany, is a prominent player focusing on high-purity solutions. Their Millipore® Filter Membranes and Durapore® PVDF membranes are critical for sterile filtration in biopharma, life sciences, and HPLC applications, positioning them strongly in the high-value life sciences segment.
DuPont Water Solutions, headquartered in Wilmington, Delaware, maintains a robust presence in the water treatment sector. Their offerings, such as Inge™ UF modules with integrated pre-filters and the IntegraTec™ XTP series, address challenges in drinking water, seawater, and industrial applications. DuPont's focus on integrating pre-filtration and increasing flow rates per module reflects a strategy aimed at operational efficiency and space optimization for customers. Toray Industries, Inc., from Tokyo, Japan, is another key contender. Their F-HFUG Series UF membrane modules are specifically engineered for wastewater reuse and biofouling reduction, addressing critical pain points in water recycling initiatives.
Ultrafiltration Membrane Filtration Market
Air Products and Chemicals, Inc., located in Allentown, Pennsylvania, brings a different perspective with gas separation and purification membrane systems. Their solutions for biogas, hydrogen recovery, and aerospace applications highlight the growing intersection of membrane technology with energy transition and industrial gas processing. PPG Industries, Inc., based in Pittsburgh, focuses on Ultrafiltration antifouling spiral-wound membranes, targeting industrial water purification and oily wastewater treatment. This specialization in antifouling capabilities addresses a persistent operational challenge in industrial settings. Alfa Laval AB, from Lund, Sweden, offers advanced membrane filtration solutions and plants for industrial processes and fermentation, emphasizing system integration and process optimization.
Other significant players include Pentair plc, headquartered in Shannon, Ireland, which provides commercial and industrial membrane filtration solutions for water treatment and purification. SUEZ Water Technologies & Solutions, based in Paris, France, delivers integrated water treatment systems and membrane filtration technologies for municipal and industrial use, leveraging their extensive utility network. Koch Separation Solutions, from Wichita, Kansas, specializes in custom membrane filtration modules and systems for industrial and chemical processing, catering to bespoke engineering requirements. Finally, Asahi Kasei Corporation, based in Tokyo, Japan, offers Microza® UF and MF membranes for water and industrial applications, showcasing strong material science capabilities. Our report analyzes how these companies are positioning themselves relative to one another and the gaps they are attempting to fill.
Recent Strategic Moves and Product Innovations
The landscape is dynamic, with key players constantly adjusting their positions through product launches, capacity expansions, and availability updates. In May 2026, Toray Industries, Inc. launched its F-HFUG Series ultrafiltration membrane module, specifically targeting wastewater reuse and aiming to reduce biofouling in RO processes. This move underscores the industry's focus on enhancing the longevity and efficiency of downstream processes through upstream innovation. Earlier, in April 2026, DuPont Water Solutions introduced Inge™ UF modules with an integrated pre-filter, designed for space-saving in drinking water and seawater applications. This launch demonstrates a trend toward compact, multi-functional systems that reduce installation footprints.
Capacity expansions also signal confidence and market demand. In June 2026, Air Products and Chemicals, Inc. held a ribbon-cutting for a 70 million USD expansion of their Missouri Manufacturing and Logistics Center. This investment increases production capacity for membrane solutions, particularly supporting their gas separation and purification applications. Such capital expenditure indicates strong expected demand in energy-related membrane applications. On the product availability front, DuPont made its IntegraTec™ XTP 100 IG ultrafiltration modules globally available in October 2025, offering up to 30% more flow per module. This incremental innovation highlights the continuous race to improve performance metrics. PPG Industries, Inc. also contributed to the innovation cycle in November 2025 by introducing an ultrafiltration antifouling membrane for industrial water purification capable of handling oily contaminants. These recent developments are cataloged and analyzed in our report to help clients anticipate competitor trajectories and identify potential partnership or acquisition targets.
Industry Dynamics: Raw Materials, Regulations, and Cost Structures
Raw Material Volatility and Supply Chain Implications
The economics of membrane filtration are heavily influenced by raw material costs and supply chain stability. The cost of key materials, such as PVDF resin used in water treatment membranes, fluctuates based on petrochemical trends and regional supply constraints. In 2024, the average global market price for PVDF resin for water treatment membranes was approximately 22,041 USD per ton. However, volatility can spike significantly; for instance, coatings-grade PVDF membrane resin main quoted prices reached between 65,000 and 70,000 USD per ton in November 2025. This discrepancy highlights the premium associated with specific grades and the potential for cost shocks.
Such volatility impacts manufacturing costs and, consequently, pricing strategies for membrane modules. Stakeholders need to understand how these material costs translate into end-product pricing and margin pressures. Our report examines the relationship between raw material indices and market pricing, offering insights into how companies are mitigating risks through long-term contracts, alternative material research, or value engineering. For procurement leaders and financial planners, grasping these dynamics is essential for budgeting and scenario planning over the forecast period.
Membrane Filtration Market
Regulatory Frameworks and Certification Requirements
Regulatory compliance is a non-negotiable aspect of the membrane filtration market, particularly in applications involving drinking water and public health. Standards such as NSF/ANSI/CAN 61 govern the health effects of drinking water system components. As of June 2026, listings for ultrafiltration devices under these certifications remained active, indicating ongoing compliance and market access. Furthermore, NSF International continues to list multiple PVDF ultrafiltration modules certified for Cryptosporidium removal efficiency, with a mean Log Reduction Value (LRV) of 4. This level of performance certification is critical for municipal and industrial water treatment projects where pathogen removal is paramount.
These regulations not only dictate market access but also influence technology preferences. Membrane technologies that can demonstrate verified performance against specific contaminants gain a competitive edge in regulated markets. Our analysis explores the impact of these regulatory requirements on product development and market entry strategies. For companies operating in North America, Europe, and other regulated regions, understanding the certification landscape is vital for ensuring product viability and avoiding costly compliance delays. The report details how regulatory trends are shaping the adoption of specific membrane types and materials.
Strategic Value of the Report for 2026 Decision-Making
Actionable Insights for Capital Allocation and Portfolio Strategy
In a market growing at a CAGR of 6.6% towards a projected valuation exceeding 30 billion USD by 2032, the allocation of capital must be precise. This report serves as a decision-support tool for senior management, offering the granularity needed to prioritize investments. Whether evaluating entry into a new geographic market, expanding production capacity for specific membrane types, or diversifying into adjacent application sectors, the data provided helps quantify potential returns and risks. The analysis of market concentration and competitor profiles allows strategists to identify white spaces where competition is less intense or where customer needs are underserved.
For investors, the report clarifies the growth trajectories of different segments, helping to identify which technologies and applications are likely to yield the highest value creation. The distinction between mature segments and high-growth niches is critical for portfolio construction. The insights into raw material dynamics and regulatory environments further de-risk investment theses by highlighting potential headwinds and tailwinds. By synthesizing market size, growth rates, and competitive intelligence, the report enables a holistic view of the investment landscape.
Operational Planning and Risk Mitigation
Beyond strategic planning, the report supports operational decision-making. Understanding the specific offerings of key competitors, such as DuPont's focus on integrated pre-filters or Toray's emphasis on biofouling reduction, helps procurement and engineering teams benchmark their own specifications and negotiate better terms. Awareness of recent capacity expansions, like those by Air Products, signals potential supply chain shifts that may affect lead times or material availability. The analysis of regulatory certifications ensures that operational plans align with compliance requirements, reducing the risk of project delays.
Furthermore, the report's coverage of regional dynamics assists in tailoring go-to-market strategies. What works in a mature North American market may not translate directly to the emerging opportunities in Asia Pacific or Latin America. By understanding the distinct drivers in each region, companies can localize their value propositions and sales approaches. The detailed segmentation analysis, while maintaining confidentiality on specific splits within the report, guides users on where to focus their commercial efforts for maximum impact.
Conclusion: Empowering Leadership with Comprehensive Intelligence
The membrane filtration market is at a pivotal juncture, driven by technological advancement, environmental necessity, and industrial demand. Navigating this complex landscape requires more than superficial market data; it demands deep, structured intelligence that connects the dots between historical performance, current dynamics, and future potential. Our Membrane Filtration Market research report is designed to provide this depth. By covering market size evolution, segmentation trends, competitive profiles, recent developments, and critical industry dynamics such as raw material costs and regulations, the report equips stakeholders with the knowledge needed to make informed decisions in 2026 and beyond.
We invite you to explore the full scope of this analysis. The complete report contains detailed quantitative data, specific segmentation splits, regional breakdowns, and granular competitor assessments that are essential for precise planning. Accessing the full intelligence will enable your organization to move from general awareness to targeted action, ensuring that your strategies are aligned with the most robust market evidence available. For leaders committed to excellence and growth in the membrane filtration sector, this report is an indispensable resource.
For detailed analysis of this topic, please visit the official page: Membrane Filtration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com