

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cable Assembly Market Hits $167B in 2025, Projects 6.12% CAGR Through 2032

Navigating the Cable Assembly Market: Strategic Intelligence for 2026 and Beyond
The global cable assembly industry stands at a critical inflection point. As connectivity demands intensify across automotive, industrial automation, and data communication sectors, manufacturers and investors require more than surface-level projections to navigate the coming growth cycle. Our latest Cable Assembly Market research delivers a structured, decision-ready intelligence framework designed specifically for enterprise strategy teams operating in 2026 and planning through 2032.
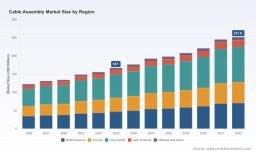
Built on a rigorous historical reconstruction spanning 2020 through 2025, the analysis establishes a verified baseline before extending forward-looking projections through the end of the decade. The market has demonstrated consistent momentum, with revenue climbing from 122.3 billion USD in 2020 to 167.0 billion USD by 2025. This trajectory reflects sustained adoption of advanced interconnect solutions, increasingly complex electronic architectures, and the ongoing migration toward higher-speed, higher-reliability transmission formats. Looking ahead, the forecast period projects a compound annual growth rate of 6.12 percent, positioning the industry to reach approximately 251.8 billion USD by 2032.
Numbers alone, however, do not capture the strategic texture of this market. What matters for leadership teams is how growth fragments across cable types, application verticals, and geographic corridors, how competitive dynamics shape pricing and capacity, and how regulatory, material, and supply-chain variables alter operational planning. This research was engineered to answer those exact questions.
The Architecture of the Report: Operational Depth Over Generic Forecasting
Many market reports stop at headline valuations and regional summaries. Our methodology deliberately goes further. The study maps the structural drivers that will determine which participants capture margin, which segments face oversupply, and where cross-functional strategy teams must allocate capital and engineering resources in the next planning cycle.
Inside the full report, readers will find:
- A granular breakdown by cable assembly type, examining how coaxial, twisted pair, fiber optic, and flat ribbon architectures are positioned across different performance thresholds, volume profiles, and design constraints.
- Application-level analysis covering automotive, data communication, industrial automation, and medical devices, with attention to the distinct qualification requirements, lifecycle expectations, and procurement patterns that define each vertical.
- Geographic demand mapping that isolates growth corridors, export-oriented production advantages, and regional compliance environments, including areas where tariff-free manufacturing and localized sourcing strategies are reshaping cost structures.
- Competitive benchmarking that evaluates how major players differentiate through product portfolios, manufacturing footprints, custom engineering capabilities, and strategic expansions into high-density semiconductor and electronics interconnects.
- Material and supply-chain context, incorporating recent observations on copper and optical fiber pricing trends, ongoing supply constraints, and the implications for contract manufacturers and electronics OEMs.
- Regulatory and standards coverage, including hazardous-environment certification frameworks, defense-sector procurement dynamics, and export-control compliance considerations that influence production planning and market access.
Each section is structured to support concrete action rather than abstract observation. Procurement leaders can use the segmentation analysis to stress-test sourcing strategies. Strategy and corporate development teams can leverage the competitive landscape mapping to identify partnership, acquisition, or geographic expansion targets. R&D and engineering management can align product roadmaps with the performance trajectories and application requirements most likely to drive volume in their respective segments.
Competitive Landscape: Differentiation, Capacity, and Recent Strategic Moves
The cable assembly market is characterized by a fragmented but increasingly sophisticated competitive field. Concentration metrics indicate that the top three players hold roughly 28.5 percent of revenue, while the top five approach 35.2 percent. This structure suggests a market where scale matters, but where specialized capabilities, custom engineering competence, and regional manufacturing agility often determine win rates in high-mix or high-reliability contract work.
Several established interconnect leaders continue to anchor the market through broad portfolios and deep application expertise. Amphenol Corporation operates across electronics, semiconductor, data communications, and high-speed applications through its communications solutions division, offering both custom and standard interconnect cable assemblies. Molex, LLC extends its positioning with custom cable assemblies, wire harnesses, and integrated interconnect solutions designed for electronics and semiconductor connectivity. TE Connectivity designs and manufactures cable assemblies and sensor interconnects tailored to electronics, semiconductor, automotive, and industrial applications, reinforcing its relevance in sectors where signal integrity and environmental durability are paramount. ICA Holdings specializes in specialty wire harnesses, cable assemblies, and electromechanical assemblies for high-mix electronics and semiconductor needs, while Meridian Cable Assemblies, LLC focuses on custom designs and manufacturing for medical, military, industrial, and electronics industries, where qualification rigor and traceability are central to customer selection.
In parallel, a strong cohort of contract manufacturers and custom assembly specialists has expanded its footprint, particularly where PCB integration, low-cost assembly, and multi-sector service capabilities create differentiated value. OurPCB provides custom cable assembly services with PCB integration spanning automotive, EV, robotics, medical, industrial, and semiconductor-related electronics. Cloom Tech specializes in custom wire harnesses and cable assemblies for automotive, aerospace, defense, robotics, and electronics sectors, and has recently strengthened its custom manufacturing capabilities for contract production serving those OEMs. SAISONIC manufactures custom cable assemblies and wire harnesses for computers, instruments, medical, machines, and electrical appliances. Romtronic produces custom cable assemblies and wire harnesses for medical, industrial automation, and automotive applications. JINNFENG Electronic Technology Co., Ltd. focuses on wire harnesses, cable assemblies, and connectors for export markets including electronics and semiconductor applications. SINNHONG Electronics Co., Limited delivers custom wire harnesses and cable assemblies with China-Vietnam manufacturing for industrial automation, consumer electronics, automotive, and communications. Wiringo manufactures custom wiring harnesses and cable assemblies for electronics, power, signal, automotive, and semiconductor applications.
Recent developments underscore how quickly competitive positioning can shift when product innovation or capacity expansion intersects with market demand. In February 2026, Molex introduced Impress Co-Packaged Copper Solutions with a compression-based on-substrate connector and mating cable assembly supporting 224Gbps PAM-4 for high-density electronics and semiconductor interconnects. This move highlights the intensifying focus on next-generation signaling performance and packaging integration. In March 2026, IWCS identified new topics for manufacturing processes of copper and optical fiber cables and innovative cable design for electronics applications, signaling continued industry attention to process improvement and design optimization. By May 2026, Cloom Tech had strengthened its custom cable assembly manufacturing capabilities for contract production across automotive, aerospace, defense, robotics, and electronics OEMs. Around the same period, WellPCB and OurPCB launched low-cost PCB assembly and custom cable assembly services for electronics and semiconductor projects, illustrating the persistent pressure to combine cost efficiency with broad application coverage.
For strategy teams, these moves are not isolated news items. They are indicators of where capability investments are flowing, which performance thresholds are becoming table stakes, and which customer segments are attracting new competition. The full report evaluates these dynamics in greater depth, connecting recent announcements to longer-term positioning and market share implications.
Market Dynamics: Regulation, Materials, and Regional Manufacturing Realities
Cable assembly markets rarely move in isolation from regulatory frameworks, material economics, and manufacturing geography. In 2026, several forces are actively shaping operational decision-making.
On the regulatory and compliance side, industry participants continue to navigate an environment where certification and export control requirements influence both product design and market access. IEC 60079 standards and related certifications remain relevant for cable assemblies deployed in hazardous environments and industrial electronics applications, creating a barrier to entry that rewards experienced manufacturers with established quality systems. At the same time, defense and aerospace procurement activity is stimulating demand in specific niches. A recent Department of Defense solicitation related to cable assembly, posted in late May 2026 with responses due in early June, illustrates how government requirements can create short-cycle opportunities while also reinforcing the importance of compliance readiness. Compliance with US Bureau of Industry and Security Export Administration Regulations and Directorate of Defense Trade Controls requirements continues to be a critical operational consideration for firms serving sensitive end markets, including those linked to Amphenol Aerospace and related facilities.
Material conditions are equally consequential. Copper and optical fiber cables used in cable assembly manufacturing are experiencing ongoing price trends alongside supply constraints within the electronics supply chain. These pressures affect cost structures, contract negotiations, and inventory planning, especially for manufacturers balancing high-mix custom work with volume commitments. Companies that can secure stable material sourcing, optimize design for material efficiency, or align product portfolios with alternative transmission architectures may gain meaningful cost and delivery advantages.
Regional manufacturing dynamics further complicate the picture. Custom cable assembly production in China and Vietnam continues to benefit from tariff-free manufacturing advantages that support global electronics export markets. For multinational buyers and contract manufacturers alike, this creates a durable cost and logistics incentive, but it also raises strategic questions about supply-chain concentration, risk mitigation, and the balance between localized production and diversified sourcing.
These dynamics do not affect all segments uniformly. Automotive, data communication, industrial automation, and medical devices each interact with regulation, materials, and geography in different ways. The report examines those interactions in detail, helping decision-makers understand not just where demand is growing, but why it is growing there, and what constraints may shape profitability.
Why This Research Matters for 2026 Decision-Making
Enterprise strategy in the cable assembly sector requires more than knowing that the market is expanding. It requires understanding which growth paths are structurally durable, which customer requirements are escalating, and where competitive intensity will compress margin unless companies act deliberately.
The 6.12 percent compound annual growth rate projected across the forecast period is a useful framing device, but the strategic value of this research lies in what sits beneath that headline. The study connects macro momentum to the specific cable types, application verticals, and geographic segments that are driving it. It situates recent product launches, capacity expansions, symposium-level manufacturing discussions, and regulatory solicitations within a coherent competitive narrative. It also highlights material constraints and compliance requirements that can determine execution risk long before demand materializes.
Fiber Optic Cable Assembly Market
For 2026 planning, this means leadership teams can approach the market with clearer hypotheses about where to invest, how to configure sourcing and manufacturing footprints, and which customer segments warrant deeper technical engagement. The research is designed to support scenario planning, procurement strategy, partnership evaluation, and product roadmap alignment in a market where performance, cost, and compliance are increasingly intertwined.
What the Full Study Delivers
The complete Cable Assembly Market report builds on the context outlined here and extends it into a comprehensive decision-support tool. It provides detailed segmentation analysis, competitive profiling, regional demand mapping, application-specific requirements, and forward-looking scenario coverage through 2032. It also integrates market concentration data, recent developments, and industry-context signals into a single analytical structure, allowing teams to compare strategic options against a consistent evidentiary baseline.
Readers seeking the full segmentation breakdowns, region- and application-level revenue detail, and complete competitive profiles will find them in the full report. That documentation is intended for teams that need to translate market intelligence into procurement plans, capacity decisions, partnership discussions, and long-range growth models.
Cable Assembly Market
Conclusion: Positioning for Informed Growth
The cable assembly market is expanding within a landscape defined by technological acceleration, material variability, regulatory complexity, and increasingly specialized competition. In that environment, strategic advantage belongs to organizations that can read the market with precision and act before structural shifts become obvious to everyone else.
Our research is built for exactly that challenge. It provides the depth required to support credible planning in 2026, while leaving the most granular intelligence available for teams ready to commit to a complete analytical framework. For executives, strategy leaders, and market development teams seeking to align their next moves with verified market direction, the full study offers the detail, structure, and operational relevance needed to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com