

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium Metal Market Poised for 16% CAGR to Hit $7.29 Billion by 2032

The Lithium Metal Market Outlook 2026: Strategic Intelligence for Next-Generation Energy Decisions
Executive Overview
The global energy transition is entering a decisive phase where material science and supply chain resilience determine competitive advantage. Lithium metal has emerged as a foundational enabler for high-energy-density storage systems, advanced alloys, and next-generation electrochemical applications. Our latest Lithium Metal Market research provides a comprehensive, forward-looking assessment of an industry experiencing structural acceleration. With a compound annual growth rate of 16.0 percent spanning the forecast horizon through 2032, the market trajectory reflects deepening integration across battery innovation, materials engineering, and regional supply chain reconfiguration. This article outlines the strategic rationale behind the study, highlights the analytical architecture, and demonstrates how enterprise leaders can convert macro-level intelligence into actionable 2026 planning.
Macro Trajectory and Market Scale
Historical performance from 2020 through 2025 illustrates a consistent expansion pattern, with revenue climbing from 1.5 billion USD to 2.6 billion USD. The acceleration observed in the base year establishes a strong foundation for the forecast period, during which valuations are projected to move from 3.04 billion USD in 2026 toward 7.29 billion USD by 2032. This scale of growth is not merely a function of incremental demand but reflects a broader technology shift toward lithium metal anodes, high-purity metallic inputs, and specialized alloy applications.
The market structure reveals meaningful concentration dynamics. Top-tier participants collectively account for a dominant share of revenue, indicating an industry where scale, process expertise, and supply chain control create durable barriers to entry. Yet concentration does not equate to stasis. Strategic partnerships, localized production initiatives, and novel refining pathways are actively reshaping competitive positioning. For decision-makers, the critical insight lies in recognizing how concentration interacts with innovation velocity: incumbents leverage manufacturing maturity while emerging players target niche performance requirements and regional supply chain independence.
Segmentation Landscape and Application Drivers
The Lithium Metal Market unfolds across distinct product forms and end-use categories. Ingots represent the dominant volume format, serving as the primary input for downstream processing and battery manufacturing. Powder and other specialized forms cater to increasingly precise electrochemical formulations, where particle morphology, purity thresholds, and surface characteristics directly influence cell performance. This structural split underscores a broader trend: customers are no longer purchasing commoditized material alone. They are procuring tailored material properties that support specific energy-density targets, thermal behavior profiles, and cycle-life requirements.
Lithium-Metal Secondary Battery Market
Application demand is heavily anchored by battery systems, which continue to command the largest share of market absorption. Alloys and other specialized applications provide meaningful supplementary vectors, supporting advanced material combinations, thermal management strategies, and specialized engineering use cases. Importantly, the relationship between application categories and growth is not linear. Battery advancement cycles, platform qualification timelines, and form-factor transitions introduce phased demand patterns that require granular planning. Our research captures these nuances by mapping application pathways to material specifications, manufacturing readiness, and regional procurement behavior without reducing the market to oversimplified share percentages.
Regional Dynamics and Supply Chain Reconfiguration
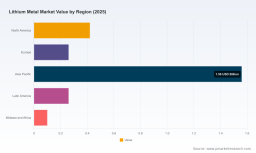
Geographically, the market reflects a diversified but unevenly distributed footprint. Asia Pacific anchors the largest portion of activity, reflecting dense manufacturing ecosystems, strong downstream demand, and rapidly scaling production capabilities. North America, Europe, Latin America, and the Middle East and Africa each contribute distinct strategic value, whether through localized supply chain initiatives, regulatory-driven procurement shifts, or specialized application clusters.
Regional analysis in this study is framed around operational realities rather than static share figures. Factors such as localized production investments, logistics constraints, material sourcing strategy, and regulatory alignment determine how demand translates into procurement decisions. The focus is on where capability is building, where dependency risks exist, and how companies can position themselves to access the right material streams under shifting trade and compliance conditions.
Recent Industry Developments and Strategic Signals
Recent operational milestones demonstrate how quickly the competitive landscape is evolving. In April 2025, a leading U.S. innovator initiated domestic production of battery-grade lithium-metal alloys and foils, establishing a fully localized, tariff-free supply chain using domestically produced alloys and sourced lithium metal. By November 2025, another vertically integrated player secured a Saudi patent covering its pure lithium metal production and lithium battery manufacturing technology, reinforcing the importance of intellectual property in advanced materials business models.
Moving into 2026,execution momentum continued. In January 2026, a sustainable refining company signed a multi-year material supply agreement for battery-grade lithium carbonate produced through its proprietary refining process, illustrating how recycling and refining innovation are being embedded directly into supply contracts. In February 2026, a composite anode materials developer and a battery technology partner formalized a memorandum of understanding to commercialize next-generation lithium-metal batteries, building on scale-up progress achieved during the prior year.
These developments share a common strategic theme: companies are reducing exposure to volatile intermediate markets by strengthening vertical integration, protecting process innovation, and securing supply agreements aligned with downstream qualification cycles. For enterprise planners, the implication is clear. Procurement strategy, partnership selection, and technology roadmapping must now account for a market where localized production, IP-protected processes, and closed-loop refining are becoming competitive differentiators.
Regulatory and Raw Material Context
Market behavior does not unfold in isolation from regulatory and commodity dynamics. Transportation compliance continues to shape logistics planning for lithium metal and lithium-ion batteries. As of January 2026, updated guidance introduced revised classification flowcharts, new test summaries, and modified state-of-charge requirements for packed equipment and lithium metal battery shipments. These changes affect packaging design, freight qualification, warehousing protocols, and cross-border shipment timelines. Firms that treat compliance as a static checklist risk operational friction; firms that integrate regulatory evolution into product launch planning and supply chain design gain predictability.
Raw material pricing also remains a relevant planning input. Market data from mid-2026 indicates lithium carbonate pricing declining to approximately 163,000 CNY per ton, reflecting a month-over-month contraction. While lithium metal markets are not perfectly synchronized with carbonate pricing, such movements influence input cost expectations, procurement timing, contract negotiation posture, and internal investment hurdle rates. The relationship is nuanced: different product forms, purity specifications, and supply routes create varying degrees of exposure. Our research addresses these sensitivities by examining how pricing trends interact with material grade requirements, regional sourcing options, and long-term contract structures.
Competitive Landscape: Differentiated Capabilities and Strategic Positioning
The competitive field spans established multinationals, specialty materials innovators, and vertically integrated challengers. Each participant is shaping the market through a distinct value proposition.
- Albemarle Corporation emphasizes ultra-thin lithium metal anodes designed for high-energy-density solid-state and lithium-metal battery platforms, positioning process precision as a performance enabler.
- Ganfeng Lithium Group Co., Ltd. focuses on high-purity lithium metal produced via oil-free vacuum melting and low-temperature vacuum distillation, reflecting an emphasis on purity control and process discipline.
- Pure Lithium Corporation pursues vertically integrated pure lithium metal anodes and batteries using brine-to-battery technology, linking upstream sourcing directly to downstream cell production.
- Lyten Inc. targets battery-grade lithium-metal alloys and foils for U.S.-localized lithium-sulfur batteries, aligning material development with regional supply chain objectives.
- Aqua Metals, Inc. contributes battery-grade lithium carbonate and nickel metal through its AquaRefining process, integrating sustainable recycling and refining into the material supply chain.
- Soelect advances lithium-metal composite anode materials for advanced high-energy-density batteries, focusing on material formulations that support next-generation cell architectures.
- Elevated Materials develops ultra-thin lithium metal films for commercial battery programs, addressing the growing demand for precision-format metallic inputs.
- Cuberg concentrates on lithium-metal cell technology for ultra-safe, high-energy-density modules in aviation and vertical takeoff and landing applications, linking material performance to demanding transport and mobility requirements.
The strategic takeaway is not simply that competition is intense, but that competition is multidimensional. Some players compete on purity and process control. Others compete on integration, localization, recycling, or application-specific cell architecture. As a result, procurement teams and technology strategists must evaluate partners against more than volume or price. Material consistency, qualification support, IP positioning, and supply continuity under regulatory change are equally relevant.
What the Report Delivers: Operational Intelligence for 2026 Planning
This study is designed as a decision-support instrument, not a broad overview. It translates market-scale data into operational context by mapping growth vectors to the practical questions enterprise teams face when planning for 2026 and beyond. The report includes analysis covering demand drivers by application pathway, product-form preferences and their manufacturing implications, regional capability building and procurement relevance, and competitive positioning based on technology readiness, integration strategy, and supply chain design.
Beyond structural assessment, the report integrates development tracking that connects corporate milestones to market consequences. Patent grants, localized production launches, multi-year supply agreements, and commercialization partnerships are examined for what they reveal about capability maturity, supply chain directionality, and the pace of market entry. Regulatory updates and raw material pricing movements are incorporated where they affect planning assumptions, with attention to how compliance shifts influence logistics and how input cost dynamics shape negotiation and sourcing strategy.
The objective is to give strategy, procurement, and technology leaders a coherent framework for evaluating opportunity, risk, and timing. Rather than leaving decision-makers with isolated figures, the study provides the connective tissue needed to interpret growth in terms of actionable market behavior: which material specifications are gaining relevance, where regional supply chain shifts are accelerating, how concentration affects access and negotiation leverage, and which development patterns indicate near-term capacity or partnership opportunities.
Lithium Metal Market
Strategic Implications for 2026 Enterprise Decisions
For organizations operating in or adjacent to the Lithium Metal Market, the 2026 planning cycle should be informed by three overarching priorities. First, align material sourcing with technology roadmaps. As battery platforms and alloy formulations continue to advance, procurement specifications increasingly need to reflect performance-sensitive characteristics rather than generic commodity procurement.
Second, incorporate regulatory and logistics evolution into product and supply planning. Updated transportation guidance, classification requirements, and state-of-charge constraints affect launch timing, packaging design, and distribution strategy. Companies that build compliance-aware supply planning into their operational cadence reduce execution risk.
Third, evaluate partnership and investment choices through the lens of integration and differentiation. Vertical integration, localized production, sustainable refining, and IP-protected processing are no longer peripheral initiatives. They are becoming core elements of supply reliability and competitive positioning. The market concentration pattern reinforces the importance of selecting partners with credible scale, process control, and continuity strategy, while the emergence of specialized innovators signals where tailored solutions and application-specific alliances may create advantage.
Conclusion
The Lithium Metal Market is moving with sufficient velocity and structural complexity that broad narratives are no longer sufficient for high-stakes planning. Growth, concentration, regional reconfiguration, regulatory updates, and corporate execution are interacting in ways that require a more disciplined intelligence framework. Our research provides that framework by linking macro trajectory to operational relevance, translating recent developments into strategic signals, and identifying the decision points that matter most for 2026.
For leaders who need the full analytical breakdown—detailed segmentation interpretation, regional capability mapping, competitive profiling, regulatory impact assessment, and development tracking with market implications—the complete report offers the depth required to convert insight into action. The market is expanding, differentiating, and reorganizing around integration, purity, localization, and application specificity. Access the full study to ground your next planning cycle in comprehensive, decision-ready intelligence.
For detailed analysis of this topic, please visit the official page: Lithium Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com